• Home
  • About Us
  • Contact Us
  • Cookies Policy
  • Disclaimer
  • DMCA
  • Privacy Policy
  • Terms and Conditions
Dr Crypton
Secure Your Future in Crypto
Bitcoin & Altcoins

Kraken Expands US Market Presence with Launch of CFTC-Regulated Kraken Borrow Platform

by admin September 24, 2026
written by admin

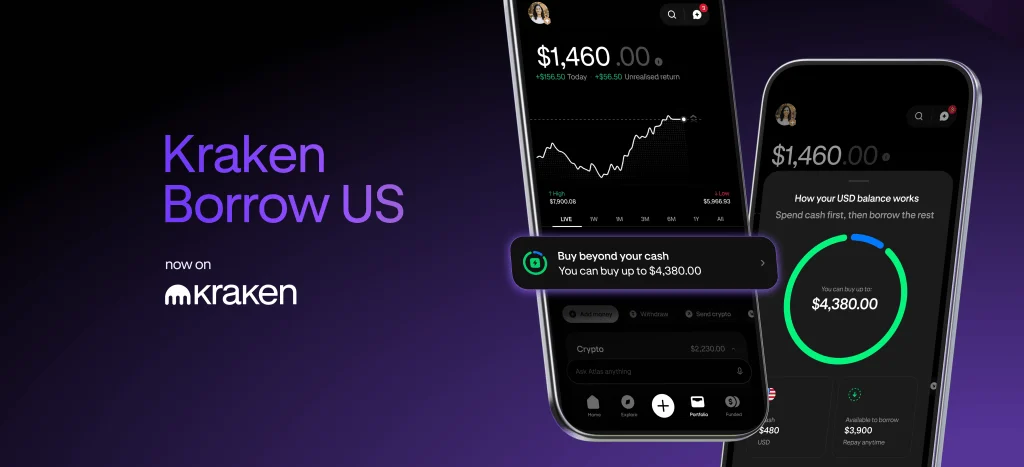
Major cryptocurrency exchange Kraken has officially announced the rollout of Kraken Borrow US, a new financial service enabling eligible United States customers to execute leveraged cryptocurrency purchases backed by their existing portfolios. Operating across 48 states at launch—with exclusions for residents of New York and Maine—the product introduces a unified spending metric that integrates a user’s available cash balance with a dynamic borrowing capacity. This development marks a significant expansion of Kraken’s regulated product offerings in the US, providing traders with advanced financial instruments structured within strict regulatory frameworks.

The launch comes at a time of evolving regulatory scrutiny and adaptation within the digital asset sector. By anchoring the borrowing mechanism on rails regulated by the Commodity Futures Trading Commission (CFTC), Kraken aims to provide a compliant pathway for retail and institutional participants to leverage their digital assets. The service is designed to streamline the purchasing process, allowing users to buy digital currencies in amounts that exceed their immediate fiat currency holdings by utilizing their broader asset base as collateral.

Mechanics of Kraken Borrow US and Unified Buying Power

At the core of Kraken Borrow US is a consolidated spending metric termed "buying power." This figure represents the sum of a user’s available U.S. dollar (USD) balance combined with their maximum eligible borrowing capacity. When a customer initiates a purchase, the platform prioritizes the utilization of their actual cash reserves before activating any borrowed funds.

For transactions that exceed the available cash balance, the purchase is split into two distinct operational components behind the scenes. The first component executes as a standard spot trade using the user’s U.S. dollars, facilitated by Payward Interactive, Inc. The second component handles the borrowed portion through a spot margin transaction executed on CFTC-regulated rails, offered through NinjaTrader Clearing, LLC—operating as Kraken Derivatives US—a registered Futures Commission Merchant and member of the National Futures Association.

Under the current parameters of the launch, Kraken Borrow US supports 27 distinct trading pairs on Bitnomial, all subject to a uniform leverage cap. Users can leverage up to three times (3x) the value of their eligible assets. To support this capacity, Kraken has designated more than 48 digital assets as eligible collateral, allowing users to leverage a diverse portfolio of holdings to secure additional purchasing capability.

Transaction Review and Risk Management Protocols

Transparency and risk awareness form foundational elements of the Kraken Borrow US interface. Prior to the final execution of any transaction that incorporates borrowed funds, users are presented with a comprehensive review screen detailing the financial commitments, fee structures, and the exact proportion of the trade funded by credit versus cash.

To maintain transparency throughout the lifecycle of a loan, Kraken has implemented a real-time account monitoring indicator known as "borrow health." This indicator classifies a user’s financial standing into one of three categories: Healthy, Caution, or At risk.

The borrow health status fluctuates in response to broader market movements. If the market value of the collateral assets declines significantly relative to the outstanding borrowed amount, the system shifts the account status to provide early warnings. In scenarios where market depreciation continues and the position deteriorates beyond acceptable risk thresholds, the platform is authorized to execute automatic liquidations of a portion of the user’s cryptocurrency holdings to cover the outstanding debt.

Furthermore, crypto assets purchased using borrowed funds are subjected to a security lock. These assets remain visible within the user’s portfolio and can be sold directly through the platform to facilitate repayment, but they cannot be withdrawn or transferred out of the Kraken ecosystem while an outstanding loan balance remains attached to them.

Repayment Structure and Terms

Unlike traditional financial credit products that often enforce rigid repayment schedules or mandate recurring monthly minimums, Kraken Borrow US introduces a flexible repayment model. Users face no mandatory repayment deadlines or minimum installment requirements. Outstanding balances can be settled at the user’s discretion through the platform’s dedicated Borrow Center.

This flexibility is intended to accommodate the volatility inherent in digital asset markets, giving traders the ability to manage their leverage without the immediate pressure of calendar-based deadlines. However, the absence of a fixed schedule places increased responsibility on the user to actively monitor their borrow health and market trends to prevent automated liquidation events.

Eligibility Criteria and Onboarding Process

Access to Kraken Borrow US is subject to specific regulatory and geographical constraints. The service is accessible to verified users residing in 48 U.S. states. Alongside the geographic exclusions of New York and Maine, participation is restricted for individuals whose total investments exceed $10 million under applicable commodities laws, aligning with regulatory definitions designed to segment retail and high-net-worth institutional compliance frameworks.

For eligible users engaging with the service for the first time, Kraken has designed a streamlined, one-time onboarding workflow. During the initial purchase that exceeds their cash balance, users are prompted to review specific regulatory disclosures and provide an electronic signature to open an associated Kraken Derivatives US account. Existing verified account details automatically carry over, minimizing friction during the setup process.

Once activated, users can view their buying power directly within the standard purchasing interface, on the portfolio overview page, or inside the Borrow Center.

Broader Implications for the US Crypto Derivatives Market

The introduction of Kraken Borrow US reflects a broader industry trend toward integrated, regulated margin products within the United States. As regulatory agencies such as the CFTC and the Securities and Exchange Commission (SEC) continue to shape the operational boundaries for digital asset service providers, exchanges are increasingly compelled to partner with registered entities to deliver leverage products.

By utilizing NinjaTrader Clearing as the clearing broker and aligning with CFTC-regulated infrastructure, Kraken is positioning its offerings within a compliant framework designed to withstand regulatory scrutiny. This approach contrasts with historical offshore margin trading models that operated outside formal regulatory oversight, offering a safer, albeit more restricted, environment for domestic participants.

Market analysts note that the ability to leverage existing asset portfolios up to 3x without immediate cash injections could increase capital efficiency for active retail traders. However, financial experts emphasize the inherent risks associated with leveraged trading in volatile asset classes. Because losses can exceed initial investments and require rapid deployment of additional collateral, market participants are advised to exercise caution and deploy only risk capital that they can afford to lose without impacting their financial security.

As Kraken continues to roll out features under its expanding suite of financial products—including distinct offerings like Kraken Borrow and Kraken Flexline—the company aims to solidify its market share by bridging traditional derivative market mechanics with contemporary cryptocurrency trading infrastructure. The success of Kraken Borrow US will likely serve as a benchmark for how regulated exchanges can safely administer leverage to U.S. retail investors moving forward.
September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
Bitcoin & Altcoins

The Digital Asset Market Clarity Act Stalls in Senate Amid Banking Sector Opposition and Evolving Federal Stablecoin Strategy

by admin September 24, 2026
written by admin

The Digital Asset Market Clarity Act, a landmark legislative effort designed to provide a comprehensive regulatory framework for the burgeoning virtual asset sector, has hit a significant roadblock in the United States Senate. Despite successfully navigating the committee process, the bill has stalled, leaving stakeholders in the digital asset space and the traditional financial sector in a state of regulatory limbo. The failure to advance the legislation is currently being attributed to intense lobbying efforts by major financial institutions, which view the rise of stablecoins as a direct threat to the traditional deposit-based banking model.

The Legislative Impasse

The CLARITY Act was envisioned as the definitive solution to the fragmented and often ambiguous regulatory landscape currently governing digital assets in the United States. Its primary objective was to delineate the jurisdictional boundaries between federal agencies—specifically the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC)—thereby providing clarity for issuers and users of virtual assets, particularly stablecoins.

However, the path to the Senate floor has been obstructed. Patrick Witt, a senior crypto adviser within the White House, has publicly identified the influence of large-scale commercial banks as the decisive factor in the bill’s stagnation. According to Witt, traditional banks have expressed deep-seated anxieties that stablecoins, if permitted to proliferate under a clear regulatory framework, would inevitably siphon liquidity away from conventional bank deposits.

This concern centers on the fundamental nature of stablecoins as dollar-denominated digital assets. Banks argue that if consumers move their capital from interest-bearing or standard savings accounts into stablecoins—which serve as a convenient medium of exchange for the digital economy—the resulting deposit outflows could impair the ability of banks to extend credit and manage their balance sheets. Even though the draft legislation included explicit guardrails, such as a prohibition on the payment of interest on certain types of stablecoins, the banking sector remained unconvinced, successfully marshaling opposition to block further progress.

A Chronology of the Regulatory Standstill

The current legislative friction is the latest chapter in a multi-year effort to harmonize crypto regulation.

  • Early 2023: Initial discussions regarding the CLARITY Act begin in earnest, fueled by a series of high-profile collapses in the crypto market that highlighted the urgent need for consumer protections.
  • Mid-2023: The legislative text is drafted, focusing on defining stablecoin issuers and separating regulatory oversight between the SEC and CFTC.
  • Early 2024: The bill enters the committee phase, where it receives cautious support from bipartisan members who acknowledge the necessity of bringing digital assets under a federal umbrella.
  • Last Week: The bill reaches a critical juncture in the Senate, where it abruptly stalls. Reports emerge of intensified lobbying from banking trade associations, shifting the momentum against the bill.
  • Present Day: Regulatory uncertainty persists. Federal agencies continue to operate under existing enforcement-led paradigms, while the administration pivots toward exploring administrative, rather than purely legislative, paths for stablecoin integration.

The Bank-Stablecoin Conflict: A Structural Divide

The impasse highlights an escalating philosophical and structural divide between the traditional financial establishment and the burgeoning crypto-native industry. At the heart of this conflict is the concept of "disintermediation."

Traditional banks function as intermediaries that utilize customer deposits to fund long-term lending. Stablecoins, by contrast, are designed to facilitate frictionless, near-instantaneous value transfer across global digital networks. Proponents of the crypto industry argue that stablecoins are an evolution of the payment rail, capable of lowering costs for cross-border remittances and expanding financial inclusion.

Conversely, banking groups have issued formal advisories warning that if stablecoins are treated as a near-substitute for bank deposits, they could undermine the efficacy of monetary policy transmission. If a significant volume of U.S. dollar liquidity moves off bank balance sheets and into private, non-bank-issued stablecoin reserves, the Federal Reserve’s influence over the money supply could be complicated. Furthermore, the risk of "run-on-the-bank" scenarios is cited as a significant concern, necessitating the strict regulatory oversight that the banking sector currently faces, but which stablecoin issuers currently evade.

The Federal Administration’s Dual-Track Strategy

While the legislative process has faltered, the U.S. government has not abandoned the underlying objective of integrating stablecoins into the broader financial system. There is an emerging, parallel effort involving the Treasury Department, the State Department, and various other agencies to explore the issuance and promotion of dollar-backed stablecoins.

This initiative is driven by a mix of economic and geopolitical considerations. As other major economies, including the People’s Republic of China and various European nations, make strides in developing their own central bank digital currencies (CBDCs) or regulated private stablecoin ecosystems, the United States is keen to maintain the primacy of the U.S. dollar.

By fostering a environment where dollar-backed stablecoins can thrive, the U.S. aims to bolster demand for U.S. Treasury securities. Because most high-quality stablecoins are backed by short-term Treasury bills, increased adoption of these digital assets effectively creates a new, high-velocity demand channel for American debt. This serves a dual purpose: it strengthens the global status of the dollar as the premier digital unit of account and provides the federal government with a strategic advantage in the ongoing competition for dominance in the global digital payments space.

Ethics and Oversight: A Wider Debate

In his critique of the current stalemate, Patrick Witt expanded the conversation beyond the CLARITY Act, addressing the broader climate of political ethics. He characterized the administration’s existing regulations on crypto holdings as the most stringent in history, while simultaneously calling out the perceived hypocrisy among some legislators. Witt pointed to the ongoing issue of congressional stock trading, suggesting that members of the Senate who oversee the financial sector should be held to the same, if not higher, standards of transparency and conflict-of-interest mitigation as those applied to digital asset participants.

This commentary underscores a growing sentiment among industry advocates that the regulatory skepticism directed toward crypto is not solely rooted in financial stability concerns, but is also influenced by political posturing and the protection of entrenched interests.

Broader Implications and Future Outlook

The failure to pass the CLARITY Act leaves a significant void in the American regulatory framework. For the foreseeable future, firms operating in the virtual asset space will remain subject to the "regulation by enforcement" approach that has defined the tenure of the current SEC leadership. This environment creates operational hurdles for businesses that prioritize compliance, as they must navigate conflicting court rulings and agency guidelines rather than a coherent federal statute.

The implications for consumers are equally significant. Without federal standards, users of stablecoins lack the uniform protections—such as mandatory reserve audits, insurance-like guarantees, and liquidity requirements—that a bill like the CLARITY Act would have codified. While the market remains resilient, as evidenced by the optimistic reactions of individual retail participants on social media platforms, the lack of institutional clarity may deter the entry of more conservative capital.

Looking ahead, the policy debate is set to shift from the Senate floor to the regulatory offices of the SEC, the Treasury, and the Federal Reserve. Policymakers must now weigh the competing demands of banking sector protection, national economic security through the dollar’s digital expansion, and the need to foster innovation. Whether the government can reconcile these interests without the backing of a clear legislative mandate remains the defining question for the U.S. digital asset market in the coming months.

As the debate continues, the focus will likely remain on whether the U.S. can create a framework that manages systemic risk without stifling the technological advancements that stablecoins offer. For now, the stalemate serves as a stark reminder of the influence of legacy financial institutions and the complexities inherent in modernizing the global financial architecture.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
Web3 & DApps

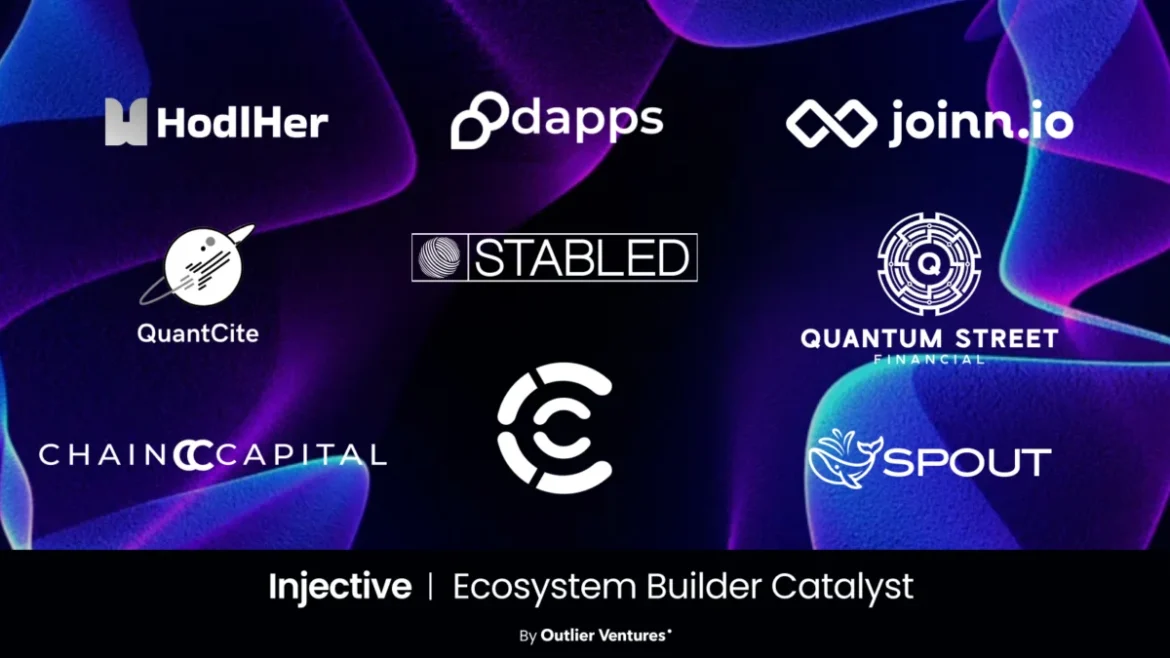
Outlier Ventures and Injective Unveil the Next Wave of Financial Innovation with the Injective Ecosystem Builder Catalyst Cohort

by admin September 24, 2026
written by admin

The landscape of decentralized finance (DeFi) is undergoing a structural evolution, transitioning away from rudimentary token-swapping mechanisms toward a highly sophisticated, institutional-grade financial ecosystem. Against this backdrop of rapid technological advancement, global Web3 accelerator Outlier Ventures and Layer-1 blockchain Injective have officially announced their latest collaborative initiative: the Injective Ecosystem Builder Catalyst cohort.

This intensive nine-week virtual accelerator program has been meticulously designed to identify, mentor, and back the next generation of high-growth decentralized finance and infrastructure startups building natively within the Injective ecosystem. The announcement arrives at a pivotal juncture for the broader digital asset economy, as decentralized finance Total Value Locked (TVL) approaches historical milestones and the integration of real-world assets (RWAs) accelerates across public blockchains. Through this strategic partnership, Outlier Ventures and Injective aim to supply emerging founders with the critical technical resources, institutional mentorship, and liquidity frameworks required to scale disruptive financial products globally.

The Genesis and Strategic Importance of the Accelerator

The launch of the Injective Ecosystem Builder Catalyst cohort underscores a broader shift in the digital asset sector toward high-performance, purpose-built infrastructure. For years, decentralized finance was constrained by slow transaction finality, high gas fees, and fragmented liquidity silos across disparate blockchain networks. However, the maturation of networks featuring sub-second block times, gasless transactions, and robust MultiVM interoperability has created a fertile ground for a truly "DeFi-first" environment.

The timing of this cohort is closely aligned with broader macro-crypto trends. Industry metrics indicate that aggregate DeFi TVL has hovered near the $140 billion threshold, while the tokenization and integration of Real-World Assets have expanded by more than 380% since 2022. This exponential growth signals an irreversible convergence between traditional finance (TradFi) and decentralized infrastructure.

Rather than simply porting legacy financial instruments onto a blockchain ledger, the founders selected for the Injective Catalyst cohort are engineering entirely new financial primitives. Leveraging Injective’s specialized financial modules, shared liquidity architecture, and high-speed execution layer, these startups are introducing innovations such as agentic trading systems, automated on-chain repo markets, and tokenized equity lending protocols that remain impossible within the confines of legacy financial systems.

Inside the Cohort: Nine Startups Reshaping the Financial Stack

The newly unveiled cohort comprises a diverse array of nine early-stage ventures spanning institutional trading infrastructure, consumer fintech, decentralized exchanges, international payments, and AI-driven Web3 operating systems. Each participant was chosen for their ability to leverage Injective’s native architecture to drive capital efficiency and solve complex friction points in global finance.

Institutional Trading and Execution: QuantCite

QuantCite enters the ecosystem as an institutional-grade Order and Execution Management System (OEMS) equipped with advanced smart-routing capabilities. Designed specifically for quantitative funds and professional traders, the platform unifies trade execution across both centralized exchanges and decentralized venues. By bridging these liquidity divides, QuantCite aims to provide institutional participants with the high-performance infrastructure necessary to execute complex trading strategies without encountering liquidity fragmentation.

Consumer Fintech and Emerging Markets: Joinn

9 Startups Selected for the Injective Ecosystem Builder Catalyst: Scaling the DeFi-First Future

Addressing the friction of wealth accumulation in emerging markets, Joinn functions as a fintech application that enables everyday users to access stable, yield-generating tokenized financial assets. Despite operating on secure blockchain rails with cross-chain, gasless, and signless transactions, the application maintains a familiar Web2 user experience. Featuring 24/7 access, an integrated Visa card experience, and a dedicated artificial intelligence agent, Joinn is designed to simplify compound wealth generation for retail demographics outside traditional banking hubs.

Decentralized Liquidity and Aggregation: Choice

Choice serves as a specialized decentralized exchange and liquidity aggregation layer optimized exclusively for the Injective network. By deploying a novel routing algorithm capable of tapping into liquidity pools across all available venues within the ecosystem, Choice guarantees users optimal swap execution while simultaneously mitigating price slippage—a persistent challenge for high-volume decentralized traders.

Cross-Border Corporate Payments: Stabled

Targeting the inefficiencies of international business transactions, Stabled offers a cross-border payments platform that facilitates compliant stablecoin settlements. The platform is engineered to eliminate reliance on legacy correspondent banking networks, drastically reducing foreign exchange (FX) losses and eliminating multi-day settlement delays for global enterprises.

Real-World Asset Tokenization: Quantum Street

Comprising capital market veterans and financial engineering specialists, Quantum Street focuses on bridging off-chain assets into the on-chain economy. By structuring transactions derived from cash-flowing corporate businesses, Quantum Street introduces tangible utility to stablecoins while driving organic Total Value Locked (TVL) growth within the Injective ecosystem.

Equity Markets and Margin Lending: Spout

Spout seeks to revolutionize the traditional equities market by introducing a decentralized borrowing and lending marketplace for U.S. public equities. Through the tokenization of equities and the implementation of a Collateralized Debt Position (CDP) model, Spout enables users to access 0.0% APR margin loans while simultaneously offering lenders yields of approximately 10% APY.

Web3 Social Economies and Creator Monetization: Dapps.co

Dapps.co addresses the monetization and agency challenges faced by digital creators through a Web3-native social network underpinned by tokenized communities and on-chain economies. The platform integrates an artificial intelligence provenance layer designed to combat low-quality generated content, empowering creators to monetize their work directly through transparent tipping mechanisms and paid direct messaging channels.

Private Debt Securitization: Chain Capital

9 Startups Selected for the Injective Ecosystem Builder Catalyst: Scaling the DeFi-First Future

Chain Capital transforms historically illiquid private debt assets into tradable, on-chain securities. By tokenizing invoices and corporate receivables, the platform automates the complex securitization workflow. According to project metrics, this automation reduces middle-office operational costs by up to 75% while granting institutional investors compliant access to high-yield fixed-income exposures.

Artificial Intelligence and Web3 Operating Systems: HodlHer

Positioned as the world’s first AI-driven Web3 operating system built natively on Injective, HodlHer utilizes intelligent artificial intelligence personas to assist users, creators, and protocols. The system is designed to streamline the complete lifecycle of on-chain interaction, spanning perception, analytical reasoning, and automated execution.

Chronology and Program Structure

The Injective Ecosystem Builder Catalyst is structured as a rigorous, immersive nine-week curriculum. Throughout the accelerator, participating founders receive hands-on mentorship from industry veterans, specialized legal and regulatory guidance, and direct access to ecosystem incentive programs designed to fast-track product development and market deployment.

The program operates on a distinct timeline leading toward a public showcase:

  • Week 1–3: Product refinement, technical architecture optimization utilizing Injective’s native financial modules, and smart contract security reviews.
  • Week 4–6: Strategic advisory sessions focusing on regulatory compliance, tokenomics design, and cross-chain interoperability testing.
  • Week 7–8: Go-to-market strategy execution, investor pitch preparation, and liquidity partner integrations.
  • Week 9: Culmination of the accelerator marked by the official Injective Ecosystem Builder Catalyst Demo Day, scheduled for February 25, 2026.

Industry Implications and the Future of Composability

The launch of this cohort reflects a broader philosophical maturation within the decentralized finance sector. Industry analysts note that future growth will depend less on the sheer proliferation of speculative tokens and more on system interoperability, architectural fit, and financial composability.

Injective’s technical architecture—which provides functional parity with traditional financial order books and collateral management systems while retaining the permissionless nature of public blockchains—enables financial strategies that remain fundamentally impossible within legacy banking frameworks. By pairing this infrastructure with Outlier Ventures’ extensive track record in venture acceleration, the Catalyst cohort is positioned to produce companies capable of scaling beyond crypto-native audiences into mainstream financial markets.

As the accelerator progresses toward its upcoming Demo Day, industry participants and institutional investors alike are closely monitoring the cohort. With global interest in tokenized assets, high-performance execution layers, and institutional DeFi accelerating, the technological outputs of the Injective Ecosystem Builder Catalyst are expected to significantly influence the trajectory of financial technology throughout 2026 and beyond. Stakeholders and interested parties can register for the upcoming Demo Day event via Outlier Ventures’ official channels on Luma.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
Cryptography & Privacy

AI Is Poised to Make Software Too Secure, Setting Up a Clash Between National Security and Tech Giants

by admin September 24, 2026
written by admin

The rapid integration of artificial intelligence into software development lifecycles is fundamentally shifting the balance of power between cybersecurity defenders and government intelligence agencies. Emerging frontier models developed by firms such as Anthropic, OpenAI, and various open-weight labs across the globe possess advanced code-analysis capabilities that fundamentally alter the landscape of vulnerability discovery. While long-awaited by enterprise security professionals seeking to rid codebases of decades-old bugs, this technological leap introduces a paradoxical crisis for law enforcement. As automated systems systematically eradicate software vulnerabilities, intelligence agencies face the prospect of a permanent "going dark" scenario. This potential shift threatens to upend a decade-long status quo where digital surveillance heavily relied on offensive cyber exploits to bypass end-to-end encryption.

A Chronology of Surveillance and Encryption: From Wiretaps to Zero-Days

To understand the current friction between technological advancement and state surveillance, it is necessary to examine the evolution of digital communication over the past two decades. In the early 2000s, electronic surveillance largely mirrored the paradigms depicted in media snapshots like the television series The Wire, relying heavily on traditional wiretaps, physical tracking, and easily intercepted telephonic communications.

The proliferation of smartphones in the late 2000s fundamentally altered this landscape. As mobile devices transformed from simple communication tools into repositories for personal data, law enforcement agencies adapted by shifting focus toward digital forensics and physical device extractions. This dynamic changed dramatically in 2010 when Apple introduced passcode-derived encryption for iPhone storage, a standard rapidly adopted by Android ecosystems. By 2011, end-to-end encryption expanded to messaging platforms, culminating by 2016 in nearly a billion global users utilizing default encrypted messaging services like WhatsApp.

Faced with a rapidly closing window of observability, the U.S. Federal Bureau of Investigation launched the "Going Dark" initiative in 2014, attempting to compel technology providers to build lawful interception capabilities directly into their architectures. The tension culminated in the 2016 legal battle between Apple and the FBI following the San Bernardino shooting, where the government sought to force the creation of a software backdoor. Although that specific legal showdown was short-circuited by an outside vendor demonstrating the ability to independently exploit the device, it established a precedent: rather than compelling backdoors, intelligence and law enforcement agencies increasingly relied on purchasing and deploying commercial zero-day exploits—such as those developed by NSO Group—to target securely encrypted devices.

Everything is about to “go dark”

The Rise of Autonomous Vulnerability Discovery

This era of offensive exploitation is now drawing to a close due to rapid breakthroughs in artificial intelligence. In early 2026, the introduction of advanced frontier models specifically optimized for cyber operations—such as Anthropic’s Mythos, alongside comparable models from OpenAI and international labs like Z.ai and Moonshot—demonstrated unprecedented efficacy in identifying deep-seated software vulnerabilities.

Initially, these capabilities prompted defensive geopolitical moves, including temporary export restrictions by the U.S. government on high-capability cyber models. However, the proliferation of open-weight alternatives made technological monopolies impossible to maintain. As these AI systems are integrated into Continuous Integration and Continuous Deployment (CI/CD) toolchains, software development pipelines are shifting from reactive patching to proactive, automated eradication of flaws.

Industry analysts project that within the next two years, major enterprise software will experience a dramatic reduction in remotely exploitable vulnerabilities. Codebases that historically harbored decades of latent bugs are undergoing comprehensive remediation, effectively sealing the digital attack surfaces that law enforcement agencies and intelligence services have historically relied upon to conduct authorized surveillance.

Implications for Law Enforcement and National Security

The impending scarcity of software vulnerabilities presents a profound dilemma for public safety and national security organizations. Without reliable access to zero-day exploits or functional security flaws, intelligence agencies will likely find their technical surveillance capabilities severely degraded.

Everything is about to “go dark”

This technological shift is expected to revive intense policy debates regarding "exceptional access" and mandatory backdoors. Cybersecurity experts have long warned that mandated cryptographic vulnerabilities weaken overall infrastructure, making systems susceptible to hostile foreign adversaries and criminal syndicates. The renewed pressure from governments to re-architect systems for lawful access could trigger a wedge in the global technology market, potentially driving international enterprises and foreign governments to decouple entirely from U.S.-developed software ecosystems to ensure their own sovereign security.

Furthermore, domestic adoption of mandated backdoors risks disproportionately compromising the cybersecurity posture of the nations implementing them, leaving local critical infrastructure vulnerable to sophisticated foreign espionage while providing diminishing returns against highly sophisticated criminal networks that already utilize isolated, custom communications architectures.

Path Forward and Industry Outlook

As the software industry approaches an inflection point defined by hyper-secure code and automated threat mitigation, policymakers and cybersecurity professionals face unprecedented strategic questions. Unlike previous transitions in encryption standards, the shift toward AI-driven software hardening is occurring autonomously and at scale.

Navigating this transition will require a fundamental recalibration of cybersecurity policy, moving away from reliance on offensive exploitation and toward resilient, zero-trust architectures that account for a world where traditional software vulnerabilities are effectively engineered out of existence. The long-term consequences of this systemic security upgrade remain uncertain, forcing both the private sector and government agencies to adapt to an environment where digital surveillance capabilities are permanently constrained by mathematically sound, AI-verified code.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

LoanPro Brings Payments Card Disbursement and AI Servicing Into One Lending Platform to Cut the Cost of Servicing

by admin September 24, 2026
written by admin

The landscape of modern lending is undergoing a profound transformation as Utah-based financial technology firm LoanPro announced a sweeping expansion of its core platform this week. By integrating payment processing, real-time card-based disbursements, and advanced artificial intelligence (AI) servicing tools into a unified ecosystem, the company is aiming to reduce the operational fragmentation that has long plagued traditional lenders. This strategic pivot represents a move toward "all-in-one" infrastructure, designed to minimize the reliance on disparate third-party vendors and streamline the complex lifecycle of credit management.

The Evolution of the LoanPro Ecosystem

Founded in 2015, LoanPro has steadily built a reputation for automating complex financial workflows, serving a diverse clientele ranging from banks and auto lenders to specialty credit providers. The latest suite of product launches—which includes LoanPro DirectPay, the Beyond Credit virtual card, and a proprietary Model Context Protocol (MCP)—is perhaps the most significant operational expansion in the firm’s history.

For years, the lending industry has operated under a model defined by "vendor sprawl." A single lender might use one software provider for loan origination, another for payment processing, and a third for communication or AI analytics. This fragmentation creates data silos, increases costs, and introduces security vulnerabilities. LoanPro’s new initiative seeks to collapse these silos, offering lenders a centralized environment where every interaction—from the initial disbursement of funds to the final payment and eventual collection—is captured under a single audit trail.

Key Technological Advancements

The core of the announcement rests on three distinct pillars:

  1. LoanPro Payments and DirectPay: By rebranding its payment suite to LoanPro Payments and introducing DirectPay, the company is positioning itself as a central clearinghouse for loan funds. With approximately $4 billion in monthly transaction volume flowing through the system, the platform provides granular visibility into the payment lifecycle. Loan officers can now diagnose failed transactions or process disputes without exiting the platform, saving valuable time and reducing customer friction.
  2. Beyond Credit (Virtual Mastercard): This feature marks a significant departure from traditional disbursement methods. By leveraging a virtual Mastercard, lenders can issue installment loan funds that borrowers access through digital wallets like Apple Pay or Google Pay. The utility lies in the "programmable money" aspect; lenders can restrict where funds are spent by merchant ID, category code, or location, ensuring that borrowed funds are used for their intended purposes, such as medical expenses or home improvements.
  3. The Intelligence Suite and MCP: Perhaps the most forward-looking component is the Model Context Protocol. As generative AI becomes more prevalent in financial services, lenders have been hesitant to deploy "agentic AI" due to compliance and oversight concerns. The MCP allows lenders to plug in their choice of AI models while ensuring those agents remain tethered to the same role-based access controls and compliance guardrails used by human staff.

Strategic Partnerships and Operational Synergy

To support these ambitious updates, LoanPro has deepened its infrastructure through strategic partnerships with Moov and CheckAlt. These collaborations enhance the firm’s backend processing capabilities, ensuring that payments are not only secure but also high-speed.

The integration of these partners into the LoanPro environment allows for real-time disbursement, a critical feature in a consumer market that increasingly demands instantaneous access to credit. As CEO Rhett Roberts noted, the ability for a lender to move funds to a borrower on a Friday night—or have an AI agent provide real-time account updates—is no longer a luxury, but a competitive necessity.

Chronology of Growth

  • 2015: LoanPro is founded with a mission to modernize loan management systems for the digital age.
  • 2021: The company gains significant industry recognition through appearances at FinDEVr 2021 and FinovateSpring 2021, showcasing its early strides in loan management automation.
  • 2024–2025: Throughout this period, the company focuses on expanding its API-first approach, setting the stage for the full-stack integration announced in late 2026.
  • September 2026: The company launches its integrated Payments, Beyond Credit, and AI-assisted servicing suites, marking its transition to a comprehensive, all-in-one lending ecosystem.

Analysis: The Governance of Agentic AI

The introduction of the Model Context Protocol addresses a growing tension in fintech: the balance between the efficiency of artificial intelligence and the rigidity of regulatory compliance. Many institutions are eager to deploy AI to summarize loan health or suggest next steps for servicing agents, but they fear the "black box" nature of these models.

LoanPro’s strategy is to treat AI agents as digital employees. By routing AI decisions through existing audit trails and compliance frameworks, the company offers a "compliance-first" approach to automation. This is a critical development for the banking sector, where any automated action must be fully transparent and attributable to a specific policy or individual oversight. As Colin Terry, LoanPro’s Chief Product Officer, aptly stated, lenders can only move as fast as they trust their "brakes." By embedding AI within a robust governance layer, LoanPro provides the brakes necessary for lenders to accelerate their digital transformation.

Broader Implications for the Lending Market

The consolidation of services into a single platform has broader implications for the fintech industry. For mid-to-large lenders, managing dozens of software integrations is a massive operational burden that incurs both direct costs and "hidden" costs related to data synchronization errors.

By offering a platform that handles the entire loan lifecycle, LoanPro is challenging the traditional best-of-breed software model. If a single platform can provide reliable, compliant, and integrated services, it creates a powerful incentive for lenders to consolidate their tech stack. This could lead to a market shift where platform reliability and integration capabilities become more important than individual feature sets.

Furthermore, the introduction of programmable disbursements via Beyond Credit suggests a future where the line between lending and payments becomes increasingly blurred. Lenders are evolving into transaction enablers, gaining more control over the point of sale and providing a more seamless experience for the end user.

Official Responses and Industry Outlook

The industry reception to these developments has focused heavily on the potential for reduced operational overhead. Analysts suggest that by minimizing the need for third-party middleware, lenders can significantly lower their "cost-to-serve" per account—a key metric for profitability in a high-interest-rate environment.

Lenders have long clamored for a single point of accountability. As Roberts pointed out, the goal is to provide a "single team to call" for everything from payment failures to AI model integration. This shift towards accountability and centralization is likely to resonate with Chief Technology Officers (CTOs) and Chief Risk Officers (CROs) who are currently tasked with managing fragmented legacy infrastructures.

Future Trajectory

As LoanPro continues to integrate AI and payment technologies, the next phase of its growth will likely involve deeper data analytics. With the full lifecycle of a loan—from origination and disbursement to payments and collections—now residing within the LoanPro platform, the company is uniquely positioned to offer predictive insights into borrower behavior.

For the broader market, this launch serves as a bellwether for the next generation of financial software. The era of stitching together disparate tools is being challenged by the era of integrated, platform-based lending. As lenders continue to seek ways to maximize efficiency while navigating an increasingly complex regulatory landscape, solutions that prioritize governance, consolidation, and real-time utility will likely define the future of the credit industry. LoanPro’s move to bring AI and payments under one roof is not just a product update; it is a strategic repositioning for a more integrated and automated financial future.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

Tokenized Deposits Cross the Threshold from Concept to Live Banking Reality As Digital Assets Transform Global Finance

by admin September 24, 2026
written by admin

Tokenized deposits have officially crossed the boundary from theoretical exploration and controlled sandbox experiments into the realm of live, production-grade financial infrastructure. Across major global financial centers, traditional banking institutions are grappling with the practical realities of deploying blockchain-based bank money for everyday consumer and commercial use. This technological leap marks a profound shift in how the foundational liabilities of the banking system are represented, transferred, and settled.

Recent milestones achieved in both the United Kingdom and the United States highlight the rapid acceleration of digital asset adoption. Yet, as commercial banks prove that tokenized deposits can successfully traverse institutional boundaries, the industry faces a complex array of structural, operational, and technical hurdles. Moving digital money is no longer the primary obstacle; rather, ensuring systemic interoperability, defining programmability governance, managing round-the-clock liquidity, and modernizing legacy back-office accounting have emerged as the defining challenges of the next era of banking.

Chronology of Recent Milestones in Tokenized Finance

The transition of tokenized deposits from experimental ledgers to live operational environments has accelerated significantly over the past several years, culminating in major industry breakthroughs in late 2026.

In the United Kingdom, momentum built steadily following regulatory clearances and collaborative industry initiatives spearheaded by groups like UK Finance. This trajectory reached a critical juncture when seven major U.K. banking institutions participated in live customer transactions using tokenized sterling deposits. Executed on the shared Great British Tokenised Deposit (GBTD) platform—developed by enterprise blockchain firm Quant—these transactions included complex high-value processes such as residential remortgage completions alongside standard consumer marketplace purchases.

Concurrently, across the Atlantic, the United States witnessed a parallel evolution in digital settlement infrastructure. The Clearing House, a banking association and payments company owned by the largest commercial banks, formally selected Quant to power its highly anticipated On-Chain Money Initiative. Designed to create a unified network allowing financial institutions to clear and settle tokenized deposits while seamlessly bridging them to legacy fiat payment systems, this initiative aims to onboard participating institutions by the first half of 2027.

These synchronized developments on both sides of the Atlantic underscore a global race to modernize wholesale and retail banking through distributed ledger technology (DLT). Financial institutions are no longer asking whether tokenization is viable, but rather how to scale it safely without fracturing the liquidity and stability of the broader financial ecosystem.

The Imperative of Bank Token Interchangeability

For tokenized deposits to achieve widespread adoption, they must overcome the fundamental barrier of fragmentation. A digital dollar or pound issued by one commercial institution cannot remain a proprietary siloed product; it must possess the same universal utility and fungibility as physical currency or traditional bank reserves.

In a traditional banking relationship, a corporate treasurer or retail consumer does not question whether funds in Checking Institution A can be easily and frictionally transferred to an account holder at Institution B. This seamless interoperability is maintained through decades-old clearing networks, correspondent banking relationships, and central bank settlement mechanisms. Tokenized deposits must replicate this exact quality on-chain.

The recent U.K. live transactions demonstrated that participating institutions could successfully transfer tokenized deposits across disparate institutional boundaries. Similarly, The Clearing House’s U.S. network is being engineered specifically to enable commercial bank token money to move fluidly among participants while the corresponding fiat funds clear in the background.

For corporate treasurers managing complex liquidity portfolios across multiple banking partners, tokenization offers little tangible value if the resulting digital balances remain trapped within individual institutional walls. The ultimate test of interoperability will be measured by whether end-users can treat tokenized deposits as universally accepted bank money rather than specialized, walled-garden digital tokens.

Identifying the Unique Value Proposition Over Legacy Rails

Banks already possess a sophisticated suite of established payment rails, including automated clearing house (ACH) transfers, high-value wire networks, and burgeoning real-time payment (RTP) systems. Therefore, introducing tokenized deposits requires a compelling economic and operational justification that goes beyond simply offering another way to move money from point A to point B.

Market research illustrates the crowded landscape of modern banking choices. According to PYMNTS Intelligence data regarding real-time payment adoption, approximately 35% of financial institutions are actively investing in centralized third-party payment hubs, while 32% are integrating rail-specific tools directly into their legacy core systems. As payment options multiply, banks risk overwhelming corporate and retail clients with redundant choices unless each rail serves a distinct, high-value use case.

Tokenized deposits find their strongest justification in capabilities that legacy rails struggle to execute efficiently, most notably conditional transactions and atomic settlement. By collapsing the time gap between the movement of an underlying asset—such as real estate, securities, or physical goods—and the transfer of funds, tokenization eliminates counterparty risk. When payment and settlement occur simultaneously, the traditional friction of escrow accounts and delayed verification processes dissolves, providing a measurable efficiency gain that justifies the capital expenditure of implementation.

Programmability, Governance, and Bank Policy

One of the most transformative attributes of tokenized deposits is programmability, the ability to embed automated conditions directly into the digital currency via smart contracts. However, the execution of automated code introduces profound operational and legal questions that extend far beyond technical execution.

The recent U.K. trials provided clear demonstrations of programmability in action. In the remortgage transactions, funds remained securely locked within the customer accounts until every legal and administrative completion condition was officially verified and satisfied. In the consumer marketplace transaction, the buyer’s funds were similarly escrowed on-chain and released autonomously only upon the successful verification of the goods exchange.

While automation promises speed and security, it also shifts subjective policy decisions into rigid algorithmic code. Financial institutions must answer critical governance questions: Who precisely defines the release conditions? What cryptographic or external data proves those conditions have been met? Who holds the administrative authority to halt a runaway execution instruction, and how are disputes between transacting parties resolved? Consequently, banks implementing tokenized deposits must build robust legal and compliance rulebooks to govern programmatic payments alongside the software code that executes them.

Continuous Settlement Pressures and Liquidity Management

The transition to tokenized deposits operating on distributed ledgers fundamentally alters traditional treasury and liquidity management frameworks. Because blockchain networks operate continuously, money that can move around the clock must be backed by funding and liquidity management that operates around the clock.

Industry data highlights the operational strain associated with continuous operations. Research from PYMNTS Intelligence emphasizes that liquidity requirements, deep treasury integration, around-the-clock staffing, and perpetual operational readiness represent primary implementation hurdles for financial institutions adopting real-time payment systems. Tokenized deposits threaten to magnify these demands exponentially, extending 24/7 liquidity requirements into large corporate finance, cross-border commerce, and complex asset-backed markets.

When discussing the architectural design of The Clearing House’s upcoming network, CEO David Watson noted that the system is intentionally engineered to allow corporate treasurers to transfer tokenized deposits between banks with a single instruction, triggering simultaneous underlying fiat settlement. For commercial banks, providing this level of unprecedented operational convenience demands that sufficient liquidity buffers remain continuously available, even outside conventional banking hours, weekends, and global holidays.

Overcoming the Bottleneck of Legacy Accounting and ERP Integration

A common misconception in financial technology modernization is that faster payment settlement automatically translates to accelerated business accounting. In reality, moving a tokenized deposit from one bank to another in a matter of seconds does little good if the receiving organization’s internal infrastructure cannot process the data with equal velocity.

Data from financial sector surveys underscores this operational bottleneck. Over 53% of financial institutions identify manual-intensive internal processes as a primary obstacle to modernization, while 52% point directly to legacy technology constraints. For corporate customers, rapid on-chain settlement loses its economic value if treasury personnel are still forced to manually identify transactions, reconcile matching invoices, or wait days for data packets to filter through legacy enterprise resource planning (ERP) software.

As tokenized deposits move closer to mainstream commercial deployment, the ultimate success of the technology will rely heavily on end-to-end integration. Financial institutions and software vendors must ensure that the speed of distributed ledgers is matched by automated reconciliation, seamless general ledger updates, and real-time compliance reporting. Only then can the full economic promise of digital bank money be fully realized across the global financial landscape.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

TechCrunch Disrupt 2026 Launches BOGO Ticket Promotion as Countdown to San Francisco Event Begins

by admin September 24, 2026
written by admin

The technology industry’s premier innovation showcase, TechCrunch Disrupt 2026, is entering its final operational phase, with organizers announcing a strategic "Buy One, Get One" (BOGO) ticket initiative designed to bolster collaborative attendance. As the event approaches its October 13 opening at the Moscone West convention center in San Francisco, the organizers are offering a 50% discount on the second pass for any ticket type purchased. This promotional window remains active until the doors open at 8:00 a.m. PT on October 13, at which point standard pricing will resume.

The Strategic Value of Collaborative Attendance

The philosophy behind the BOGO promotion is rooted in the logistical reality of large-scale industry conferences. TechCrunch Disrupt, which runs from October 13 through October 15, serves as a hub for more than 10,000 founders, investors, engineers, and tech executives. Because the event features over 200 tactical sessions and spans six distinct industry stages, the organizers argue that the complexity of the agenda makes it difficult for a single individual to extract maximum value from the experience.

By incentivizing the attendance of co-founders, business partners, or colleagues, the event aims to facilitate a "divide and conquer" approach to networking and knowledge acquisition. When two members of an organization attend, they can simultaneously monitor different tracks—such as Artificial Intelligence, SaaS, Fintech, or hardware innovation—and synthesize their findings to create a more comprehensive strategic roadmap. This collaborative attendance model is intended to turn passive observation into actionable business intelligence, potentially accelerating product development cycles or fundraising efforts.

Event Overview and Industry Impact

Since its inception, TechCrunch Disrupt has positioned itself as a barometer for the broader technology ecosystem. The 2026 iteration is expected to host more than 300 early-stage and growth-stage startups, providing a centralized venue for deal-making and talent acquisition. The event’s structure is built on a foundation of "AI-powered matchmaking," a technology utilized to connect founders with investors based on specific industry verticals, funding stages, and technical requirements.

Bring your co-founder, partner, or colleague and get 50% off a second TechCrunch Disrupt 2026 pass

The significance of such gatherings has grown in the current economic climate, where capital efficiency and rapid iteration are prioritized. By gathering 250+ speakers—ranging from venture capitalists managing multibillion-dollar portfolios to technical leads from hyperscale enterprises—the event offers a unique cross-section of the industry’s current priorities. Historically, these sessions cover a spectrum of topics including the ethical implications of autonomous systems, the evolution of cloud infrastructure, and the changing landscape of global cybersecurity regulations.

Chronology and Operational Deadlines

The lead-up to Disrupt 2026 follows a structured timeline designed to manage attendee volume and logistical capacity.

  • Early September 2026: Initial registration phases for exhibitors and VIP attendees reach capacity, marking the shift toward general admission focus.
  • September 24, 2026: Launch of the BOGO 50% promotional offer for all ticket tiers, including Investor, Founder, Attendee, Non-profit, Student, and Expo+ passes.
  • September 25, 2026: A critical pricing deadline for individual ticket holders, with rates set to increase at 11:59 p.m. PT.
  • October 13, 2026 (8:00 a.m. PT): Official event kickoff at Moscone West. This serves as the absolute deadline for the BOGO offer; post-opening, standard pricing for remaining inventory applies.

Analysis of Ticket Tiers and Economic Implications

The promotional structure differentiates between the specific needs of various attendee cohorts, reflecting the diverse economic goals of participants:

Investors: This cohort is incentivized to bring associates or partners to help verify due diligence. By having two representatives on the floor, firms can increase their capacity for vetting startups, comparing signals in real-time, and identifying investment opportunities before they reach wider market awareness. The BOGO deal offers a potential savings of up to $450 per pair.

Founders: For early-stage companies, the cost of attendance is often weighed against potential funding outcomes. By reducing the cost for a co-founder or a key operational lead, the event allows startups to maintain a presence at booth exhibitions while simultaneously attending high-level investor panels. The potential $425 savings provides a meaningful reduction in the overhead required to participate in the event’s high-visibility startup showcase.

Bring your co-founder, partner, or colleague and get 50% off a second TechCrunch Disrupt 2026 pass

Operators and General Attendees: This category includes product managers, software engineers, and growth specialists. For these professionals, the value proposition lies in benchmarking their own company’s performance against industry peers. Accessing six industry stages allows teams to optimize their go-to-market strategies by learning from the successes and failures of others. Savings here reach up to $412 per pair.

Students and Non-profits: In a deliberate effort to lower the barrier to entry for the next generation of builders and mission-driven organizations, the BOGO initiative offers significant reductions for students ($175 savings) and non-profit representatives ($237 savings). These groups are encouraged to utilize the networking opportunities to secure mentorship or potential partnerships that might otherwise be inaccessible.

The Role of Networking and Infrastructure

The success of TechCrunch Disrupt is largely attributed to its role as a "force multiplier" for professional networks. Data from previous years suggests that the vast majority of participants identify "connection building" as their primary objective. The introduction of AI-driven matchmaking in recent years has shifted the event away from random encounters toward highly curated, intent-based meetings.

For attendees, the decision to bring a partner is not merely a financial calculation; it is a tactical choice to increase the "surface area" of the event. In a three-day window, a solitary attendee can typically participate in a limited number of high-stakes conversations. Two attendees, however, can effectively double the number of interactions, ranging from spontaneous networking at the coffee stations to formal, scheduled "Braindate" sessions that are a hallmark of the conference’s structure.

Navigating the Future of the Tech Landscape

As the industry prepares for the 2026 gathering, the prevailing sentiment among analysts is that the event will focus heavily on the maturation of generative AI applications and the transition from "hyped" technology to "utility" technology. The sessions are curated to address the "how" of business—how to scale under economic pressure, how to manage talent in a decentralized world, and how to maintain competitive advantages when technology commoditization occurs at an unprecedented rate.

Bring your co-founder, partner, or colleague and get 50% off a second TechCrunch Disrupt 2026 pass

The organizers emphasize that the event’s structure—from the "Builders Stage" to the "Investor Lounge"—is intended to mimic the actual lifecycle of a company. Whether an attendee is in the ideation phase, seeking Series A funding, or preparing for an IPO, the content is segmented to provide immediate, actionable relevance.

Final Call for Participation

As the October 13 deadline approaches, prospective attendees are encouraged to review the full agenda to ensure that the ticket type selected aligns with their specific professional objectives. The BOGO promotion is, by design, a limited-time opportunity to minimize the capital required to access a high-density network of peers and decision-makers.

For those who have not yet secured their place at Moscone West, the upcoming days represent the final opportunity to participate under the current promotional terms. Following the commencement of the event, the focus will shift entirely from acquisition to execution, as the global technology community converges in San Francisco to define the trajectory of the coming year.

(Disclosure: This article contains information regarding ticket sales and potential affiliate monetization through TechCrunch’s promotional links. Such arrangements do not influence the editorial content or the objective reporting of event details.)

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

Crowdcube Positions Secondary Share Trading as a Core Growth Driver with £750 Million Pipeline Backed by PISCES

by admin September 24, 2026
written by admin

Crowdcube, one of Europe’s leading equity crowdfunding and online investment platforms, has announced that secondary share transactions have rapidly evolved into a cornerstone of its commercial strategy. According to recent disclosures from the firm, an impressive £543 million in transactions facilitated through the United Kingdom’s Private Intermittent Securities and Capital Exchange System (PISCES) is currently winding its way through the platform’s pipeline. When calculated alongside other secondary listings, Crowdcube projects the potential for up to 29 distinct listings carrying a cumulative estimated value of £750 million over the course of the next two quarters.

This major strategic pivot highlights a broader maturation within the alternative finance sector. Traditionally, retail-focused equity crowdfunding platforms built their business models around primary issuances—connecting early-stage startups and high-growth ventures with retail and institutional risk capital. The fundamental objective was to democratize access to private asset classes that were historically reserved for venture capitalists and institutional heavyweights. Over the past decade, however, leading platforms have increasingly diversified their operations, moving beyond primary fundraising rounds to address a critical friction point in the private market lifecycle: liquidity.

The Evolution of Private Markets and the Rise of Secondaries

For years, the private market ecosystem faced a distinct structural bottleneck. As private companies chose to remain private for significantly longer periods—often delaying initial public offerings (IPOs) due to regulatory burdens, ample private liquidity, and shifting market conditions—early investors, founders, and long-serving employees found themselves locked into illiquid positions. While these firms achieved multi-billion-dollar valuations, stakeholders had few viable avenues to realize financial returns on their equity prior to a formal trade sale or public market debut.

Recognizing this market inefficiency, innovative platforms began laying the groundwork for secondary marketplaces. These secondary offerings enable the buying and selling of shares in privately held companies that have already secured substantial venture backing but have not yet gone public. By facilitating these transactions, platforms can bridge the gap between eager buyers seeking exposure to mature private firms and existing shareholders looking to monetize their stakes.

Crowdcube’s proactive stance in this arena began years before the introduction of formal governmental frameworks dedicated to private secondary trading. This early-mover advantage allowed the company to construct the underlying technological infrastructure, compliance protocols, and investor networks necessary to handle complex secondary transactions seamlessly. Consequently, when regulatory shifts created new pathways for private market liquidity, Crowdcube was uniquely positioned to capture significant market share.

The Role of PISCES and Regulatory Innovation in the United Kingdom

At the heart of the current surge in secondary trading is PISCES, an acronym for the Private Intermittent Securities and Capital Exchange System. PISCES represents a visionary legislative and regulatory initiative spearheaded by the UK government and financial authorities, designed to enhance the competitiveness and flexibility of both public and private capital markets across the country.

The primary objective of PISCES is to allow private companies to periodically trade their shares on a regulated platform without undergoing the rigorous, expensive, and time-consuming process of a full IPO. Under the PISCES framework, a private firm can remain private while still offering its shareholders and institutional investors structured windows of liquidity. These periodic trading events are hosted on authorized, regulated platforms, ensuring transparency, investor protection, and robust market integrity.

In a move that solidified its standing as a market leader, Crowdcube established a strategic partnership with the London Stock Exchange (LSE) to support this innovative service. Furthermore, Crowdcube operates as a Registered Auction Agent (RAA) on the London Stock Exchange Private Securities Market (PSM). The operational success of this ecosystem is already evident: the nascent PISCES and PSM framework has successfully facilitated four major transactions to date, with Crowdcube directly involved in three of those landmark deals executed on the LSE Private Securities Market.

Strategic Insights and Leadership Perspectives

The sheer velocity at which secondaries have integrated into Crowdcube’s overarching business model has surprised even industry veterans. The company notes that its current pipeline of secondary offerings features some of the most dynamic, fastest-growing technology and consumer brands across the United Kingdom and the broader European Union.

Matt Cooper, Co-Chief Executive Officer of Crowdcube, emphasized that the visibility and near-term nature of this pipeline distinguish it from traditional, highly unpredictable primary fundraising rounds.

"What is different about this pipeline is that it is near-term, and we have good visibility on it," Cooper stated in a recent company blog post. "We built the infrastructure for this before PISCES existed, and that is why these transactions are coming to us."

Cooper’s remarks underscore the importance of operational readiness in the fintech sector. By anticipating the regulatory shift toward private market liquidity and investing heavily in proprietary trading infrastructure years in advance, Crowdcube avoided the lag time that typically plagues legacy financial institutions when new asset classes emerge.

Global Parallels and Market Transformation

Crowdcube’s strategic pivot mirrors a broader macroeconomic trend observed globally, most notably in the United States. Over the past several years, multiple prominent US-based private market platforms have expanded their operational scopes well beyond primary issuances. By establishing robust secondary marketplaces, these platforms have transformed from niche startup funding portals into comprehensive private equity ecosystems.

For Crowdcube, this transition is fundamentally reshaping the company’s financial profile and commercial trajectory. Executive leadership notes that secondary transactions are not merely an auxiliary revenue stream; rather, they are actively driving overall corporate growth and geographic expansion. Industry analysts suggest that if current projections hold, secondary offerings could soon eclipse primary fundraising to become the single largest segment of Crowdcube’s business, fostering a more resilient, diversified, and sustainable corporate model.

While the vast majority of transactions executed under the PISCES framework thus far have involved domestic UK enterprises, Crowdcube reports a notable uptick in inbound interest from continental European companies. These firms are increasingly looking toward the UK’s regulatory framework and Crowdcube’s digital infrastructure to orchestrate their own upcoming liquidity events, signaling the cross-border appeal and scalability of the model.

Broader Economic Implications and Future Outlook

The rapid scaling of private secondary markets has profound implications for the wider financial ecosystem. For institutional investors, family offices, and high-net-worth individuals, platforms like Crowdcube offer unprecedented access to late-stage private companies that were previously walled off behind institutional syndicates. This democratization of private equity helps distribute wealth-generation opportunities more broadly across the investor base.

Simultaneously, for late-stage private companies, the availability of structured liquidity events via PISCES relieves the immense pressure to pursue premature public listings. Companies can focus on long-term operational execution and strategic growth without alienating early employees and angel investors who require periodic cash realization. By offering a controlled, periodic trading environment, PISCES bridges the historical chasm between private agility and public market liquidity.

As Crowdcube works to convert its £750 million pipeline over the upcoming quarters, the platform’s performance will likely serve as a bellwether for the broader viability of intermittent private trading systems. With strong institutional backing, regulatory support through the London Stock Exchange partnership, and a rapidly expanding European footprint, Crowdcube is well-positioned to lead the next evolution of private market finance.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
NFT & Digital Assets

NFT Project Passport: Galactic Geckos

by admin September 24, 2026
written by admin

The digital asset landscape is littered with the remnants of short-lived hype cycles, failed roadmaps, and abandoned community initiatives. Yet, within the fast-moving and volatile Solana ecosystem, a select few foundational projects have managed to weather multiple market corrections, redefining what it means to be a long-term decentralized brand. Among these enduring pioneers is Galactic Geckos, officially recognized as Galactic Gecko Space Garage (GGSG). Launched in September 2021 during the nascent stages of Solana’s NFT boom, the project has evolved from a standard profile picture (PFP) collection into a comprehensive social adventure club, a lore-driven intellectual property (IP) brand, and a resilient decentralized autonomous organization (DAO) ecosystem.

This comprehensive project profile examines the historical trajectory, structural shifts, and recent developments surrounding Galactic Geckos. By evaluating its deflationary mechanics, community-led evolution, and expansion into gaming and cross-chain activations, this report provides a fact-based analysis of how GGSG has sustained its relevance and value proposition over nearly half a decade of Web3 evolution.

Project Snapshot and Market Fundamentals

At its core, Galactic Geckos is structured around a total fixed supply of 10,000 hand-drawn digital assets depicting warrior-class, space-racing reptiles. Minted originally on September 22, 2021, at an initial price of 2 SOL, the collection has witnessed significant market fluctuations, mirroring the broader macroeconomic cycles of the cryptocurrency industry.

As of June 2026, the collection maintains a floor price of approximately 6.26 SOL (roughly $455), backed by a holder base of approximately 2,983 unique wallets as tracked by analytics platforms such as HowRare. The historical performance of the asset highlights substantial value retention, reaching an all-time high floor of 65 SOL in April 2023, with CoinGecko data recording peak valuations of approximately $4,400 per unit in December 2023.

NFT Project Passport: Galactic Geckos

Crucially, the circulating supply of liquid Galactic Geckos is heavily constrained by structural design choices. Out of the 10,000 total supply, 902 assets have been permanently immortalized through soulbound staking mechanisms, while 7,111 tokens remain locked in long-term staking contracts—the majority of which have been committed for periods of 12 months or longer. This leaves an effectively thin float of approximately 2,000 actively tradeable assets on secondary marketplaces including Magic Eden, Tensor, Artifacte, and Orbis, creating an underlying supply-and-demand dynamic that protects the collection from sudden liquidity shocks.

Origins, Artistic Vision, and the 2022 Leadership Transition

The conceptual foundation of Galactic Geckos was established during a period when the Solana network was rapidly gaining traction as a high-speed, low-cost alternative to Ethereum for generative art and collectibles. While the early Solana landscape was heavily dominated by primate-themed PFP projects, GGSG introduced a distinct sci-fi narrative centered on intergalactic conflict resolved through high-stakes spaceship racing rather than traditional warfare.

The artistic integrity of the collection was spearheaded by acclaimed artist Gossip Goblin, whose professional portfolio includes contributions to major fantasy card games such as Magic: The Gathering. Gossip Goblin manually drew every individual trait within the collection, resulting in 162 unique visual components, each accompanied by detailed narrative lore. Furthermore, the collection was divided into four distinct factions—Alura, Targari, Martu, and Barada—which provided holders with an immediate sense of tribal identity and fueled community engagement beyond simple speculative trading.

Despite its strong conceptual launch, the project encountered severe operational friction during its first few months. A misalignment of financial and operational incentives between the original founding team and the broader holder community led to mounting dissatisfaction and protracted negotiations. Recognizing the existential threat posed by this friction, a decisive restructuring occurred in February 2022. GenuineArticles, alongside a dedicated collective of community members, successfully bought out the original founders, transitioning the project into a community-governed and led entity.

This leadership overhaul fundamentally altered the trajectory of GGSG. The newly established management team discarded top-down corporate directives in favor of a hybrid DAO executive model. This framework combined a lean, agile operational core with a flat organizational structure, enabling rapid execution while maintaining deep alignment with community stakeholders. Through this transition, the overarching mandate of the DAO became strictly focused on routing all ecosystem value back to the original Gecko holders, avoiding the recurring external fundraising rounds that often burden Web3 projects.

NFT Project Passport: Galactic Geckos

Ecosystem Expansion: From Staking Innovations to the Galactic Overdrive TCG

In the years following the 2022 buyout, Galactic Geckos systematically expanded its utility footprint without resorting to inflationary token models or aggressive public-facing marketing campaigns. Instead, the project adopted a "build quietly and compound capability" philosophy, resulting in a diverse suite of proprietary tools and ecosystem extensions.

Among its most notable structural innovations was the pioneering of the "Hero’s Journey" and "immortalization" staking mechanics. By committing assets to long-term lockups or soulbound permanent staking, holders effectively removed significant portions of the supply from circulation while unlocking tiered reward streams. According to project analytics and historical CoinGecko charts, cumulative rewards distributed to staked Gecko holders have historically exceeded $23,000 at peak valuations, augmented by anticipated token generation events (TGEs) from ecosystem partners such as LucidAI and CUBE ($ISO).

Simultaneously, the project established GreenListed, a community-led investment and incubation affiliate. GreenListed has functioned as an early-stage venture vehicle for Solana and broader Web3 builders, famously leading the seed funding round for Matrica with a seven-figure investment and a secured board seat. Matrica has since matured into a leading cross-chain token-gating protocol utilized across multiple blockchain ecosystems, validating the strategic foresight of the GGSG investment arm.

In January 2026, the ecosystem achieved a significant milestone with the alpha release of Galactic Overdrive, a trading-card game developed by Space Squid Studios in close partnership with GGSG. Designed after four years of deliberate development, the game prioritized user experience and engaging gameplay mechanics over immediate financialization. Initial alpha testing metrics on iOS, Android, and web demonstrated high user retention, with over 90 percent of participants returning for multiple sessions and more than 20 percent engaging on a daily basis without financial incentives. A broader public beta rollout is scheduled for the third quarter of 2026.

Concurrently, the project has enhanced its digital infrastructure by launching Collector Profiles and comprehensive holder tools. These applications provide advanced rarity research, airdrop tracking, and gamified badges that surface and reward active participation within the ecosystem. Furthermore, specialized internal community groups—focusing on domains ranging from artificial intelligence expertise and DeFi optimization to X (formerly Twitter) growth and personal wellness—have successfully equipped members with professional skills, with the Gecko Growth Group alone assisting over 80 members in monetizing their social media presence.

NFT Project Passport: Galactic Geckos

Broader Industry Impact and Strategic Implications

The longevity and trajectory of Galactic Geckos offer several important insights into the economic sustainability of NFT-based intellectual property brands. In an industry sector where public momentum is frequently manufactured through high-frequency marketing campaigns and expansive, often unfulfilled roadmaps, GGSG has maintained a deliberately understated public profile.

By prioritizing organic community alignment, deflationary supply mechanisms, and tangible utility over speculative hype, the project has demonstrated that legacy NFT collections can successfully transition into diversified decentralized enterprises. Cross-community initiatives, such as the January 2026 activation connecting Galactic Geckos to Yuga Labs’ Otherside metaverse via LucidAI allocations, further underscore the brand’s ability to transcend its native blockchain environment and integrate into broader digital culture.

Looking toward the remainder of 2026 and beyond, the project’s strategic roadmap remains deliberately flexible, eschewing rigid timelines in favor of adaptive execution. Confirmed initiatives include the forthcoming expansion of physical merchandise, tokenized physical goods, and real-world asset (RWA) partnerships, alongside the anticipated scale-up of the Galactic Overdrive TCG.

As the digital asset market matures, projects like Galactic Geckos serve as empirical testaments to the power of resilient community ownership. By weathering governance crises, shifting market narratives, and severe macroeconomic contractions without relying on external venture capital extraction, GGSG has established a durable blueprint for community-driven intellectual property development in the Web3 era.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
NFT & Digital Assets

The Rise of Argonauts and the Return to Artist-Centric NFT Collecting

by admin September 24, 2026
written by admin

Today, the digital art landscape witnessed a significant shift in market behavior as Argonauts, the latest 10,000-piece collection by the crypto-native artist a.c.k. (@lphaCentauriKid), minted out in a matter of minutes. Priced at approximately 0.12 ETH—roughly $300 at the time of the sale—the collection’s rapid depletion of supply was not driven by the typical speculative frenzy that characterized the 2021 bull market, but rather by a concentrated effort from a community of artists, long-term collectors, and patrons of crypto-native aesthetics. While the secondary market for NFTs has faced extreme volatility over the past twenty-four months, the success of Argonauts serves as a data point indicating a potential transition toward a more sustainable, art-first ecosystem.

The Mechanics of the Mint and Market Context

The minting process for Argonauts began with a clear, artist-led value proposition. Unlike the "roadmap-heavy" project models that dominated the NFT space in recent years—where utility, tokenomics, and metaverse integration were used to justify price floors—a.c.k. opted for a minimalist approach. By positioning the collection as a direct extension of his established body of work, the artist bypassed the need to manufacture artificial demand.

The chronology of the release was swift. Within minutes of the contract opening, the 10,000 pieces were fully distributed. This velocity of sale, particularly in a market environment currently wary of high-supply collections, suggests that the collector base for crypto-art has become highly sophisticated. Data from the mint suggests that the primary purchasers were not anonymous "flippers" seeking immediate arbitrage opportunities, but rather wallets with histories of holding blue-chip digital art and supporting mid-career digital creators.

Historical Context: From Speculation to Provenance

To understand the significance of the Argonauts mint, one must examine the evolution of the NFT sector. During the height of the 2021 market boom, the narrative surrounding NFTs became increasingly commoditized. Projects were frequently launched as startup entities, promising future perks, "staking" rewards, and elaborate, often undeliverable, utility. This shift alienated many traditional art collectors, who viewed these projects as financial instruments rather than creative assets.

The foundational promise of NFTs—the ability to establish digital provenance, enforce scarcity, and facilitate a direct, transparent relationship between the artist and the buyer—was often obscured by the noise of speculative trading. The Argonauts launch acts as a correction to this trend. By focusing on the visual language that a.c.k. has cultivated over several years of production, the collection returns to the fundamental utility of the medium: the act of owning and supporting the work of a specific artist.

The Role of Accessibility in Digital Art

A persistent challenge in the digital art market has been the issue of accessibility. As artists gain prestige, their primary works often reach price points that exclude all but the most affluent collectors. Historically, this has created a "whale-dominated" market, where only a small percentage of participants can afford to engage with an artist’s ecosystem.

The 10,000-piece format utilized by Argonauts provides a strategic solution to this barrier. By offering a larger supply at an accessible entry price, a.c.k. has effectively democratized participation in his body of work. This strategy allows a wider demographic—including fellow artists, curators, and emerging collectors—to secure a stake in the artist’s output. This shift is vital for the long-term health of the crypto-art market; it builds a broad, inclusive foundation that is more resilient to the departures of high-net-worth speculators.

Demographic Analysis: Artists Collecting Artists

One of the most notable aspects of the Argonauts collection is the demographic profile of the holders. Industry analysts have noted a trend where established digital artists are increasingly becoming the primary collectors of their peers’ work. This phenomenon creates a "virtuous circle" of value, where the credibility of the ecosystem is bolstered by the participation of those who understand the technical and aesthetic nuances of the medium.

When an artist with a significant following releases a collection that is immediately absorbed by other practitioners in the field, it signals a consensus on the work’s artistic merit. This form of "social proof" is far more durable than the marketing-led hype cycles that plagued the NFT space in the past. It suggests that the value of Argonauts is anchored in cultural capital rather than speculative volatility.

Implications for Future Market Cycles

The successful sellout of Argonauts provides a blueprint for the next phase of the digital asset market. If the primary driver of future success is, once again, the quality of the art and the strength of the artist’s reputation, then the industry is likely entering a period of "professionalization."

In this emerging era, we can expect a decline in the dominance of collections that rely on "roadmap" promises. Instead, collectors are likely to prioritize:

  1. Provenance: The verifiable history of the artist’s career and their previous output.
  2. Aesthetic Cohesion: A clear, identifiable visual language that exists independently of the blockchain.
  3. Community Composition: The presence of genuine peers and long-term supporters within the holder base.

This evolution mirrors traditional fine art markets, where reputation and provenance are the primary determinants of value. By aligning itself with these historical precedents, the digital art space may finally be moving toward a model of permanence.

The Sustainability of the Artist-Collector Relationship

The relationship between the artist and the collector is the bedrock of any successful creative economy. For years, the NFT space treated this relationship as a transactional, short-term arrangement. The Argonauts launch, however, highlights the importance of fostering long-term engagement. When collectors believe in the trajectory of an artist’s career, they are more likely to hold their assets through market fluctuations, providing the stability that digital creators need to produce their best work.

Furthermore, the lack of reliance on secondary-market volatility suggests that both a.c.k. and his collectors are focused on the long-term appreciation of the art. This is a critical departure from the "mint-and-dump" culture that characterized the early 2020s, where projects often collapsed as soon as the initial hype dissipated.

Broader Impact on Digital Infrastructure

The broader implications of this shift extend beyond the art market. It reinforces the utility of blockchain technology as a tool for artistic distribution rather than just financial speculation. As the industry moves toward more stable, interest-based communities, the technological infrastructure supporting these assets—such as marketplaces, smart contract standards, and display platforms—will likely evolve to cater to the needs of collectors who prioritize quality over quick returns.

The success of the Argonauts mint proves that the demand for crypto-native art has not evaporated; it has simply matured. Collectors are no longer satisfied with empty promises of utility. They are looking for substantive, artist-led projects that offer a clear connection to the creator’s vision.

Conclusion: A Return to Fundamentals

The Argonauts collection by a.c.k. stands as a testament to the endurance of artistic value in the digital age. By ignoring the pressures of the speculative market and focusing on the core relationship between artist and collector, the project has successfully navigated a challenging economic environment.

This development is a signal to the entire NFT ecosystem: the era of the speculative "road-mapped" project is waning, and the era of the artist-centric collection is emerging. If the market continues to prioritize genuine appreciation, provenance, and the sustained support of creators, the digital art world will emerge from its current period of volatility not only intact but more robust than it has ever been. The success of this mint is not just a triumph for a.c.k.; it is a proof-of-concept for a healthier, more sustainable future for digital ownership.

As the dust settles on the Argonauts mint, the focus remains on the art itself—a simple, revolutionary concept that, after years of complexity and confusion, finally feels like it is coming home. Through this collection, the community has shown that it is ready to move beyond the experimental phase of NFTs and into a more mature, refined chapter of digital art history.

September 24, 2026 0 comment
0 FacebookTwitterPinterestEmail
Newer Posts
Older Posts

Recent Posts

  • The Evolution of the Web3 Wallet: From Private-Key Vault to the Command Center of the Agentic Web
  • Ethereum Foundation Announces Annual Protocol AMA Session Scheduled for September 16
  • Kraken Expands Its Digital Asset Offerings with the Official Listing of Doppler Finance (Xdp)
  • CSD BR and Ripple Collaborate to Integrate XRP Ledger into Brazilian Financial Market Infrastructure
  • Web3 Venture Funding Surges to Record $22 Billion in Third Quarter 2025 Driven by Institutional Adoption

Recent Comments

No comments to show.
  • Facebook
  • Twitter

@2021 - All Right Reserved. Designed and Developed by PenciDesign


Back To Top
Dr Crypton
  • Home
  • About Us
  • Contact Us
  • Cookies Policy
  • Disclaimer
  • DMCA
  • Privacy Policy
  • Terms and Conditions

We are using cookies to give you the best experience on our website.

You can find out more about which cookies we are using or switch them off in .

Dr Crypton
Powered by  GDPR Cookie Compliance
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.

Strictly Necessary Cookies

Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.