• Home
  • About Us
  • Contact Us
  • Cookies Policy
  • Disclaimer
  • DMCA
  • Privacy Policy
  • Terms and Conditions
Dr Crypton
Secure Your Future in Crypto
Cryptocurrency News

Coinbase Expands Crypto Reach Through Strategic Partnership With Stablecore to Empower Community and Regional Banks

by admin September 19, 2026
written by admin

The landscape of American banking is undergoing a subtle yet profound transformation as digital assets transition from the fringes of finance into the core architecture of traditional institutions. In a major strategic push to bridge the gap between traditional finance and the decentralized economy, cryptocurrency exchange giant Coinbase has announced a definitive partnership with banking-infrastructure provider Stablecore. This collaboration aims to strip away the technical complexities that have historically prevented smaller financial institutions from offering digital asset services. By leveraging Stablecore’s pre-existing network integrations, the initiative opens a potential gateway for more than 3,000 community banks, regional banks, and credit unions across the United States to seamlessly integrate cryptocurrency trading, secure digital custody, and stablecoin payment rails directly into their existing product suites.

For decades, community financial institutions have found themselves structurally and financially constrained when attempting to innovate alongside multinational banking titans. While major Wall Street institutions and multi-billion-dollar fintech enterprises have spent years building proprietary blockchain frameworks, regional banks have largely been left on the sidelines. The prohibitive costs of compliance, software development, and specialized cybersecurity infrastructure have made the adoption of digital assets a daunting endeavor. The Coinbase and Stablecore collaboration directly addresses this bottleneck by offering a turnkey, white-label solution. Rather than requiring banks to build expensive digital asset frameworks from the ground up or forcing their customers to migrate to external cryptocurrency exchanges, the partnership embeds digital finance squarely within the familiar interfaces that everyday consumers and businesses already use.

Unpacking the Infrastructure: How the Integration Works

At the heart of this partnership is a division of labor designed to maximize efficiency and security. Stablecore operates as an infrastructure bridge, offering white-label software solutions that plug directly into the legacy core banking and digital banking systems utilized by community financial institutions. These legacy systems—often provided by third-party tech vendors that service the vast majority of America’s regional banks—are notoriously difficult to modify. Stablecore’s technology effectively acts as an interpreter, bridging traditional banking software with modern fintech rails.

Behind this user-facing layer sits Coinbase, which provides the heavy lifting of digital asset infrastructure. Through its institutional-grade custody solutions, deep liquidity pools, and compliant trading APIs, Coinbase handles the underlying storage, execution, and regulatory compliance associated with cryptocurrencies and stablecoins.

When a community bank opts to activate the service, its customers do not need to download a separate application, verify their identity with a third-party crypto exchange, or initiate complex wire transfers to fund an external account. Instead, a local bank customer can view a cryptocurrency balance, execute a trade, or settle a cross-border invoice using stablecoins directly inside their primary online banking portal or mobile app. The blockchain ledger operates invisibly in the background, transforming what was once an intimidating alternative asset class into a native banking feature.

Early validation of this model is already taking shape. Coinbase has confirmed that implementation efforts are officially underway with early adopter institutions, notably Amarillo National Bank in Texas. As these pilot programs mature, they are expected to serve as a blueprint for other regional institutions seeking to stem the outflow of customer deposits toward digital-first fintech competitors.

Contextualizing the Footprint: Access Versus Active Adoption

While the headline figure of 3,000-plus accessible financial institutions commands attention, market analysts and industry observers emphasize the crucial distinction between infrastructure reach and actual adoption. The statistic does not imply that thousands of American community banks and credit unions have simultaneously rushed to launch Bitcoin trading desks or stablecoin payment gateways overnight.

Rather, the figure represents the aggregate footprint of Stablecore’s existing network integrations—the total addressable market of institutions that now possess a frictionless, pre-engineered technical pathway to activate Coinbase-powered services whenever they deem it strategically viable. Actual implementation will depend heavily on individual institutional risk appetites, local demographic demand, and board-level consensus.

This distinction highlights the evolving nature of banking technology procurement. For years, regional banks have relied on incremental software updates provided by legacy core processors. By introducing modular, plug-and-play digital asset capabilities through established infrastructure intermediaries, Coinbase is circumventing the traditional, multi-year sales cycles that typically govern banking software adoption. Banks can now toggle these services on incrementally, testing consumer demand without making a terminal commitment to a brand-new operational model.

The Broader Shift: Invisible Crypto and Embedded Finance

The collaboration between Coinbase and Stablecore points to a much wider, quieter trend reshaping the global financial ecosystem: the steady march toward invisible crypto. For years, the narrative surrounding cryptocurrency adoption focused heavily on user acquisition—compelling retail investors and enterprise treasuries to learn entirely new financial interfaces, master self-custody seed phrases, and navigate unfamiliar decentralized applications.

That paradigm is rapidly giving way to embedded finance. Financial technology trends indicate that the most successful technological integrations are those that require the least behavioral change from the end user. By pushing stablecoin settlement, digital asset custody, and yield-bearing cryptocurrency products directly into traditional software environments—such as commercial treasury platforms, mobile banking apps, and enterprise payment systems—the friction of adoption is largely eliminated.

From a regulatory and consumer perspective, this approach normalizes digital assets. When a trusted local credit union offers a stablecoin payment option alongside traditional Automated Clearing House (ACH) transfers and wire services, the psychological barrier of dealing with a volatile or misunderstood technology is substantially lowered. Customers view the service through the lens of the institution providing it, rather than the underlying protocol.

Strategic Implications for the Competitive Banking Landscape

The timing of this partnership is hardly accidental. Regional banks and credit unions across the United States have faced mounting pressure on multiple fronts. Domestically, they compete fiercely with money-center banks that possess massive software development budgets capable of attracting tech-savvy consumers. Simultaneously, they face existential pressure from decentralized finance (DeFi) protocols and centralized cryptocurrency exchanges that continue to capture fee revenue from retail and institutional investors who prefer digital assets over traditional savings vehicles.

By equipping community banks with the technological capability to offer digital assets, Coinbase is executing a classic ecosystem play. For Coinbase, partnering with thousands of localized financial institutions provides a resilient, high-trust distribution channel that bypasses the high customer acquisition costs associated with direct-to-consumer digital marketing. For the community banks, the partnership offers a vital lifeline to retain younger demographics—millennials and Generation Z consumers who increasingly view digital asset access as a baseline requirement for any primary financial relationship.

Furthermore, the integration of stablecoins represents a significant commercial opportunity for regional lenders. Stablecoins—digital tokens pegged to fiat currencies like the U.S. dollar—have exploded in utility, serving as the primary liquidity medium for international trade, cross-border remittances, and round-the-clock commercial settlement. By incorporating stablecoin rails into their treasury services, regional banks can offer corporate clients instantaneous, low-cost settlement capabilities that rival or exceed traditional legacy wire systems, which are often constrained by banking hours and geographic borders.

Looking Ahead: The Road to Mainstream Integration

As the partnership between Coinbase and Stablecore rolls out to its broader network of institutions, industry watchers will be monitoring several key metrics. Chief among them will be the pace at which regional banks transition from infrastructure compatibility to active deployment. Regulatory clarity will also play a decisive role; as federal banking regulators continue to issue guidance regarding how traditional financial institutions may safely engage with digital assets, the legal and compliance pathways for these 3,000-plus institutions will become clearer.

The collaboration signals a maturing phase for the cryptocurrency industry. The era of adversarial positioning—where decentralized digital assets sought to entirely displace traditional banking infrastructure—is steadily being replaced by a pragmatic era of integration and coexistence. By acting as the backend engine for trusted community institutions, Coinbase is positioning digital assets not as a replacement for the traditional financial system, but as the underlying operating system for the next generation of banking.
September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Blockchain Technology

Tokenization Accelerates as India and Singapore Lead the Integration of Blockchain into Traditional Financial Markets

by admin September 19, 2026
written by admin

The global financial landscape is currently undergoing a structural metamorphosis as the concept of tokenization—the process of converting rights to an asset into a digital token on a blockchain—transcends experimental pilot programs to become an operational pillar of traditional finance (TradFi). This shift is driven by the mandate of major financial institutions and central banks to modernize the issuance, settlement, and lifecycle management of financial instruments. By leveraging Distributed Ledger Technology (DLT) and smart contracts, these institutions are moving toward a future where value transfer is not only faster but inherently more transparent and efficient.

Two pivotal developments in Asia last week underscored this momentum: the launch of a live pilot for tokenized corporate bonds in India, and a landmark collaboration between Singapore’s three largest domestic banks to execute live interbank transactions using tokenized deposits. These events signal a maturation of the technology, moving beyond theoretical white papers toward the creation of a robust, regulated, and interoperable digital financial infrastructure.

India’s Demat 2.0: Automating the Corporate Bond Lifecycle

In a significant move to modernize its securities market, the Securities and Exchange Board of India (SEBI) and the Reserve Bank of India (RBI) have inaugurated a pilot project titled "Demat 2.0." This initiative is designed to transition corporate bond management from legacy settlement systems to a high-efficiency DLT framework.

On September 9, 2026, the regulatory bodies confirmed the successful launch of the infrastructure, which allows corporate bonds to be issued and held as digital tokens. The technical architecture relies on a distributed ledger maintained by the nation’s statutory depositories. Unlike traditional bond issuance, where interest payments and redemptions require complex manual reconciliation between multiple intermediaries, Demat 2.0 utilizes smart contracts—self-executing code stored on the ledger—to automate the entire lifecycle of the security.

Chronology and Initial Issuance Data

The scale of this pilot suggests significant institutional appetite. Within the first few days of the rollout, three major entities leveraged the new infrastructure to raise capital:

  • September 7, 2026: REC (a government-owned financier) became the pioneer issuer, raising 5 billion rupees ($52 million) from 18 institutional investors.
  • September 9, 2026: Indian multinational conglomerate L&T Limited successfully issued 5 billion rupees ($52 million) in tokenized bonds to four investors.
  • September 9, 2026: IIFL Finance, a prominent non-banking financial company, raised 250 million rupees ($2.61 million) from a single investor.

In total, 10.25 billion rupees (approximately $108 million) were issued in the inaugural phase. This represents a significant expansion from initial projections made in August, which estimated the pilot would involve less than 5 billion rupees.

The Role of Wholesale CBDC

The defining feature of Demat 2.0 is its integration with the Indian wholesale Central Bank Digital Currency (CBDC), the digital rupee (e₹). Through the Unified Market Interface (UMI) of the RBI, the system achieves "atomic settlement." This allows the securities leg and the payment leg of a transaction to occur simultaneously. In the current T+3 settlement cycle standard, transactions can take up to three days to clear; under the new model, the transfer of ownership and the exchange of funds happen in near-real-time, effectively eliminating settlement risk.

Singapore’s Interbank Tokenized Deposit Breakthrough

While India is concentrating on the modernization of securities, Singapore has reached a different, equally critical milestone: the institutional use of tokenized deposits for interbank liquidity.

DBS, OCBC, and UOB, representing the "big three" of Singaporean domestic banking, collaborated to execute live interbank transactions using tokenized deposits on the Swift blockchain-based ledger. This move represents a shift toward a more programmable banking environment.

The Architecture of the Collaboration

The transactions were conducted through an exchange of payment messages between the banks, with the Swift ledger acting as the central orchestration layer. The obligations were recorded as tokenized deposits on the banks’ respective internal systems. This is significant because it provides a bridge between private bank databases and a global, standardized blockchain network, solving the "silo" problem that has long plagued digital asset adoption.

Rachel Chew, Chief Operating Officer and Co-Head of Digital Assets at DBS, noted that the pilot confirms that tokenized deposits allow for round-the-clock liquidity. "Clients can transact USD and SGD payments any time, any day, including over a weekend," Chew stated. This capability is expected to drastically reduce the idle capital held in accounts for settlement purposes, thereby improving the velocity of money across the Singaporean economy.

Global Context: A Trend Toward Institutional Integration

The actions in India and Singapore are not isolated occurrences but part of a global trend toward the institutionalization of DLT. Various jurisdictions are currently testing similar frameworks to ensure their financial systems remain competitive in a digital-first global market.

  • Switzerland: The Swiss National Bank’s "Project Helvetia III" has been instrumental in testing the issuance of wholesale CBDC on regulated, third-party DLT platforms.
  • Hong Kong: The Hong Kong Monetary Authority (HKMA) continues its "Project Evergreen" initiative, which focuses on the application of tokenization in capital markets and the issuance of digital green bonds.
  • Global Private Sector: Financial titans such as BlackRock and JPMorgan are actively exploring the integration of tokenized U.S. Treasury products. These efforts are aimed at modernizing cash management, as tokenized assets offer the potential for higher liquidity and lower transaction costs compared to traditional money market instruments.

The Broader Implications for Financial Markets

The transition to tokenized financial infrastructure carries profound implications for the global economy. By removing manual processes—such as file sharing, reconciliation, and validation—financial institutions can significantly lower operational overhead.

Economic Efficiency and Risk Reduction

The primary economic argument for tokenization is the reduction of "friction." In current systems, the time elapsed between trade execution and settlement creates counterparty risk. Atomic settlement, as demonstrated by the Indian pilot, removes this temporal risk. Furthermore, the ability to program money and assets through smart contracts allows for greater transparency. Interest payments and principal redemptions, for instance, are now automated, reducing the possibility of human error or delayed processing.

The Future of Interoperability

A persistent challenge for the digital asset industry has been the lack of interoperability between different ledgers and banking ecosystems. The Singaporean pilot is notable because it leverages the existing, trusted Swift network to connect these silos. By using an established global messaging standard as the base layer for blockchain transactions, banks can maintain compliance and security while benefiting from the speed of DLT.

Strategic Outlook: From Pilot to Production

The regulators in India and Singapore have indicated that these projects are only the beginning. The RBI and SEBI have confirmed that Demat 2.0 will proceed in phases, with plans to introduce secondary market trading through existing request-for-quote platforms and, eventually, to extend participation to retail investors.

Similarly, Singapore’s commitment to its "Global Finance & Technology Network" (GFTN) suggests that the city-state will continue to refine its prudential rules to favor tokenized assets. By providing a clear, regulated path for these technologies, both nations are positioning themselves as the architects of the next generation of global financial infrastructure.

As these pilots conclude and move toward wider implementation, the financial sector must contend with the reality that the "digital" and "traditional" divide is rapidly closing. The successful integration of DLT into the daily operations of banks like DBS, OCBC, and UOB suggests that the future of banking will be defined by programmable, real-time settlement, and that the institutions that adapt to this tokenized paradigm will hold a significant competitive advantage in the coming decade.

The convergence of central bank digital currencies, smart contract-enabled securities, and interoperable interbank networks marks a clear path forward for the global financial system—a transition from the slow, batch-processed past to a future of continuous, automated, and instant value transfer.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Blockchain Technology

The Silicon Valley Cartel: How OpenAI, Anthropic, and Google DeepMind are Architecting AI Self-Regulation to Secure Market Dominance

by admin September 19, 2026
written by admin

The landscape of artificial intelligence governance underwent a seismic shift on September 15, 2026, as the industry’s leading frontier labs moved toward a centralized, self-regulatory framework. During a pivotal briefing in Washington, OpenAI Chief Global Affairs Officer Chris Lehane confirmed that his organization, alongside Anthropic and Google DeepMind, has been engaged in high-level coordination to establish a formal safety standards body. This initiative, modeled after the Financial Industry Regulatory Authority (FINRA), represents a significant departure from the decentralized, often chaotic approach to AI safety that has characterized the sector since the public debut of generative AI in 2022.

The proposed entity seeks to create an industry-funded, government-sanctioned framework that would mandate the review of advanced AI models up to 30 days prior to public release. While proponents argue this is a necessary step to prevent catastrophic risks, critics view the move as a sophisticated maneuver to secure a social license to operate while simultaneously erecting insurmountable barriers to entry for smaller competitors and the open-source community.

A Chronology of Coordination and Conflict

The path to this moment has been paved with strategic posturing and shifting alliances. The concept of a FINRA-style body first gained public traction on July 14, 2026, when Google DeepMind CEO Demis Hassabis proposed the model as a viable middle ground between unchecked innovation and restrictive government oversight.

The timeline of developments leading to the September 15 announcement highlights the acceleration of the industry’s lobbying efforts:

  • July 2026: Reps. Jay Obernolte and Zoe Trahan introduce the FRONTIER Act (H.R.9925), proposing an independent, NIST-backed verification system. This legislative threat serves as a catalyst for industry leaders to draft their own, more favorable, self-regulatory terms.
  • September 12, 2026: Anthropic CEO Dario Amodei publishes an expansive 3,800-word essay titled "We Must Pace the Frontier," calling for a deceleration in development cycles to ensure safety.
  • September 15, 2026: The Washington briefing confirms the coalition between OpenAI, Anthropic, and Google DeepMind. Simultaneously, at the Dreamforce conference, industry leaders including Meta’s Mark Zuckerberg and representatives from xAI and NVIDIA voice vocal opposition to government-mandated regulation.
  • Late September 2026: Reports emerge indicating that despite the public calls for a "pause" or "pacing," companies like Anthropic are internally evaluating new, high-performance model releases to compete with the anticipated GPT-6 Astra, underscoring the conflict between safety rhetoric and capital-driven growth.

The FINRA Precedent and the Risk of Regulatory Capture

The selection of the FINRA model is not coincidental. FINRA is a private, non-governmental organization that acts as the primary regulator for brokerage firms in the United States. While it provides a veneer of public oversight, it is funded and governed by the industry participants themselves. By adopting this structure, the "Big Three" of AI are attempting to preemptively capture the regulatory environment before federal agencies can establish independent, objective, and potentially restrictive oversight.

Economists and industry analysts have noted that this approach creates a "regulatory moat." When the entities that define the safety standards are the same entities that possess the capital and compute resources to comply with those standards, the outcome is almost invariably the exclusion of smaller players. Cohere CEO Aidan Gomez has been the most vocal critic of this consolidation, explicitly characterizing the proposal as a "cartel." Gomez draws historical parallels to the SEC’s 1975 NRSRO designation, which effectively granted a government-sanctioned monopoly to a handful of credit rating agencies, and the 1985 European Motor Vehicle Block Exemption, which entrenched automotive incumbents.

The Growth vs. Safety Paradox

At the heart of this initiative is a fundamental tension between the "safety thesis"—the idea that AI requires guardrails to prevent existential or societal harm—and the "growth thesis," which demands rapid, aggressive scaling to satisfy massive venture capital and institutional investor interest.

Investors have poured hundreds of billions of dollars into these companies under the assumption of exponential capability gains. A genuine, long-term industry-wide slowdown would arguably constitute a breach of fiduciary duty to those investors. Consequently, these companies are attempting to manufacture a version of "safety" that is compatible with high-speed development. By framing safety as an internal operating model rather than a hard regulatory constraint, the labs hope to satisfy regulators’ concerns about risk without actually throttling the pace of innovation that justifies their multi-billion-dollar valuations.

Legislative and Political Friction

The administration’s reaction to this initiative remains fluid. White House AI czar David Sacks has expressed skepticism, privately and publicly labeling the labs’ proposal as a potential instance of regulatory capture. The Trump administration, characterized by a preference for deregulation and competition, is wary of any framework that might stifle the U.S. advantage in the global AI race.

The FRONTIER Act remains the primary legislative alternative. By proposing that independent verification organizations (IVOs) be licensed by the National Institute of Standards and Technology (NIST) to perform audits every six months, the Act provides a structure that is far more transparent than the "closed-door" board envisioned by OpenAI and its allies. OpenAI’s Lehane has signaled that the labs are prepared to move forward with their standards body "with or without government support," a defiant stance that suggests a willingness to operate in a legal gray zone to maintain their competitive advantage.

Broader Implications for the AI Ecosystem

The implications of a successful, industry-led regulatory body are profound. First, it would likely formalize a hierarchy in the AI industry, where the "frontier" labs—those capable of training models at the multi-trillion-parameter scale—become the gatekeepers of the technology. Second, it would likely marginalize the open-source community, as any "safety standard" would inherently struggle to account for the decentralized and permissionless nature of open-weights models.

Furthermore, the fragmentation of the industry is now fully visible. Meta, which has staked its future on an open-weights strategy (Llama), finds itself at odds with the proprietary, closed-model approach of OpenAI and Anthropic. This split suggests that the future of AI governance will not be a unified consensus, but rather a battlefield of competing regulatory philosophies.

As of late September 2026, the industry remains in a state of strategic ambiguity. While the labs coordinate on safety protocols, they continue to compete fiercely on product performance, IPO timelines, and infrastructure deployment. Whether this coalition can survive the competing interests of its members and the looming scrutiny of federal regulators remains the defining question for the industry. For now, the "gatehouse" of AI safety is under construction, but it remains unclear who will hold the keys and who will be left on the outside looking in.

Ultimately, the move toward a FINRA-style body is less about the technical mitigation of AI risk and more about the institutionalization of the current power structure. By controlling the standard, these firms are effectively writing the rules of the game to ensure that their leadership is preserved, even as the underlying technology continues to evolve at a pace that few, if any, existing institutions are truly prepared to manage.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Blockchain Technology

Nearly One Million Investors Lose $3.8 Billion in Trump Memecoin Collapse as Industry Scrutiny Intensifies

by admin September 19, 2026
written by admin

The volatile intersection of modern politics and the digital asset economy reached a sobering milestone as blockchain analytics firm Nansen released data showing that nearly one million individuals have suffered a cumulative loss of $3.8 billion following investments in the $TRUMP memecoin. The digital token, which skyrocketed in popularity following its high-profile launch by President Donald Trump just days before his inauguration in 2025, has since shed nearly 98 percent of its peak value, leaving approximately two-thirds of its investor base nursing substantial financial damages.

Publicly available blockchain ledgers scrutinized by Nansen indicate that by the close of June, precisely 988,905 distinct crypto wallets or accounts had recorded net losses from trading the token. While early speculators and insiders managed to secure immense profits during the asset’s meteoric rise, the vast majority of retail participants who entered the market later found themselves holding depreciating digital assets. On Sunday, market data confirmed that $TRUMP was changing hands at a modest $1.69, a staggering drop from its all-time high of $75.35.

The fallout extends beyond the individual ledger of the $TRUMP token. It highlights a broader narrative concerning presidential involvement in digital finance, regulatory shifts under the current administration, and the distinct mechanics of memecoins—assets driven almost entirely by internet culture, celebrity endorsement, and speculative momentum rather than underlying utility or revenue-generating infrastructure.

Chronology and Background of the $TRUMP Token Launch

The genesis of the $TRUMP memecoin traces back to the final preparations for the second presidential inauguration in early 2025. Leveraging a brand built over decades in real estate, entertainment, and national politics, the venture was introduced to the public as a direct digital connection between the incoming commander-in-chief and his supporters worldwide.

The launch occurred amid a burgeoning portfolio of crypto-related initiatives associated with the Trump family. Prior to the memecoin’s debut, the president and his sons had co-founded World Liberty Financial, a decentralized finance startup centered around the $WLFI token. Like its memecoin counterpart, the $WLFI token has also experienced significant downward pressure, declining substantially from its initial valuations and drawing skepticism from traditional financial analysts regarding its long-term viability.

The $TRUMP token gained rapid traction across social media platforms, fueled by intense retail enthusiasm and speculative fervor typical of the broader memecoin market. However, unlike traditional equities or utility tokens tied to operational software, the token possessed no intrinsic economic backing, relying purely on market sentiment and continued interest to sustain its valuation. As initial momentum waned and early holders realized profits, the downward trajectory accelerated, ultimately leading to the widespread liquidation of retail portfolios documented by Nansen.

Financial Disclosures and Personal Windfall for the President

While nearly one million retail traders absorbed billions in losses, financial disclosure documents submitted by the president reveal a starkly different financial outcome for the issuer. According to the recent filings, President Trump amassed $636 million in personal revenue directly from the $TRUMP memecoin.

This monumental figure constitutes nearly half of the total $1.4 billion that the president reportedly generated from various cryptocurrency industry ventures over the preceding year. The convergence of official executive power and personal commercial enterprise within the digital asset sector has sparked vigorous debate among ethicists, lawmakers, and market participants. Critics argue that the promotion of speculative tokens by a sitting head of state creates an unprecedented conflict of interest, particularly when regulatory agencies under the executive branch hold direct authority over the digital asset ecosystem.

Trump memecoin investors lost $3.8 billion, analysis finds

Regulatory Shifts and the Position of the Securities and Exchange Commission

The financial losses incurred by retail investors coincide with a dramatic recalibration of federal oversight concerning digital assets. Since taking office, the administration has fostered a permissive regulatory environment designed to position the United States as a global leader in financial technology.

Under the leadership of appointees aligned with the administration’s pro-crypto agenda, the Securities and Exchange Commission (SEC) formally stated that it would not classify memecoins as traditional securities, thereby exempting them from the rigorous disclosure, registration, and investor protection mandates that govern stocks and bonds. Furthermore, the agency has moved to dismiss or scale back numerous high-profile enforcement actions and lawsuits against major domestic crypto firms and executives, including the prominent legal battle involving the Winklevoss twins and the Gemini exchange.

These policy decisions have fundamentally transformed the operational landscape for digital assets in the United States. Proponents of the administration’s approach argue that deregulation fosters innovation, prevents capital flight to overseas jurisdictions, and empowers individual financial freedom. A White House spokesperson defended the administration’s trajectory in a statement to the press, asserting, "President Trump proudly made the United States the crypto capital of the world."

Industry Analysis and Broader Economic Implications

Financial analysts and consumer protection advocates view the widespread losses associated with the $TRUMP token as a cautionary case study regarding the risks inherent in celebrity-backed speculative assets. Unlike established cryptocurrencies such as Bitcoin or Ethereum, which possess institutional backing and technological integration, memecoins often function as zero-sum financial games where late-stage retail investors absorb the losses of early entrants.

The scale of the $3.8 billion deficit underscores the urgent need for comprehensive financial literacy campaigns and clearer risk disclosures in the digital economy. Economists point out that retail investors, frequently drawn to high-yield digital assets by social media hype and parasocial loyalty to public figures, are ill-equipped to navigate the extreme volatility and lack of consumer protections characteristic of unregulated token markets.

Furthermore, the intersection of political influence and speculative finance raises systemic questions about market integrity. When political figures leverage their platform to promote volatile financial instruments, the boundary between public service and private commercial gain becomes blurred, complicating efforts by independent regulatory bodies to maintain fair and transparent markets.

Outlook for the Digital Asset Market

As the cryptocurrency market continues to mature through 2026, the legacy of the $TRUMP token collapse will likely reverberate across legislative and regulatory discussions. Lawmakers on Capitol Hill are facing renewed pressure from consumer advocacy groups to establish a specialized federal framework for digital assets that balances the imperative for technological innovation with basic safeguards for retail participants.

For the nearly one million affected investors, the financial recovery remains non-existent, serving as an expensive lesson in the hazards of speculative crypto trading. Meanwhile, the administration maintains its steadfast commitment to deregulation, signaling that the United States will continue down a path of expansive growth for the digital asset sector, regardless of the individual market corrections and investor casualties left in the wake of high-profile token booms.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Cybersecurity & Hacking

Global Law Enforcement Coalition Exposes North Korean Hacking Group WaterPlum in Massive Cyberespionage and Cryptocurrency Heist Campaign

by admin September 19, 2026
written by admin

An unprecedented multi-national law enforcement investigation has uncovered a massive, sophisticated cyberespionage and financial theft operation orchestrated by the North Korean state-sponsored threat group known as WaterPlum. According to a joint cybersecurity advisory issued by authorities in the United States, Japan, Australia, and Germany, the threat actors successfully compromised a minimum of 30,000 individual devices across more than 100 countries between December 2025 and July 2026. The coordinated offensive resulted in the illicit laundering of over $10.7 million in stolen cryptocurrency directly back to the Democratic People’s Republic of Korea (DPRK), serving to financially back the regime’s illicit weapons development programs.

The comprehensive joint report highlights the evolving tactics of state-backed hacking syndicates that target global IT professionals, software developers, and cryptocurrency investors. By blending advanced social engineering, AI-driven deception, and malicious software packaging, WaterPlum has established a pervasive threat infrastructure that weaponizes the recruitment processes of Western and allied technological firms.

Anatomy of the Campaign: The "Contagious Interview" Trap

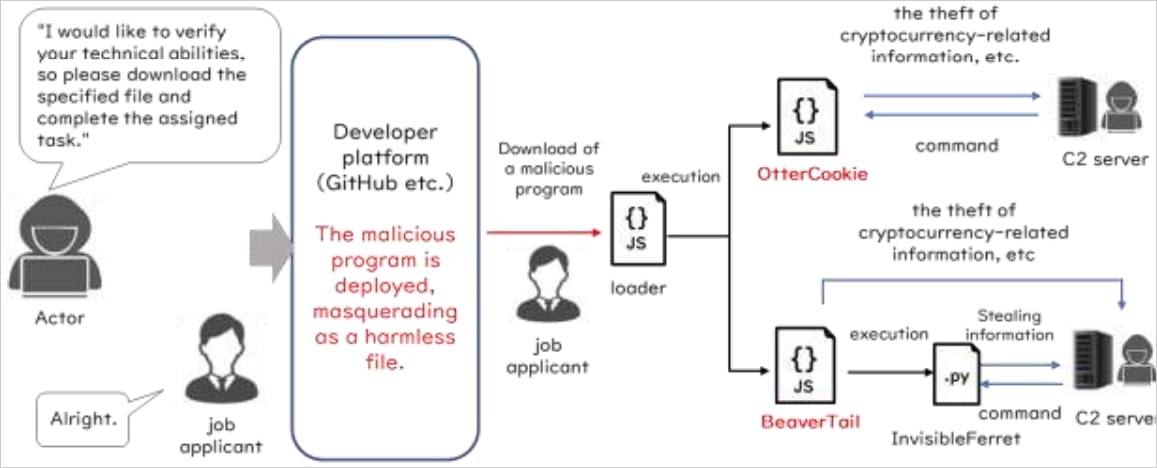
At the core of WaterPlum’s operational success is the multi-year "Contagious Interview" campaign. This sophisticated social engineering scheme heavily targets job seekers in the information technology and cryptocurrency sectors. The threat actors routinely pose as legitimate recruiters, human resources representatives, or executives from prominent artificial intelligence, cryptocurrency, and NFT enterprises. They utilize popular freelance marketplaces, professional networking sites, and specialized job boards to approach prospective targets with lucrative employment offers.

Once engagement is established, the victims are invited to participate in remote technical screenings, coding tests, or interviews. During these interactions, the attackers employ various ruses to compromise the victim’s hardware. Candidates are frequently instructed to clone and run specific open-source software projects, troubleshoot fabricated video-conferencing connection errors, or execute ostensibly harmless scripts required for the evaluation process.

In many instances, the campaign has leveraged malicious packages distributed via public code repositories, such as compromised npm packages, which silently deploy information-stealing malware the moment they are compiled or executed on a developer’s machine. Once inside the local environment, the malware aggressively harvests sensitive data. Investigators noted that the software is engineered to capture browser-stored credentials, clipboard contents, active keystrokes, personal documents, and screen captures. Crucially, the payload targets cryptocurrency infrastructure by extracting private keys and seed phrases from digital wallets. According to the international advisory, the group successfully compromised account credentials or exfiltrated funds from upwards of 7,000 individual cryptocurrency wallets worldwide.

North Korean WaterPlum hackers infected 30,000 devices worldwide

Chronology and Scale of the Threat

The timeline outlined by the coalition details a concentrated surge in operational activity stretching from the winter of 2025 through the summer of 2026. However, security researchers note that the foundations of the campaign extend years prior through iterative testing of supply-chain vector attacks.

By December 2025, intelligence agencies observed a dramatic uptick in anomalous cryptocurrency transactions linked to wallets controlled by the DPRK. Concurrently, software supply-chain monitors flagged an unprecedented influx of malicious packages designed to target software developers. Over the subsequent eight months, the coalition tracked the expansion of the botnet, culminating in the milestone of 30,000 infected devices by July 2026.

Financial tracing conducted by the coalition indicates that the threat actors successfully converted and transferred 1.7 billion Japanese yen—equivalent to approximately $10.71 million USD—into the DPRK. This capital injection directly supports state objectives, specifically feeding the financial reservoirs of the regime’s military research units.

Nexus with Fraudulent IT Worker Operations and AI Spoofing

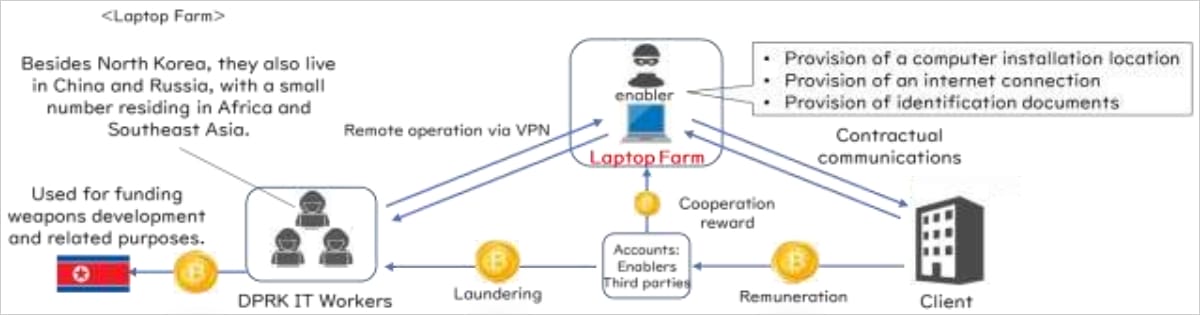
One of the most revealing findings within the joint advisory is the direct operational overlap between WaterPlum hackers and North Korea’s sprawling network of fraudulent overseas IT workers. Intelligence agencies discovered that individuals operating within the WaterPlum hacking collective frequently double as remote contract web developers for international clients. In several instances, forensic analysts identified shared infrastructure and identical Internet Protocol (IP) addresses utilized by both the cyberespionage hackers and the fraudulent IT workers.

Furthermore, the advisory highlights a grim cycle of identity theft. North Korean IT workers routinely utilize stolen identity documents—harvested directly through WaterPlum intrusions—to pass digital KYC (Know Your Customer) checks, complete background verifications, and secure high-paying remote employment with Western companies. Once hired, these operatives funnel a significant portion of their salaries back to Pyongyang, while simultaneously using their internal network access to conduct corporate espionage and intellectual property theft.

North Korean WaterPlum hackers infected 30,000 devices worldwide

To circumvent security measures during the hiring phase, WaterPlum operatives have increasingly adopted artificial intelligence-powered face-swapping software. During live video interviews, these actors deploy real-time digital avatars to mask their true appearance. When pressed or when technical glitches are simulated, the hackers deliberately disable their webcams, attributing the video feed failure to transient network instabilities.

Attribution to the 313 General Bureau and the "Laptop Farm" Bust

Law enforcement and intelligence assessments place the command and control of WaterPlum and its associated IT worker rings squarely under the jurisdiction of North Korea’s 313 General Bureau. This bureau operates as a subordinate entity within the Munitions Industry Department, the governmental body explicitly tasked with overseeing the research, development, and production of the nation’s ballistic missiles and nuclear weapons arsenal.

In a landmark domestic enforcement action, Japan’s National Police Agency announced that authorities had successfully identified, investigated, and physically dismantled a North Korean IT-worker "laptop farm" operating within the country. This marked the first time Japanese law enforcement dismantled such an infrastructure node on domestic soil. Investigators recovered substantial evidence indicating that several hundred million yen had been illicitly transferred overseas via the facility, which utilized proxy hardware to deceive foreign employers regarding the true geographic location of the workers.

Implications for Corporate Security and the Global Software Supply Chain

The revelations detailed in the joint advisory underscore a profound structural vulnerability in the modern remote-work economy. The globalization of the IT workforce, accelerated by post-pandemic remote work trends, has inadvertently provided state-sponsored threat actors with a frictionless entry point into critical corporate networks.

By infiltrating a single developer’s workstation, actors can easily pivot from personal environments into corporate networks, gaining unfettered access to proprietary source code, internal staging environments, and sensitive customer data. This creates a dual-threat vector: immediate financial extortion through ransomware and cryptocurrency theft, paired with long-term strategic espionage and intellectual property pillaging.

North Korean WaterPlum hackers infected 30,000 devices worldwide

Security analysts emphasize that traditional perimeter defenses are entirely inadequate against attacks initiated by trusted, authenticated remote employees whose credentials have been validated through fraudulent or stolen identities. The ability of hostile nation-states to weaponize the standard hiring pipeline turns a company’s own human resources and recruitment apparatuses into unwitting vectors for national security breaches.

Defensive Recommendations and Industry Guidance

In response to the escalating threat posed by WaterPlum and aligned DPRK cells, the issuing authorities—including the FBI, the Australian Cyber Security Centre (ACSC), the German Federal Office for the Protection of the Constitution (BfV), and Japan’s National Police Agency—have issued a comprehensive series of mitigation recommendations for organizations and individual developers alike.

For corporate entities and human resources departments, the agencies advise rigorous validation of applicant identities. Companies must move beyond basic video interviews by requiring robust multi-factor identity verification, conducting live reference checks, and cross-referencing employment histories with primary sources. Furthermore, organizations are strongly urged to enforce the principle of least privilege, restricting remote contractors and third-party developers to only the specific data repositories and infrastructure environments strictly required for their assigned tasks. Continuous behavioral monitoring of endpoints can help detect anomalous data exfiltration or unauthorized script executions in real-time.

For software developers and technical personnel, the advisory stresses strict hygiene regarding open-source dependencies. Developers should never execute unverified code, scripts, or binaries outside of a securely isolated sandbox environment. Codebases and dependency manifests should be carefully inspected for obfuscated commands, unexpected network callbacks, or unauthorized routines designed to fetch external payloads from remote servers.

As state-sponsored threat groups continue to refine their methodologies, integrating advanced AI capabilities and sophisticated social engineering, the international cybersecurity community emphasizes that organizational vigilance remains the primary bulwark against financially and politically motivated cyber campaigns.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Bitcoin & Altcoins

Ethereum Ecosystem Evolution: Strategic Grants and Research Initiatives for 2025 and 2026

by admin September 19, 2026
written by admin

The Ethereum Foundation and its associated ecosystem partners have unveiled a comprehensive slate of research, development, and educational initiatives scheduled for execution throughout 2025 and 2026. This expansive program focuses on the core pillars of network security, protocol scalability, zero-knowledge (ZK) proof integration, and the cultivation of a global developer workforce. By allocating resources to projects ranging from formal verification of cryptographic primitives to the decentralization of block-proving hardware, the ecosystem is positioning itself to address the technical complexities of post-quantum transition, client diversity, and the integration of artificial intelligence into blockchain infrastructure.

The Strategic Shift Toward Protocol Hardening

A central theme of the 2025–2026 development roadmap is the rigorous hardening of the Ethereum protocol. With the upcoming "Glamsterdam" upgrade on the horizon, significant efforts are being directed toward proactive vulnerability identification. Research teams are focusing on the consensus layer and execution layer clients to preemptively identify potential exploits. Notably, the development of the Lighthouse client is set to enter an intensive phase between May and October 2026, where engineers will prioritize ePBS (executable proposer-builder separation), Gloas, and partial message networking. This period of development also underscores a commitment to formal verification, with systems like ETHeorem being deployed to map protocol specifications directly to client implementations across major nodes such as Geth, Reth, and Prysm. By utilizing agentic systems that combine Large Language Models (LLMs) with program analysis, the ecosystem aims to achieve a level of full-stack coverage that was previously unattainable through manual audits alone.

Advancing Zero-Knowledge and Hardware Decentralization

The ZK-proof sector is witnessing a transformative shift toward hardware sovereignty. A major initiative, the "Ethproofs On-Prem Multi-GPU Prover" program, involves collaborations with entities such as Brevis, Succinct Labs, ZisK, and Matter Labs. These projects are tasked with transitioning Layer 1 block-proving stacks from centralized cloud providers to on-premise, multi-GPU hardware configurations.

This move is not merely technical; it is a strategic effort to reduce reliance on centralized infrastructure, which has long been identified as a single point of failure in scaling solutions. As these teams build out their respective stacks, they are committed to publishing an "On-Prem Ops Playbook." This open-source resource will provide the necessary documentation for future provers to maintain operational resilience. Complementing this, research into polynomial evaluation and the formal verification of zkVM circuits—such as those integrated into the CompPoly library—ensures that the mathematical foundations of these scaling solutions are robust against both current and future cryptographic threats.

Client Diversity and the Post-Quantum Frontier

The health of the Ethereum network is intrinsically tied to its client diversity. To ensure long-term resilience, the ecosystem is funding the development of several new consensus clients. The Lodestar project continues to provide vital support for the TypeScript and Zig communities, while the introduction of "Gean," a new Rust-based consensus client, aims to diversify the ecosystem from within Africa.

Furthermore, the Ream project is pushing the boundaries of what is possible with consensus clients. By developing a Rust-based, lean consensus client designed for 4-second slots and post-quantum readiness, Ream is testing the limits of network architecture. These efforts are supported by an intensive internship program for 2026, which sees participants working directly on Geth, protocol prototyping, and advanced cryptographic research. By embedding these interns into core development teams, the Ethereum Foundation is facilitating a knowledge transfer that bridges the gap between academic theory and production-grade implementation.

Privacy, AI, and User-Facing Infrastructure

The intersection of privacy and user experience (UX) represents the next frontier for Ethereum developers. Projects like the Open Anonymity Project are exploring unlinkable access to gated services through the use of blind signatures and TEE-friendly servers. Simultaneously, the development of the "Steward" wallet—a fully local, on-device smart account wallet—signals a trend toward self-sovereign, private AI interactions.

The integration of AI is not limited to end-user applications; it is also being applied to developer tooling. Tools such as "mevlog-rs" allow for local querying of on-chain data, while the "Cantina Apex" and "Octane" initiatives provide automated, AI-powered vulnerability scanning for smart contracts. These tools are designed to lower the barrier to entry for developers while maintaining high security standards. For instance, the "Web3j" library update ensures that the JVM and Android integration infrastructure remain compatible with the Glamsterdam upgrade, ensuring that the vast majority of enterprise-grade Java and Kotlin applications remain tethered to the network.

Global Education and Ecosystem Expansion

Beyond technical R&D, the ecosystem is making a concerted effort to decentralize its human capital. The "Blockchain Curriculum Train the Trainers" program for the Philippines is a prime example of this focus, enabling eight academic institutions in Mindanao to build sustainable blockchain curricula. Similar efforts are taking place in Bhutan, where an intensive residency program is cultivating a local cohort of Ethereum developers.

In higher education, the sponsorship of the Research Centre for Blockchain Technology at Hong Kong Polytechnic University demonstrates a commitment to nurturing the next generation of researchers. By providing scholarships and supporting engagement with global conferences like Devconnect and Asiacrypt, the Ethereum Foundation is fostering a global network of talent that is not tethered to any single geographical hub.

Analysis of Implications

The cumulative effect of these grants and initiatives is a shift toward a more modular, resilient, and academically rigorous Ethereum. By formalizing security models for encrypted mempools and investing in the "lean" architecture of new clients, the foundation is effectively "future-proofing" the network against both regulatory and technological disruptions.

The focus on formal verification—particularly the use of the Lean 4 proof assistant to verify everything from smart contract compilers to zkVM constraint systems—indicates a professionalization of the development process. As Ethereum matures into the primary settlement layer for global finance and digital public goods, the shift from "move fast and break things" to "prove correctness and build resilience" is a necessary evolution. The emphasis on capital instruments for digital public goods, as seen in the research into onchain ESG funding, further suggests that the network is looking to move beyond simple transaction processing and toward becoming a foundational substrate for global social and economic infrastructure.

Timeline and Expected Outcomes

  • Late 2025: Completion of initial formal verification pipelines for key consensus layer clients and the deployment of initial on-premise hardware setups for L1 block proving.
  • Q1 2026: Launch of the "Glamsterdam" upgrade and subsequent validation of client compliance through AI-driven agents.
  • Mid-2026: Expansion of the Bhutan and Philippine educational programs, expected to produce over 500 new developers skilled in Ethereum tooling.
  • Late 2026: Conclusion of the Lighthouse and Ream client development cycles, resulting in a more robust, post-quantum-ready network capable of supporting 10,000+ validators per devnet.

As these projects reach fruition, the Ethereum ecosystem is likely to see a significant reduction in cloud dependency and a marked improvement in the security posture of its smart contract layer. By proactively addressing the challenges of decentralization, privacy, and protocol complexity, the Ethereum Foundation is ensuring that the network remains the preferred choice for developers and institutions alike in the coming decade. The shift toward formal methods and on-premise hardware represents a maturing of the ecosystem, one that prioritizes long-term sustainability over short-term gains, thereby securing its position as a global digital public good.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Bitcoin & Altcoins

The Future of Finance: Why Changpeng Zhao Believes IPOs Are Destined for the Blockchain

by admin September 19, 2026
written by admin

The financial world witnessed a significant shift in discourse on September 8, 2026, when Binance co-founder Changpeng Zhao, widely known as CZ, took to the social media platform X to declare that "IPOs will move on-chain." This brief but consequential statement has ignited a global conversation regarding the modernization of capital markets, suggesting that the traditional Initial Public Offering (IPO) process—a cornerstone of corporate finance for centuries—is ripe for a radical technological overhaul. By shifting the mechanism of raising capital and distributing ownership onto decentralized ledgers, the industry could move toward a model where transparency, efficiency, and accessibility are programmatically enforced.

The Anatomy of the Traditional IPO

To understand the gravity of this proposal, one must first evaluate the inefficiencies inherent in the current financial ecosystem. An IPO is a complex, high-friction endeavor involving investment banks, underwriters, legal firms, and regulatory clearinghouses. Companies seeking to go public must navigate stringent compliance protocols, which often result in substantial administrative costs and weeks of waiting for settlement.

In the current paradigm, ownership is tracked through a tiered system of intermediaries. When an investor purchases shares, the transfer of ownership is recorded across databases managed by central securities depositories. This system is bound by "market hours"—typically operating during standard business days—and is plagued by settlement delays, often referred to as T+1 or T+2 cycles, where the actual movement of funds and securities takes days to finalize.

By moving these processes "on-chain," corporations could theoretically issue equity as digital tokens. This would eliminate the need for redundant record-keeping, as the blockchain acts as a single, immutable source of truth. Ownership transfers could occur near-instantaneously, and the barrier to entry for global investors could be lowered, potentially democratizing access to corporate ownership that was previously restricted by geographical or institutional gatekeeping.

Chronology of a Paradigm Shift

The transition toward on-chain finance did not happen overnight. It is the result of years of incremental development in the decentralized finance (DeFi) space.

  • 2020-2022: The emergence of real-world asset (RWA) tokenization began as a niche experiment, with early protocols attempting to bridge the gap between traditional assets and blockchain wallets.
  • 2023-2024: Institutional interest in stablecoins and digital ledger technology (DLT) grew, with major global financial institutions beginning to explore internal blockchain networks for bond issuance and collateral management.
  • 2025: The regulatory landscape began to shift, with several jurisdictions introducing clearer frameworks for digital securities, paving the way for more complex asset classes to be tokenized.
  • September 8, 2026: CZ’s definitive statement serves as a catalyst, signaling that the technological infrastructure is now mature enough to challenge the traditional stock exchange model.

The Role of BNB Chain in Financial Infrastructure

As the discourse surrounding on-chain IPOs gains momentum, the BNB Chain has emerged as a primary laboratory for this evolution. With a current ecosystem hosting over 700 tokenized stocks and exchange-traded funds (ETFs), the network is already functioning as a bridge between traditional finance (TradFi) and the decentralized web.

Binance has bolstered this position by introducing 1:1-backed tokenized securities. These assets are not merely speculative tokens; they are pegged to traditional financial instruments, allowing them to retain their economic value while gaining the programmability of blockchain assets. This functionality allows investors to interact with traditional stocks through DeFi protocols, such as using tokenized equity as collateral for loans or as liquidity in automated market makers (AMMs).

The integration of these assets into the BNB Chain has provided a blueprint for how future IPOs might function. If a company were to launch an IPO on-chain, it would bypass traditional brokerage interfaces, allowing for direct participation by investors globally, provided they satisfy the necessary Know-Your-Customer (KYC) and Anti-Money-Laundering (AML) requirements that will inevitably be embedded into the smart contracts governing these securities.

Market Implications and Economic Data

The immediate market reaction to CZ’s comments underscored the sensitivity of the crypto market to institutional-grade narratives. Following the post on September 8, the BNB token experienced a notable surge, climbing 1.5% in 24 hours to reach a trading price of $756.42. This volatility reflects investor anticipation that increased adoption of on-chain securities will drive significant transaction volume and network utility for the BNB Chain.

BNB Price Up 1.5% as CZ Predicts IPOs Will Move On-Chain

From an economic perspective, the shift toward on-chain equity could have profound implications for market liquidity. Traditional exchanges suffer from liquidity fragmentation and high latency. Blockchain networks, conversely, operate on a 24/7/365 basis. If an IPO were to move on-chain, it would effectively turn a corporate equity stake into a global, liquid asset that can be traded during weekends or holidays, drastically increasing the velocity of capital.

Furthermore, the role of stablecoins in this transition cannot be overstated. For an on-chain IPO to be successful, settlement must happen in a stable medium of exchange. The increasing adoption of fiat-backed stablecoins provides the necessary liquidity to settle these massive financial transactions, effectively replacing the aging clearinghouse infrastructure that currently supports modern equity markets.

Challenges and Regulatory Hurdles

While the technological feasibility of on-chain IPOs is increasingly apparent, the implementation remains subject to complex regulatory hurdles. Securities laws are designed to protect investors and ensure market integrity, and regulators globally—including the SEC in the United States and ESMA in Europe—are tasked with ensuring that any transition to blockchain does not create loopholes for market manipulation or fraud.

A key concern for regulators is the "pseudonymous" nature of blockchain. For an IPO to comply with global standards, the identities of token holders must be verifiable. Industry experts suggest that the future of on-chain stocks will likely involve "permissioned" blockchains or decentralized identity (DID) solutions, where users must prove their eligibility before they can interact with the smart contracts governing the stock.

Additionally, there is the matter of jurisdictional conflict. If a company goes public on a blockchain, which country’s laws govern the issuance? The legal community is currently working to reconcile corporate law with decentralized execution, and it is likely that the first wave of on-chain IPOs will be highly regulated, hybrid affairs rather than fully autonomous, anonymous offerings.

The Broader Vision: Beyond Stocks

The vision articulated by CZ extends far beyond the tokenization of common stocks. The ultimate goal is the migration of the entire capital market stack—including bonds, real estate, commodities, and complex derivatives—onto the blockchain.

By standardizing these assets on a common, programmable infrastructure, the global economy could see a reduction in the "cost of capital." The layers of middle-men—custodians, clearinghouses, and transfer agents—each extract fees and add time to financial processes. Removing these layers could significantly reduce the cost for companies to raise capital, potentially fostering a new era of entrepreneurship where even smaller firms can tap into global liquidity pools without the prohibitive costs of a traditional IPO.

Conclusion: A New Frontier

As of mid-September 2026, the industry stands at a threshold. While the transition from traditional markets to on-chain ecosystems will be a multi-year, perhaps multi-decade process, the trajectory is clear. The convergence of DeFi, tokenized real-world assets, and robust blockchain infrastructure like that of the BNB Chain is creating the necessary environment for this shift.

The comments made by Changpeng Zhao have served to focus the attention of both the crypto-native community and institutional stakeholders on the inevitable marriage of finance and code. Whether it is through the evolution of existing networks or the creation of new, purpose-built institutional chains, the move toward on-chain IPOs represents a fundamental reimagining of how ownership, value, and capital are managed in the digital age. As the ecosystem matures and regulatory clarity improves, the promise of a more efficient, inclusive, and transparent financial system may finally transition from a theoretical goal to a market reality.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Cryptography & Privacy

WhatsApp Encryption Under Fire: A Detailed Analysis of New Allegations, Lawsuits, and the Mechanics of Secure Messaging

by admin September 19, 2026
written by admin

Mainstream media coverage of cryptographic messaging applications rarely captures public attention for questioning the very existence of privacy features rather than debating their strength against government oversight. Over the past several days, however, public discourse has shifted toward a striking allegation: that WhatsApp, one of the world’s most widely adopted communication platforms, fundamentally lacks end-to-end encryption. This narrative marks a sharp departure from standard regulatory debates, where law enforcement agencies typically argue that applications like WhatsApp are excessively secure and impede criminal investigations. Following a wave of high-profile commentary from industry executives such as Elon Musk and Pavel Durov, alongside reports of preliminary federal inquiries, the technology sector has been forced to re-examine the mechanics and trustworthiness of commercial encryption at scale.

Origins of the Legal Challenge and Federal Scrutiny

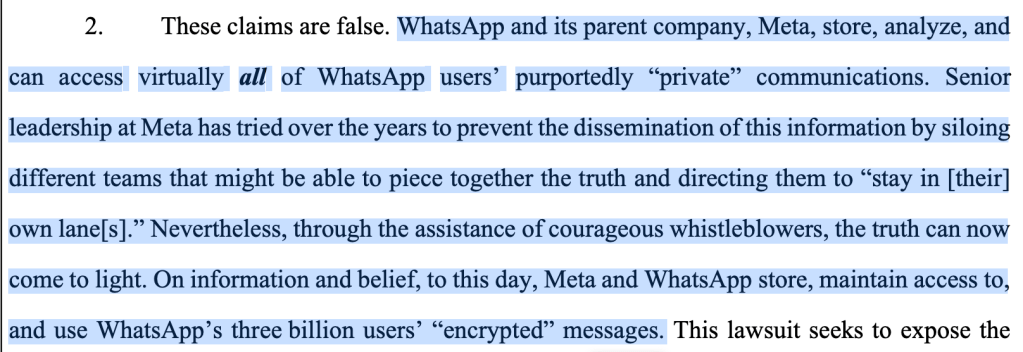
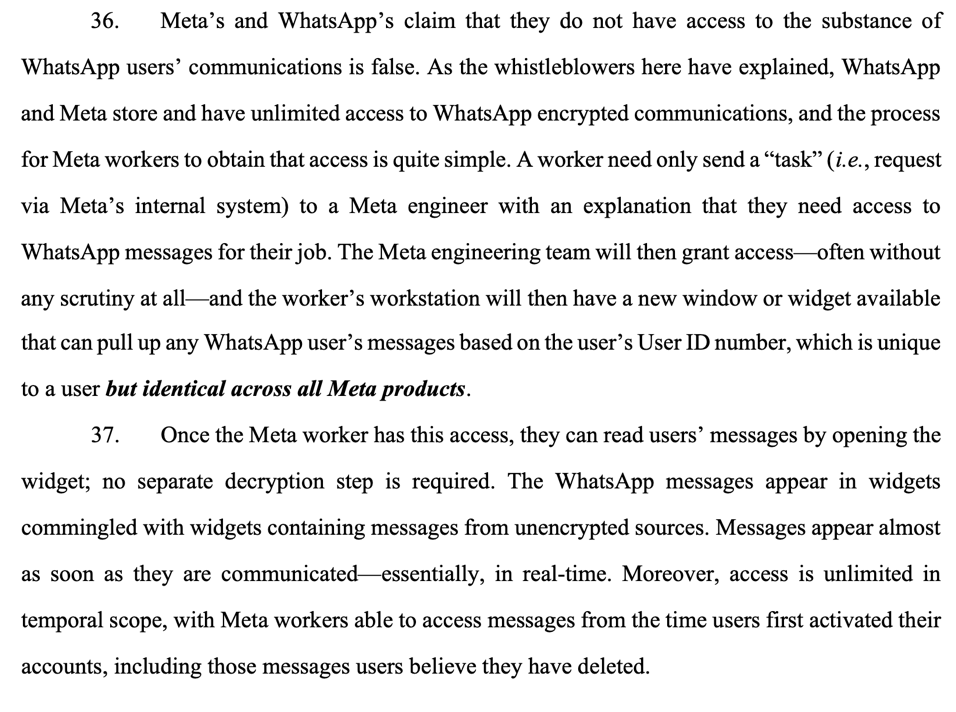
The controversy began with a class-action lawsuit filed by the prominent law firm Quinn Emanuel on behalf of several plaintiffs. The complaint alleges that while Meta—the parent company of WhatsApp—extensively markets the platform as utilizing end-to-end encryption to protect user communications, private data remains accessible to corporate infrastructure. The legal filing offers little direct technical evidence to substantiate its claims, yet it has been amplified across digital platforms by figures associated with competing messaging services.

Simultaneously, investigative reports from financial and technology media outlets have indicated that United States authorities have begun examining Meta regarding these claims. The intersection of private civil litigation and federal attention has transformed what might otherwise have been a standard legal dispute into a significant public relations and regulatory hurdle for Meta. Technologists and security researchers emphasize that while consumer skepticism toward major technology conglomerates is understandable, extraordinary allegations require rigorous, verifiable technical proof rather than speculative legal pleadings.

WhatsApp Encryption, a Lawsuit, and a Lot of Noise

The Scale of WhatsApp and the Implementation of End-to-End Encryption

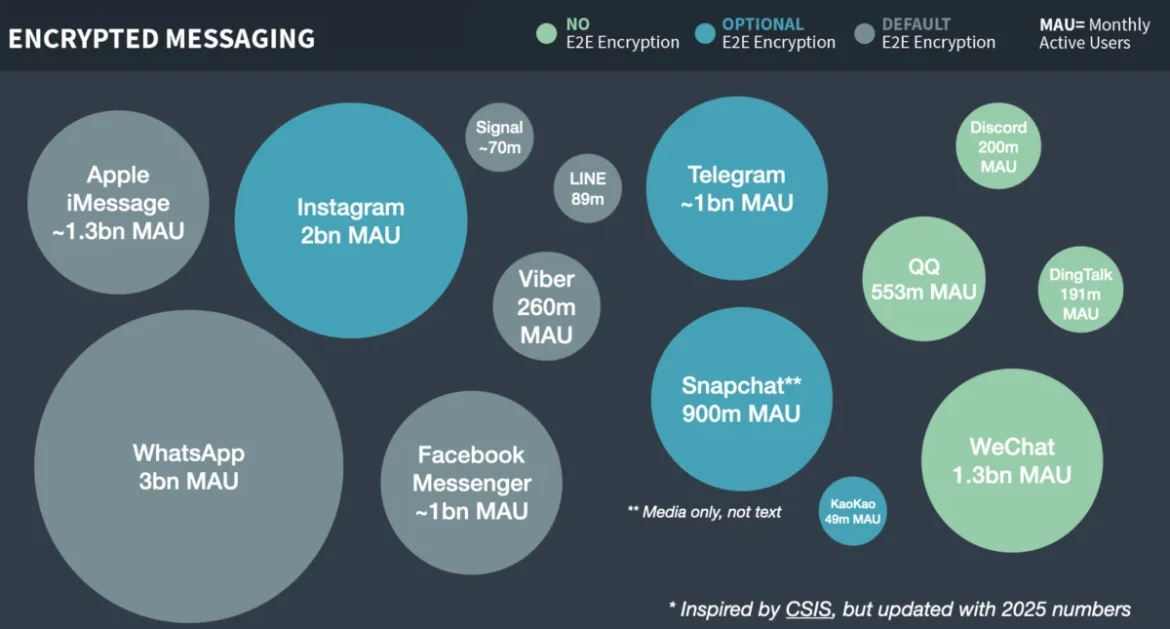
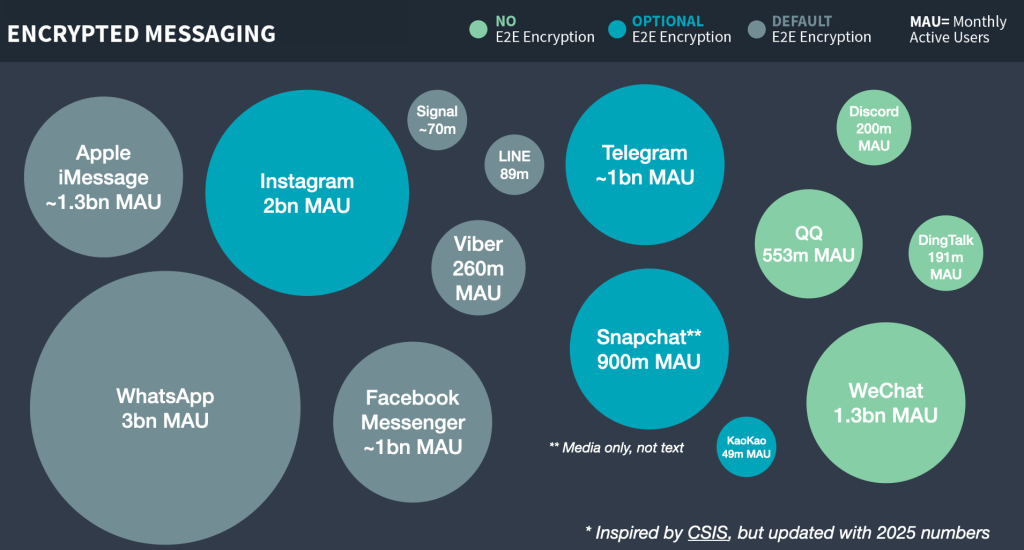
To evaluate the plausibility of these allegations, it is essential to examine the operational scale of WhatsApp and the architectural framework of modern messaging systems. Launched decades after the inception of primitive instant messaging technologies, contemporary communication apps operate on an unprecedented scale. WhatsApp currently serves approximately three billion monthly active users, representing nearly half of the global population. In numerous regions, the application functions as the primary infrastructure for personal and professional communication, surpassing traditional telecommunication services.

This vast scale presents profound data stewardship challenges. Historically, centralized messaging architectures required users to transmit data through corporate servers where it was stored in transit and, in many cases, at rest. This centralized storage model creates vulnerabilities, exposing vast quantities of real-time user data to potential breaches, unauthorized data harvesting, and compulsory legal demands from state actors.

In response to these systemic risks, WhatsApp’s original developers initiated the integration of end-to-end encryption beginning in 2014, adopting the robust Signal protocol following the platform’s acquisition by Facebook. Under a true end-to-end encryption architecture, messages are encrypted on the sender’s device and can only be decrypted on the intended recipient’s device. The cryptographic keys required for this process reside exclusively on the endpoints, theoretically preventing the service provider, network operators, and malicious third parties from intercepting or reading message contents.

Regulatory Friction and Government Pushback

WhatsApp Encryption, a Lawsuit, and a Lot of Noise

The large-scale deployment of default end-to-end encryption across billions of accounts was a transformative development for digital privacy, but it immediately generated acute political friction. Governments worldwide—including the United States, the United Kingdom, Australia, India, and member states of the European Union—have consistently expressed concern over the inability of law enforcement agencies to access communication content, even when armed with valid judicial warrants.

In October 2019, the United States Department of Justice, alongside international counterparts, issued a formal open letter urging Meta to halt the expansion of end-to-end encryption across its ecosystem unless verifiable lawful access mechanisms, commonly referred to as backdoors, were incorporated. Meta resisted these demands, maintaining that weakening encryption for law enforcement compromises security for all users globally. Consequently, the company expanded cryptographic protections to Facebook Messenger and introduced optional encrypted features for Instagram direct messages, cementing its position as a primary target for governments seeking exceptional access capabilities.

Technical Feasibility of a Secret Backdoor

Analyzing the core allegation that WhatsApp’s encryption is illusory requires assessing what such a capability would entail from a software engineering perspective. Because WhatsApp’s client application runs locally on user devices, executing a mass surveillance or key-exfiltration scheme without detection would necessitate deliberate modifications to the client-side code. Specifically, the application would need to continuously export unencrypted plaintext messages or duplicate encryption keys to Meta’s servers for every active user.

Security researchers note that while WhatsApp is proprietary and closed-source—preventing public compilation and verification of the exact source code—historical and current versions of the compiled application are publicly accessible through various repositories. Experts routinely decompile these packages to analyze network traffic, forensic artifacts, and application behavior. Implementing a systemic bypass of end-to-end encryption at a scale encompassing three billion users would leave highly visible forensic traces within the application binaries and network telemetry.

WhatsApp Encryption, a Lawsuit, and a Lot of Noise

While sophisticated server-side attacks, such as man-in-the-middle key substitution, have been theoretically proposed by intelligence agencies to target specific individuals, executing a mass-scale compromise of this nature without detection is considered highly improbable by the cryptographic community. The probability that independent security researchers, reverse engineers, and forensic analysts would fail to detect systemic data exfiltration across billions of active devices over an extended period remains extremely low.

Evaluating Real-World Loopholes and Metadata Collection

Discussions surrounding messaging security often conflate the absolute protection of message content with peripheral data exposures. Critics frequently highlight existing architectural realities that, while fully disclosed by WhatsApp, are sometimes misinterpreted as evidence of compromised encryption.

First, end-to-end encryption protects the literal content of private communications, but it does not inherently shield metadata. Information regarding communication frequency, timestamps, participant identities, and social graph structures remains visible to platform infrastructure.

Second, user convenience features introduce separate security considerations. Cloud-based message backups—stored on third-party infrastructure such as Apple iCloud or Google Drive to facilitate device migration—have historically lacked default end-to-end encryption unless explicitly configured by the user with additional cryptographic keys.

WhatsApp Encryption, a Lawsuit, and a Lot of Noise

Third, commercial integrations and artificial intelligence features introduced by Meta, such as automated customer service interactions or optional AI writing assistants, rely on specific processing environments. While technologies like Trusted Execution Environments are utilized to protect user data during off-device processing, these optional features represent operational boundaries distinct from core peer-to-peer messaging. However, security analysts emphasize that none of these known operational loopholes or metadata practices support the severe allegations presented in the current class-action lawsuit, which alleges a wholesale absence of encryption for standard personal chats.

Implications for Digital Trust and Industry Standards

The recent legal challenge and subsequent media coverage underscore the delicate balance of trust inherent in modern digital communications. Cryptographic protocols do not eliminate the necessity of trust entirely; rather, they extend trust from an institution to specific software implementations, hardware environments, and cryptographic primitives.

As computer scientist Ken Thompson famously demonstrated in his foundational work on computing trust, absolute verification of complex software stacks remains a persistent challenge in computer science. Users of closed-source applications ultimately place a degree of trust in the vendor’s stated architecture and independent security audits.

For users who find the requisite level of corporate trust unacceptable, open-source alternatives with reproducible builds, such as Signal, provide a verifiable cryptographic model. Nevertheless, the prevailing consensus among independent cryptographers and security engineers suggests that the extraordinary claims presented in the recent WhatsApp lawsuit lack verifiable technical backing. Absent concrete forensic evidence demonstrating a systemic cryptographic failure, the platform’s end-to-end encryption implementation continues to provide the functional privacy guarantees for which it was originally designed.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

FinovateFall 2026 Crowns Best of Show Winners as AI-Driven Efficiency Redefines Financial Services

by admin September 19, 2026
written by admin

The conclusion of FinovateFall 2026 has marked a definitive shift in the fintech landscape, where the focus has pivoted from speculative artificial intelligence experimentation to the practical application of agentic AI in core banking operations. As the votes were tallied following an intensive multi-day demonstration schedule, eight companies emerged as the official Best of Show winners. These organizations were selected by an audience of financial industry professionals, reflecting a collective industry preference for solutions that tangibly address deposit growth, operational simplification, and the modernization of legacy infrastructure.

The Evolution of the Fintech Showcase

FinovateFall has long served as a bellwether for the financial technology sector, providing a platform where startups and established players alike showcase their latest innovations through rapid, seven-minute, slide-free demonstrations. Since its inception, the conference has moved from promoting mobile banking and P2P payments to today’s current frontier: the integration of autonomous AI agents that act on behalf of financial institutions to streamline workflows that were previously bogged down by manual, siloed processes.

FinovateFall 2026 Best of Show Winners Announced!

The 2026 edition underscored a maturation in the market. While AI was present in virtually every demonstration, the narrative shifted away from "AI for AI’s sake" toward a focus on compliance, customer experience, and the bottom line. Attendees, who were tasked with voting on the basis of demo quality and the potential impact of the technology, clearly signaled that the most valuable innovations are those that bridge the gap between complex data and actionable insights for both the institution and the end-user.

Analysis of the 2026 Best of Show Winners

The winners selected by the audience represent a diverse cross-section of the modern financial services stack, ranging from consumer-facing wellness tools to backend performance enablement.

Clockout: Addressing Liquidity and Wellness

Clockout secured its position among the winners by targeting the critical issue of deposit growth. By embedding financial wellness directly into the user experience, the company reported an ability to drive direct deposit increases of 10% to 25%. This model highlights a growing trend where banks are moving beyond simple transaction processing to becoming active participants in the financial health of their customers, generating significant monthly per-user revenue in the process.

FinovateFall 2026 Best of Show Winners Announced!

equipifi: Modernizing Native Digital Banking

In an era where consumer expectations for flexible payment options are at an all-time high, equipifi’s success demonstrates the demand for Buy Now, Pay Later (BNPL) capabilities that reside within the bank’s own ecosystem. By allowing financial institutions to offer these services natively, equipifi helps banks retain the relationship and the data, preventing the fragmentation caused by third-party payment providers.

Goodbuy: Connecting Community Commerce

Goodbuy’s platform represents a strategic attempt to revitalize local banking by linking account activity to community engagement. By transforming local small business transactions into a growth channel for banks, the solution addresses the perennial challenge of card activation and interchange growth, proving that local community ties remain a potent differentiator for regional institutions.

Neural Payments: Bridging the Rail Gap

The complexity of the modern payment landscape—spanning real-time rails, traditional networks, and digital wallets—remains a major pain point for community banks. Neural Payments’ Payments Hub was recognized for its ability to unify these disparate systems into a single, branded integration. This is a direct response to the "siloed systems" identified by industry leaders as a primary barrier to operational efficiency.

FinovateFall 2026 Best of Show Winners Announced!

ScreenSteps: Operational Performance Enablement

Not all fintech innovation occurs at the customer interface. ScreenSteps was honored for its work in the internal operations space, focusing on performance enablement. By converting dense, legacy procedural manuals into real-time, digestible guidance for employees, the company is tackling the "hidden" costs of manual operations, reducing error rates and training times for financial services staff.

Tweezr: Modernization Without the Overhaul

Legacy systems remain the greatest challenge for incumbent financial institutions. Tweezr garnered support for its approach to developer productivity and legacy maintenance. By accelerating time-to-market and potentially obviating the need for total "rip-and-replace" modernization projects, Tweezr provides a pragmatic path forward for banks struggling with technical debt.

Vertice AI: Strategic Automation

Vertice AI’s recognition highlights the power of agentic AI in the marketing department. The company’s OPTIMIZE solution moves beyond basic data analytics, utilizing AI to execute complex marketing campaigns while maintaining human oversight at the strategic level. This represents the next phase of AI adoption: autonomous execution within a strictly governed, compliant framework.

FinovateFall 2026 Best of Show Winners Announced!

Young Early Starters: The Next Generation

Rounding out the winners, Young Early Starters focuses on the long-term future of finance. By providing an investing and education platform that allows children to own real stock, the company is tapping into the generational transfer of wealth and the necessity of early financial literacy, providing a value-add that appeals to family-oriented banking segments.

Broader Industry Implications

The data from this year’s FinovateFall suggests that financial institutions are entering a period of consolidation regarding their technology stacks. The success of these eight firms indicates a shift toward "integrated utility." Banks are no longer looking for standalone point solutions; they are looking for platforms that can plug into their existing infrastructure to deliver measurable ROI.

The emphasis on agentic AI—software that can perform tasks, make decisions, and complete processes without constant human intervention—marks a significant leap from the predictive AI models of 2024 and 2025. This transition is not merely technical; it is economic. As institutions face pressure to maintain margins in a high-rate environment, the ability to automate routine tasks while simultaneously deepening customer relationships has become the primary metric of success.

FinovateFall 2026 Best of Show Winners Announced!

Methodology and Governance

The integrity of the "Best of Show" selection process remains a cornerstone of the Finovate brand. To ensure the results represent the consensus of the fintech community, only verified attendees without ties to the demoing companies were permitted to vote. Each voter was instructed to evaluate demonstrations based on two primary criteria: the quality of the presentation and the potential impact of the innovation on the industry.

This rigorous, audience-driven approach distinguishes Finovate from industry awards that are determined by editorial boards or paid panels. By crowdsourcing the selection, the results act as a real-time market survey of what industry insiders believe will move the needle over the coming 12 to 24 months.

Looking Ahead: FinovateSpring 2027

As the industry digests the lessons of FinovateFall 2026, the focus now shifts toward the next gathering. FinovateSpring 2027 is scheduled to take place at the Gaylord Pacific Resort and Conference Center in San Diego, California, from May 3rd through May 5th.

FinovateFall 2026 Best of Show Winners Announced!

The upcoming conference is expected to expand on the themes of agentic AI and operational resilience. For those looking to participate, early registration is currently open, with significant incentives for those who secure their attendance before the November 6th deadline. The trajectory set by the 2026 winners confirms that the future of finance lies in the seamless integration of human-centric goals and machine-driven efficiency. The industry’s challenge, as demonstrated by the winners, will be to maintain this momentum while navigating the complex regulatory and security requirements that define the modern financial sector.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
FinTech Innovations

Anthropic Eyes November IPO Debut in Potential Record-Breaking $2 Trillion Public Offering

by admin September 19, 2026
written by admin

Artificial intelligence pioneer Anthropic is reportedly adjusting the timeline for its highly anticipated initial public offering (IPO), shifting its planned public market debut from October to November. According to sources familiar with the matter cited by financial media outlets, the strategic adjustment is designed to allow the company to incorporate its robust third-quarter financial results into its public disclosures, reassuring prospective investors of its underlying economic strength even as broader macroeconomic and sector-wide debates surrounding artificial intelligence unfold.

The decision to target November comes at a critical juncture for the generative AI sector. While regulatory scrutiny and public discourse regarding the pace of AI development have intensified, foundational model providers continue to experience unprecedented commercial demand. If executed within projected parameters, Anthropic’s public market entry could value the company at approximately $2 trillion and successfully raise up to $100 billion in capital. Such a milestone would eclipse historical fundraising and valuation benchmarks, surpassing the record-setting public and private transaction milestones achieved by aerospace heavyweight SpaceX earlier in the year.

Financial Momentum and the Road to the Public Markets

The acceleration of Anthropic’s financial performance underpins the aggressive valuation targets set for the upcoming IPO. Industry reports indicate that the company’s annualized revenue run rate experienced exponential growth over a remarkably short window. At the close of 2025, Anthropic’s revenue run rate stood at approximately $9 billion. By the end of July, that figure had surged to an astonishing $65 billion, with projections suggesting annualized revenues could eclipse $100 billion throughout 2026.

This meteoric top-line expansion has provided leadership with the necessary leverage to proceed with public market plans, despite a shifting sentiment among investors regarding technological saturation and safety governance. The confidential IPO filing process began earlier this year, establishing the groundwork for what financial analysts anticipate will be a watershed moment for technology sector liquidity.

The chronology of Anthropic’s public market journey highlights a calculated approach to market readiness:

  • June 1, 2026: Anthropic formally announces that it has confidentially filed the necessary paperwork with regulators for an initial public offering, noting that the ultimate debut would depend on prevailing market conditions and corporate milestones.
  • Mid-September 2026: Reports emerge detailing the shift from an October target to November, strategically aligned with the finalization and release of third-quarter financial statements.
  • Upcoming November 2026: Anticipated public debut window, subject to final market conditions, regulatory sign-offs, and macroeconomic stability.

Divergent Paths: Anthropic Versus OpenAI

While Anthropic moves steadily toward a public listing, its primary rival in the generative AI space, OpenAI, has charted a distinctly different course regarding market timelines. OpenAI CEO Sam Altman addressed the company’s capitalization strategy during industry interviews in September, explicitly stating that OpenAI would not pursue an IPO in 2026.

Altman emphasized that OpenAI is under no immediate pressure to transition into a publicly traded entity. Citing mounting concerns regarding artificial intelligence safety, alignment, and the societal implications of rapid frontier model scaling, Altman noted that the current environment represents an ill-advised moment to introduce the company to the public equity markets. Nevertheless, like Anthropic, OpenAI submitted its own confidential IPO paperwork on June 8, signaling that while the foundational infrastructure for a public offering is in place, the strategic timing remains flexible.

The contrast between Anthropic’s willingness to brave the public markets this autumn and OpenAI’s conservative posture underscores the varied risk appetites and corporate governance strategies governing the leading players in the artificial intelligence landscape.

Macroeconomic Context and Enterprise AI Adoption

The looming public debuts of the sector’s titans arrive against a backdrop of intense debate among economists, policymakers, and technologists regarding the sustainability of current AI investment levels. Questions have been raised regarding whether the rapid pace of frontier model development might face a temporary plateau, either due to computational bottlenecks, diminishing returns in training data, or heightened regulatory oversight focused on safety and data privacy.

However, market data and enterprise technology analysts suggest that a potential slowdown in the velocity of frontier model breakthroughs will not impede broader commercial adoption. Industry experts note that enterprise customers have shifted their focus from the speculative novelty of foundational models to the practical implementation, integration, and return on investment of existing capabilities.

Maya Mikhailov, CEO and co-founder of Savvi AI, noted in recent industry commentary that commercial entities are heavily invested in operationalizing artificial intelligence regardless of whether a new generation of frontier models is deployed immediately. Enterprises are prioritizing workflow automation, data security, and productivity gains derived from mature AI tools, ensuring a steady, reliable demand stream for infrastructure and application providers alike.

Implications for Global Capital Markets

An Anthropic valuation reaching the $2 trillion threshold would fundamentally alter the composition of global equity markets, cementing artificial intelligence providers as foundational pillars of the modern economy alongside legacy cloud providers and semiconductor giants. Raising up to $100 billion would also represent the largest capital-raising event in public market history, testing the depth and liquidity of international capital markets.

Financial institutions and institutional investors are expected to scrutinize Anthropic’s upcoming third-quarter disclosure closely. Key metrics—including enterprise retention rates, compute cost efficiencies, and gross margins—will serve as a proxy for the entire generative AI sector’s long-term economic viability.

As November approaches, market participants will monitor regulatory developments, macroeconomic indicators, and potential shifts in investor sentiment. Whether Anthropic successfully executes its historic public offering as planned will likely set the valuation tone and operational expectations for the entire next generation of artificial intelligence enterprises for years to come.

September 19, 2026 0 comment
0 FacebookTwitterPinterestEmail
Newer Posts
Older Posts

Recent Posts

  • Ethereum Network Upgrade Update: Glamsterdam Activation on Hoodi Postponed
  • Kraken Expands Its Digital Asset Offerings With the Official Listing of NEXO
  • Cardano Price Faces Mounting Bearish Pressure as Whale Holdings Contract and Technical Indicators Signal Further Correction
  • Web3 Fundraising Surges to Record Highs in Third Quarter of 2025 as Institutional Capital Takes Center Stage
  • Beyond the Hype: Why Financial Institutions Are Rethinking Their AI Strategies in 2026

Recent Comments

No comments to show.
  • Facebook
  • Twitter

@2021 - All Right Reserved. Designed and Developed by PenciDesign


Back To Top
Dr Crypton
  • Home
  • About Us
  • Contact Us
  • Cookies Policy
  • Disclaimer
  • DMCA
  • Privacy Policy
  • Terms and Conditions

We are using cookies to give you the best experience on our website.

You can find out more about which cookies we are using or switch them off in .

Dr Crypton
Powered by  GDPR Cookie Compliance
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.

Strictly Necessary Cookies

Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.