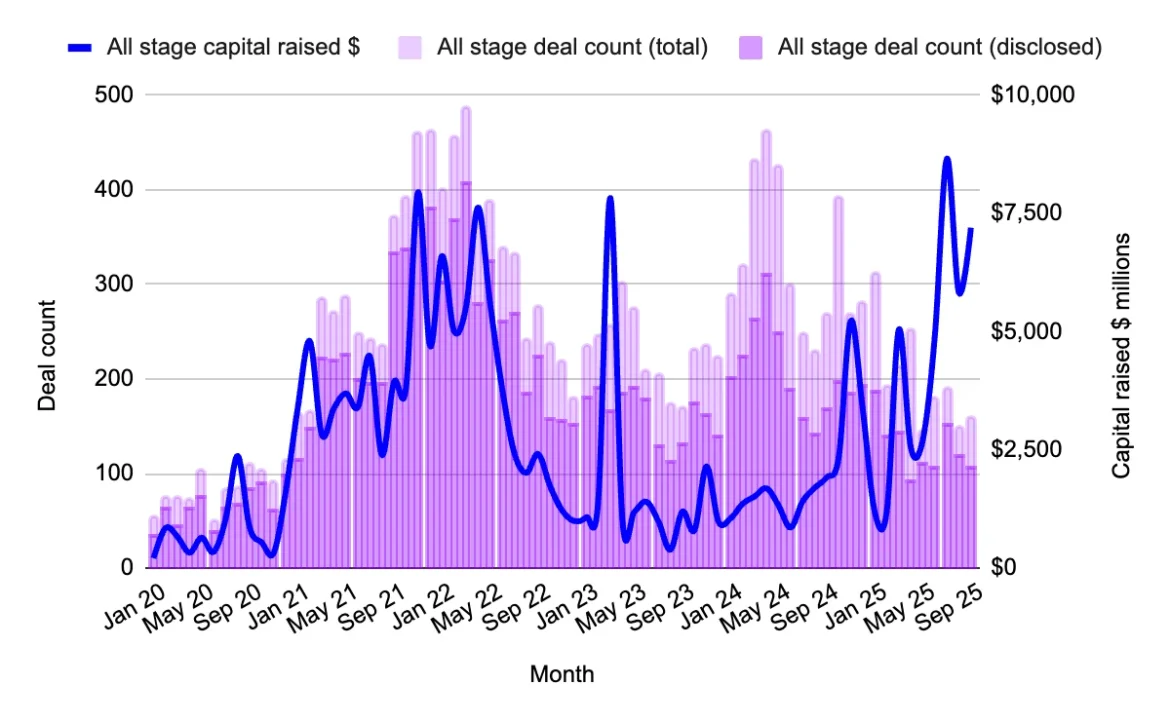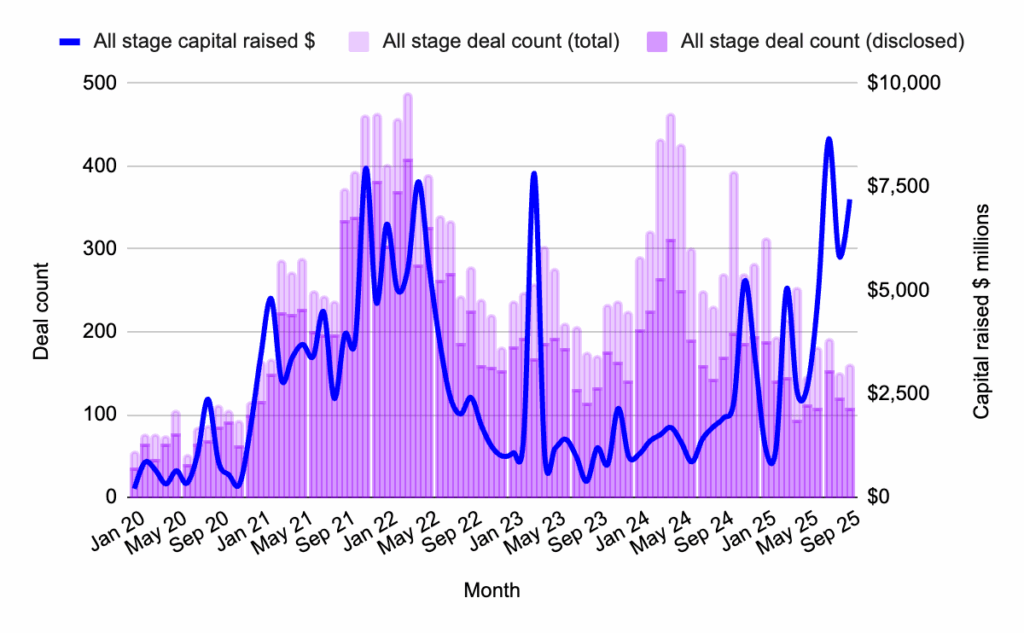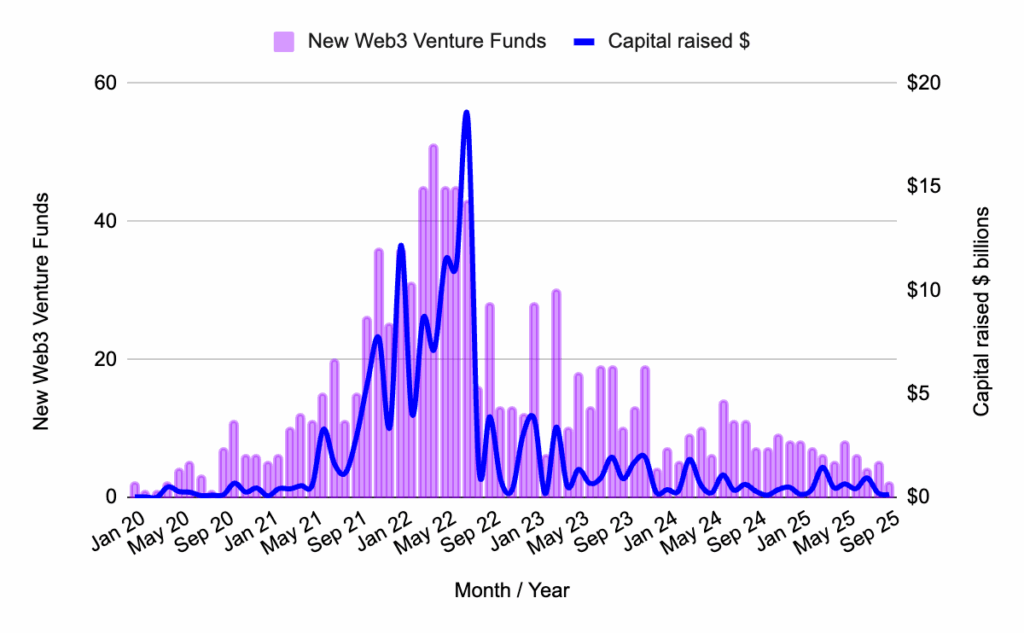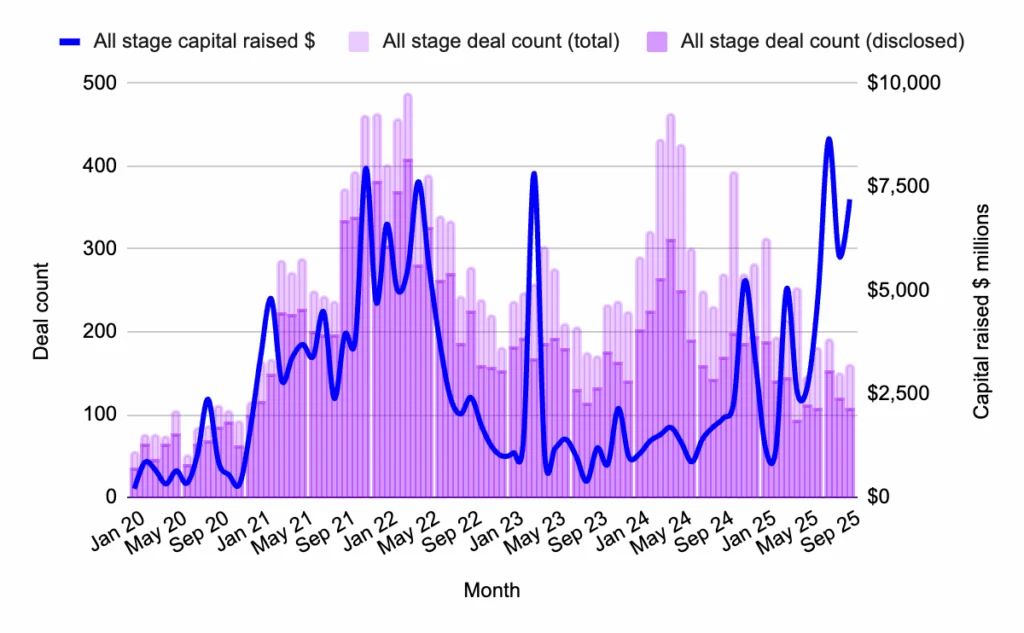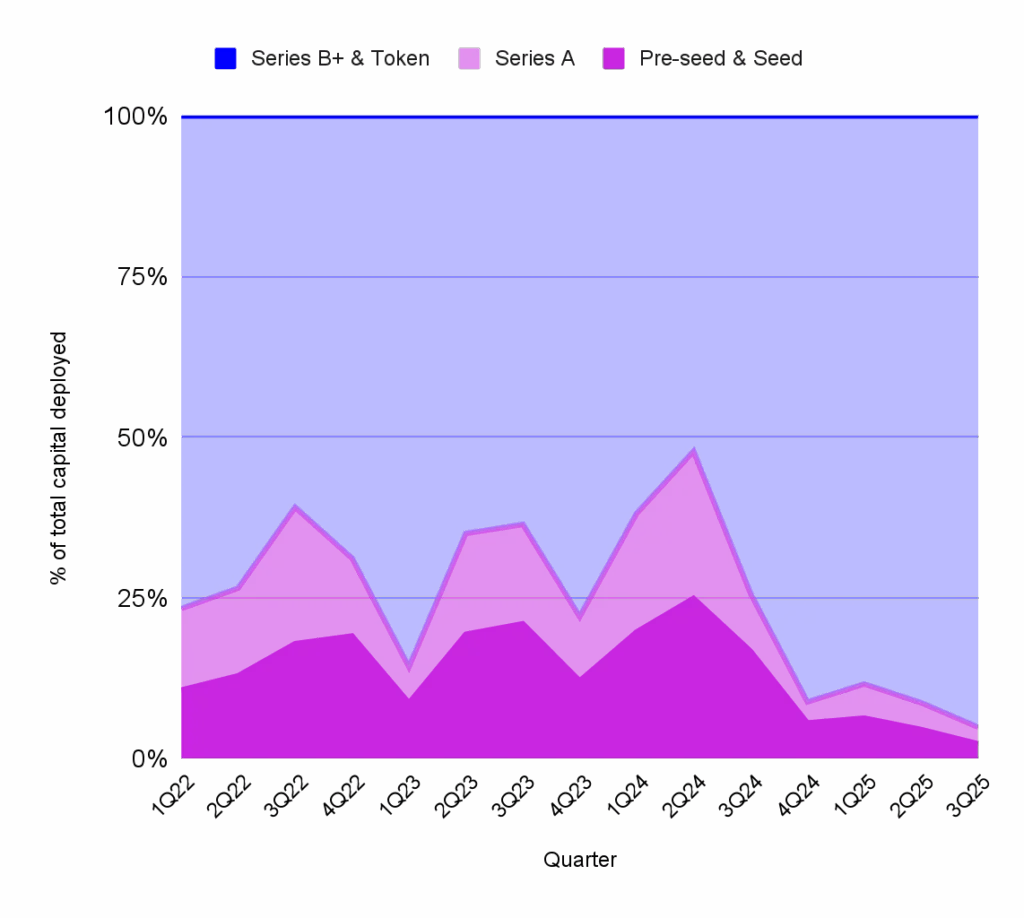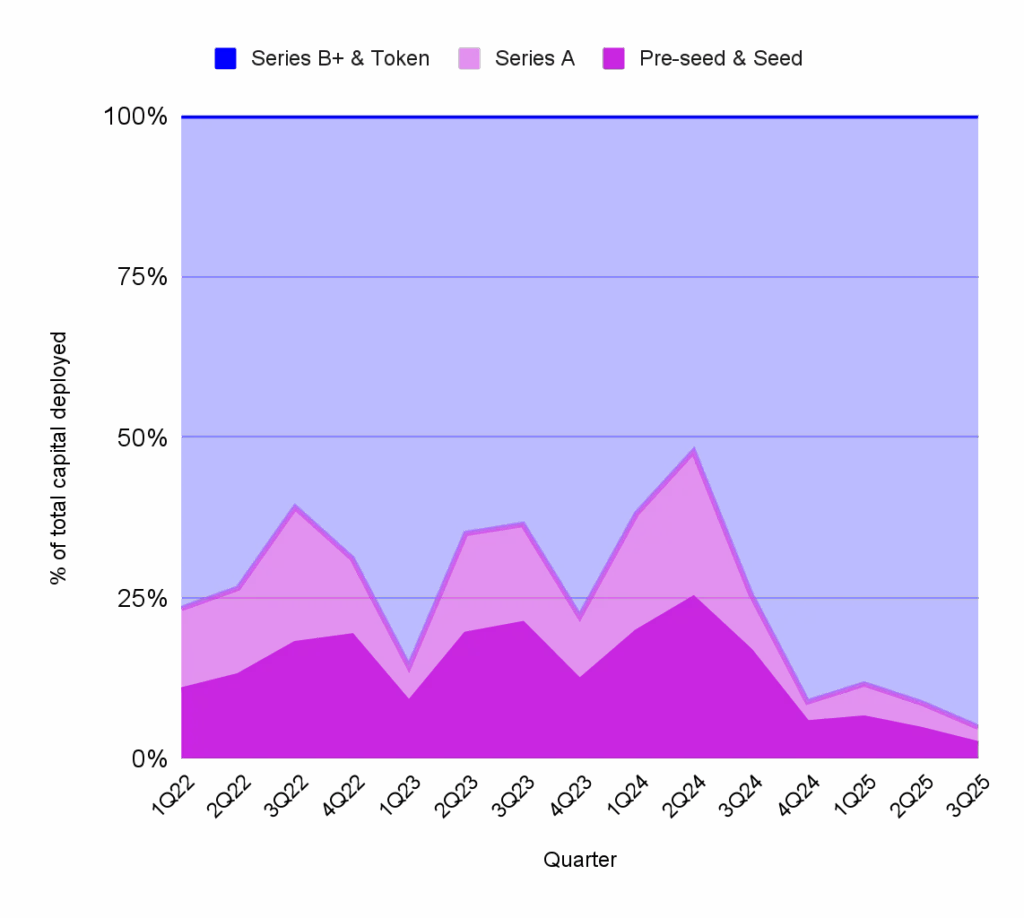
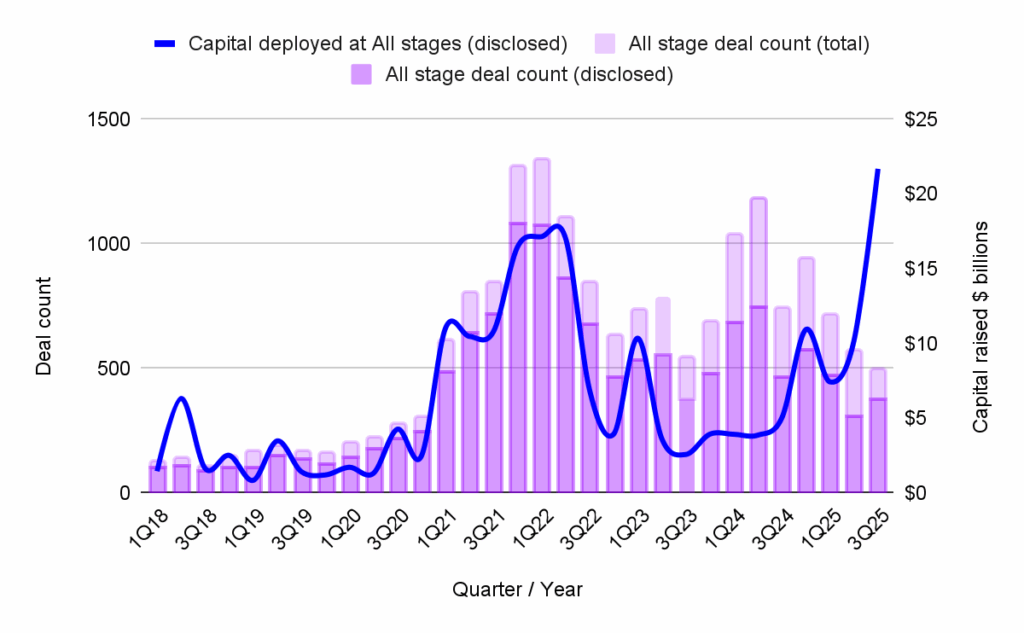
The landscape of Web3 venture funding underwent a massive transformation during the third quarter of 2025, recording a cycle high of nearly $22 billion deployed across 376 disclosed deals globally. According to comprehensive market intelligence data compiled by Outlier Ventures and Messari, aggregate capital commitments more than doubled quarter-on-quarter, leaping by 113 percent from the $10.2 billion observed in the second quarter of 2025. This historic influx of liquidity outpaced the growth in total deal volume, which rose by a modest 22 percent from 309 transactions. Financial analysts note that this pronounced divergence highlights a market driven decisively by larger, highly concentrated institutional tickets rather than a broad-based surge in early-stage entrepreneurial activity.

The third quarter performance eclipses even the peak fundraising metrics of the 2021 and 2022 bull markets in terms of sheer capital concentration. However, industry experts emphasize that this cycle is defined by an ethos of conviction over coverage. While historical cycles were frequently characterized by speculative dispersion across thousands of nascent protocols, the current environment exhibits a disciplined focus on infrastructure, regulatory compliance, and scalable financial integration.
The Institutional Architecture of Modern Crypto Finance
The structural shift observed in the third quarter of 2025 stems from the maturation of institutional financial channels. Unlike previous eras driven largely by retail exuberance and speculative momentum, the current market is anchored by operationalized traditional finance frameworks, including exchange-traded funds (ETFs), digital asset treasuries (DATs), tokenization initiatives, and enterprise-grade settlement rails.
Data from Messari’s Q3 reviews indicate that Ethereum-focused ETFs experienced a watershed period, capturing approximately $8.7 billion in inflows during the quarter and surpassing Bitcoin-focused counterparts. Total assets under management (AUM) for Ethereum ETFs surged by roughly 170 percent quarter-on-quarter to reach $27.4 billion. Concurrently, digital asset treasuries secured approximately 3.8 percent of the circulating Ethereum supply, signaling a structural evolution in corporate treasury management.
Major traditional financial institutions transitioned their digital asset strategies from conceptual pilots to active production environments during this period. JPMorgan’s Kinexys network went live for tokenized repurchase agreement settlements, while SWIFT expanded its multi-party tokenization trials in collaboration with global custodians such as BNY Mellon, Citi, Clearstream, Euroclear, and Northern Trust. Simultaneously, payment giants like Visa integrated USDC settlement capabilities into Visa Direct, processing cross-border transactions at scale. This robust institutional demand generated a downstream effect, funneling massive capital allocations directly into later-stage infrastructure projects capable of supporting enterprise workloads.
Policy Catalysts and Regulatory Maturation
Regulatory developments throughout 2025 played a crucial role in reducing barriers to institutional entry. Reports from DBS Bank indicate that the third quarter marked a decisive pivot from policy consultation to active execution, catalyzed by legislative milestones such as the GENIUS Act and official recommendations regarding stablecoin usage and asset tokenization in banking and payments.
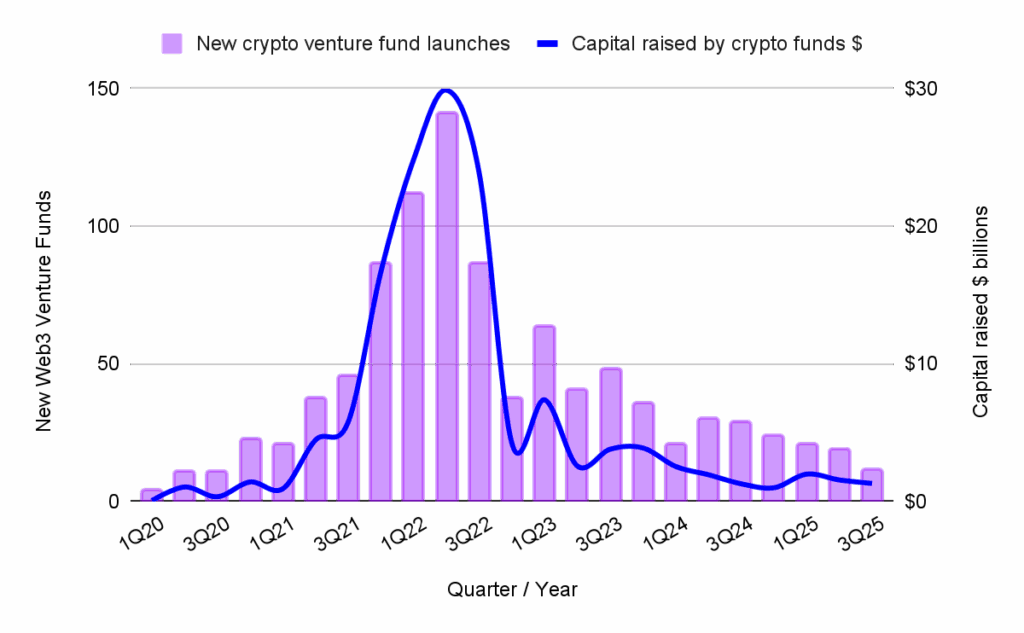
Despite improving regulatory clarity, institutional capital allocators continue to operate under strict governance frameworks, fiduciary mandates, and return expectations. Deploying small ticket sizes across an extensive portfolio of early-stage, unproven startups remains operationally inefficient for large asset managers. Furthermore, career risk discourages decision-makers within traditional institutions from backing speculative ventures without established product-market fit or regulatory compliance.
To bridge this structural gap, the market has seen an increase in hybrid investment vehicles. Strategic partnerships—such as the collaboration between Outlier Ventures and Morgan Creek—exemplify how traditional asset managers can gain structured exposure to early-stage Web3 ventures by leveraging specialized due diligence, technical expertise, and portfolio management frameworks.
Stage-by-Stage Funding Dynamics: Pre-Seed Squeezed, Seed and Series A Resilient
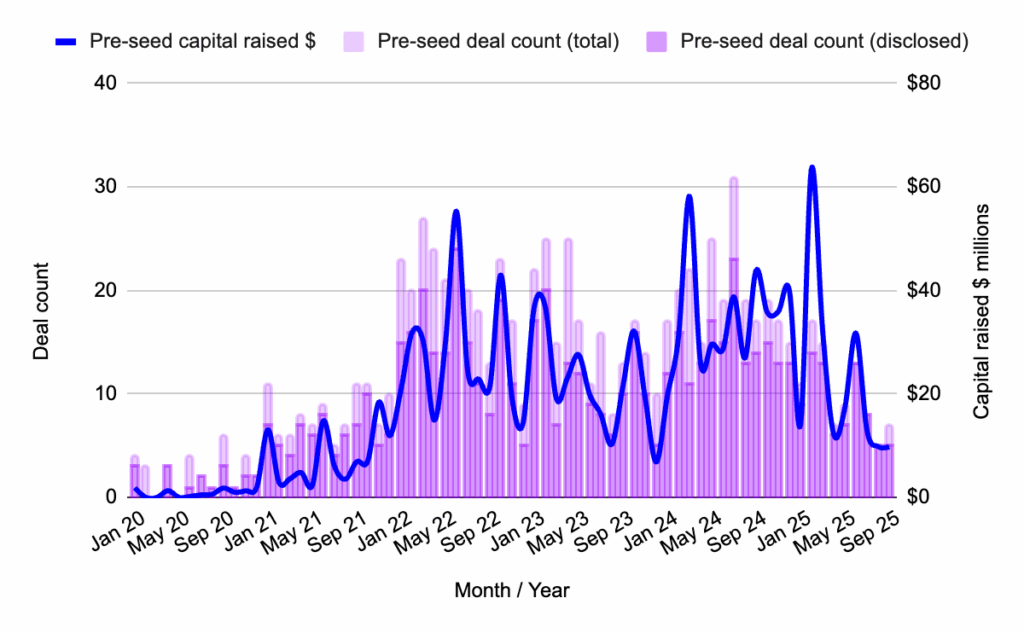
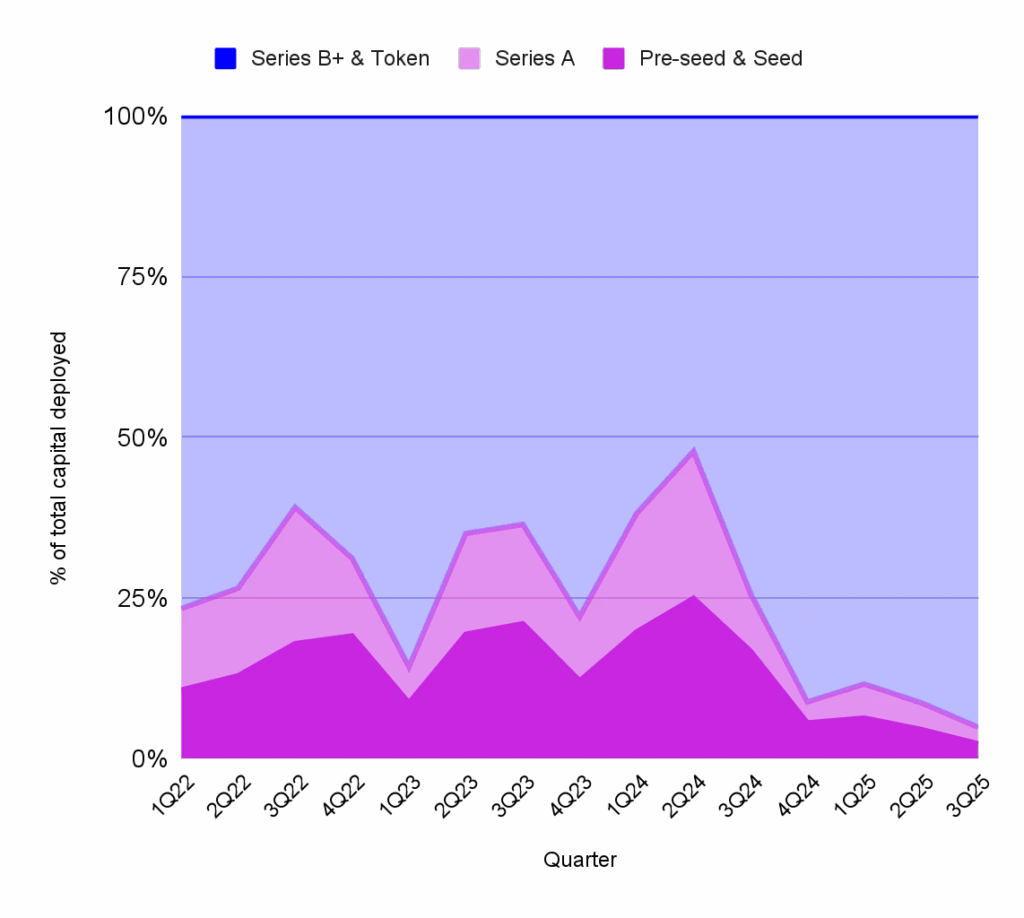
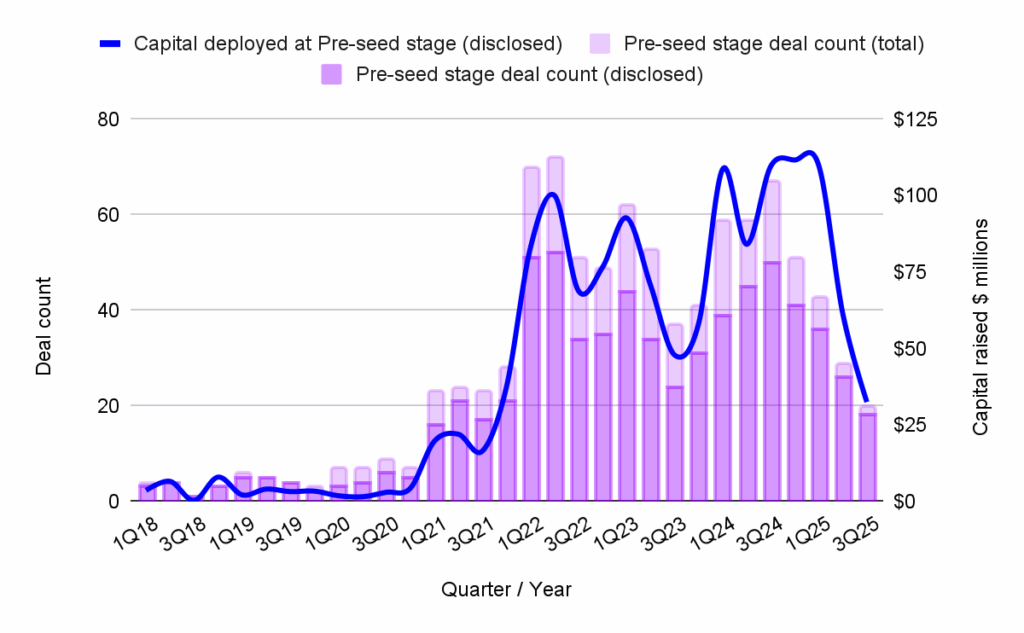
Despite record-breaking headline figures, early-stage fundraising experienced stark bifurcations across funding rounds. Pre-seed financing sank to a multi-year low, logging just 18 disclosed rounds totaling $32.5 million, accompanied by a decline in accelerator activity. This contraction reflects a highly restrictive funnel for founders at the earliest ideation stage.
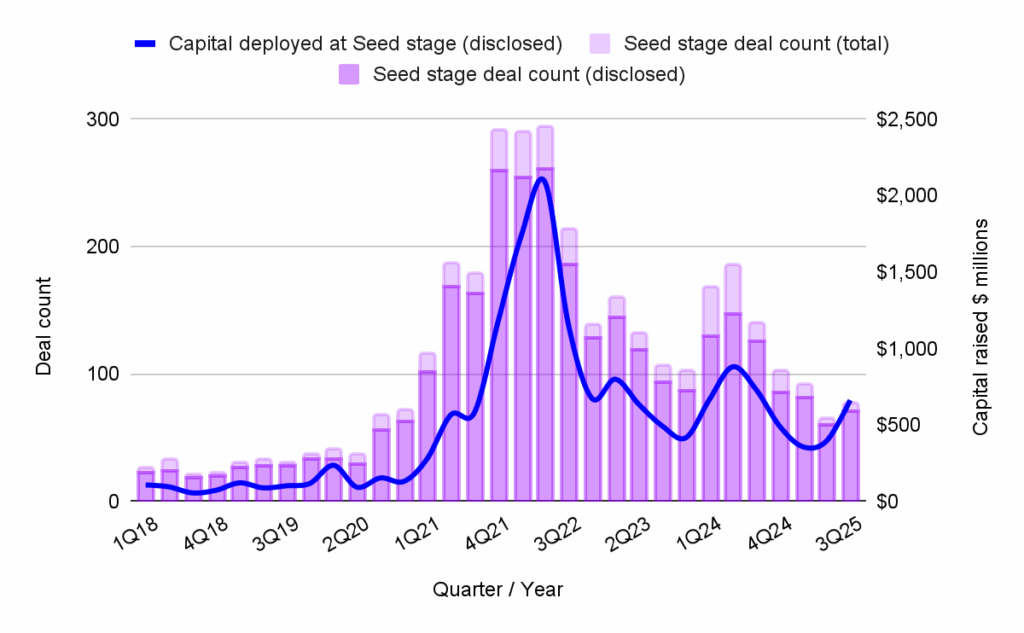
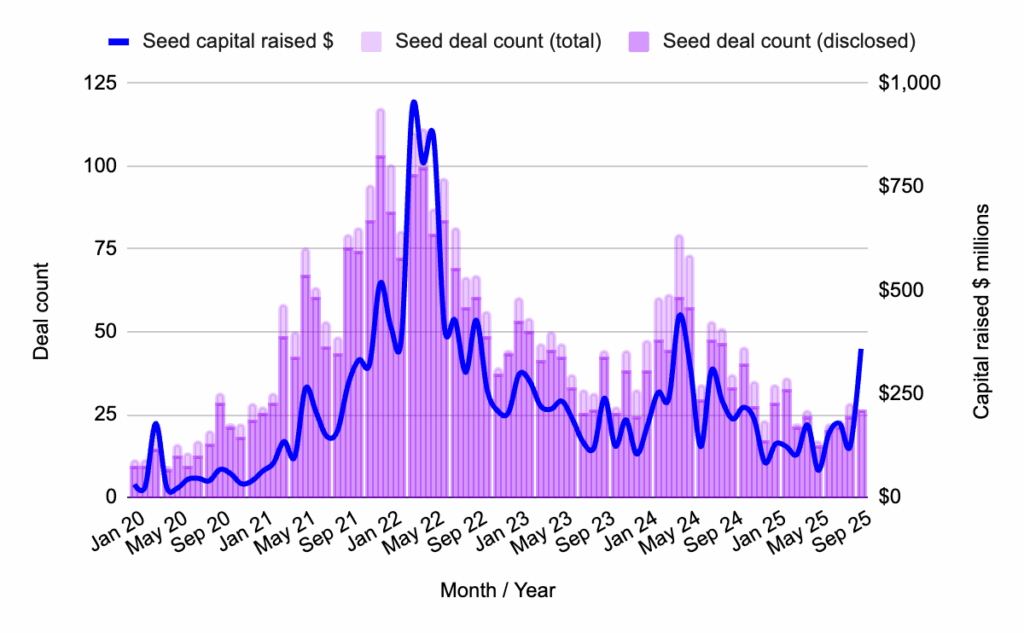
Conversely, seed-stage fundraising recorded 71 disclosed rounds totaling nearly $663 million. However, this figure was heavily skewed by outlier transactions, most notably Flying Tulip’s $200 million raise, which accounted for nearly a third of total seed capital for the quarter. The structure of the Flying Tulip round highlighted a growing preference among investors for liquid, capital-efficient financial instruments over traditional simple agreements for future equity (SAFEs). By incorporating on-chain redemption rights, the financing provided investors with yield-bearing exposure akin to callable treasury assets rather than illiquid equity.
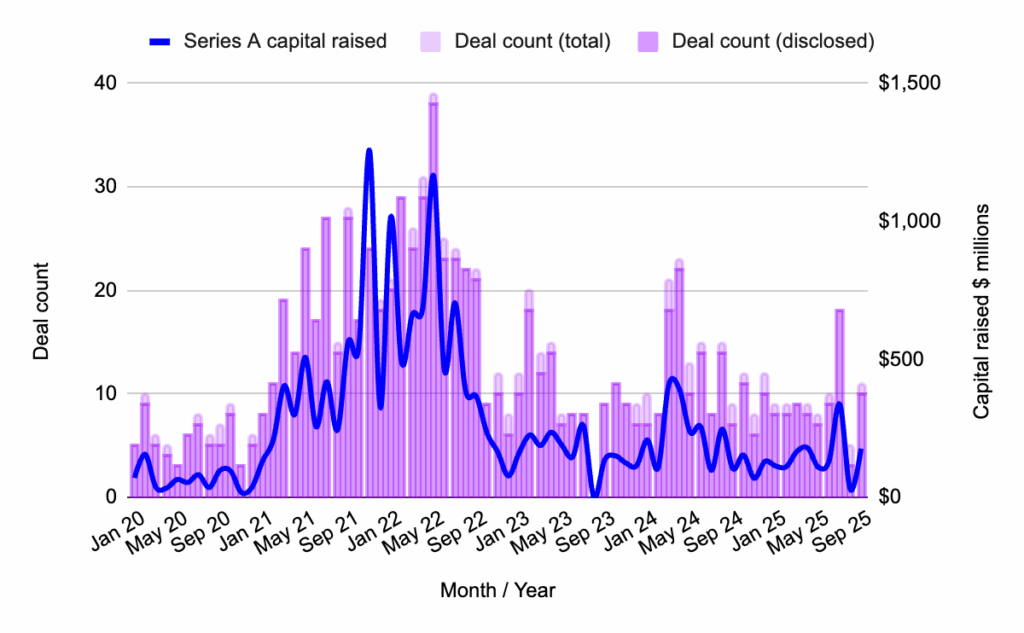
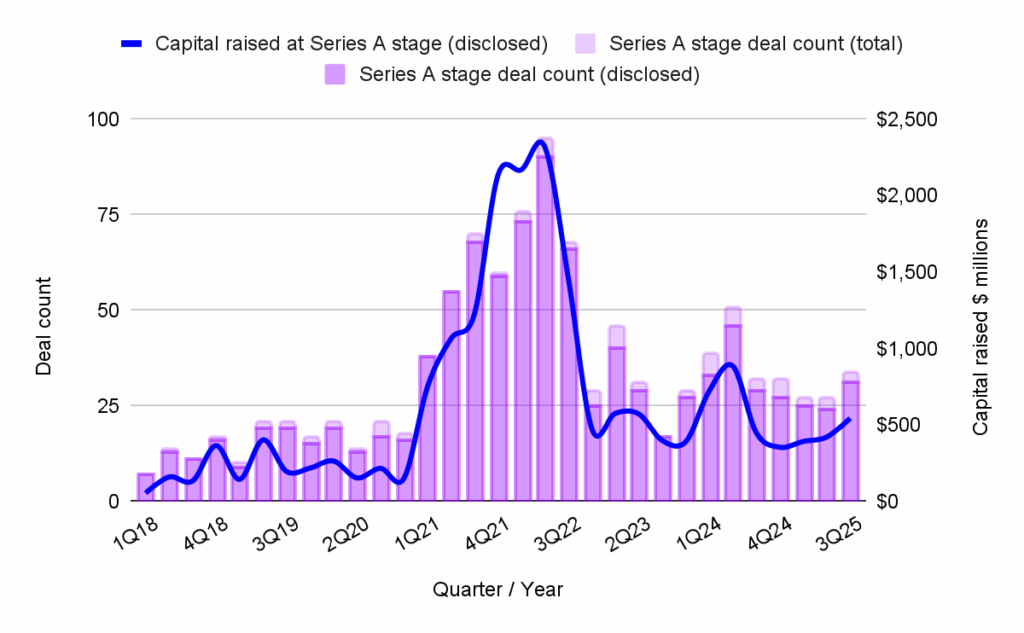
Series A fundraising demonstrated relative stability, logging 31 disclosed rounds totaling approximately $545 million, with a consistent 12-month running median of around $16 million. Analysts note that capital at this stage favored projects directly aligned with institutional rails, including enterprise infrastructure, data services, and tokenization platforms.
Category Breakdown and the Dominance of Infrastructure
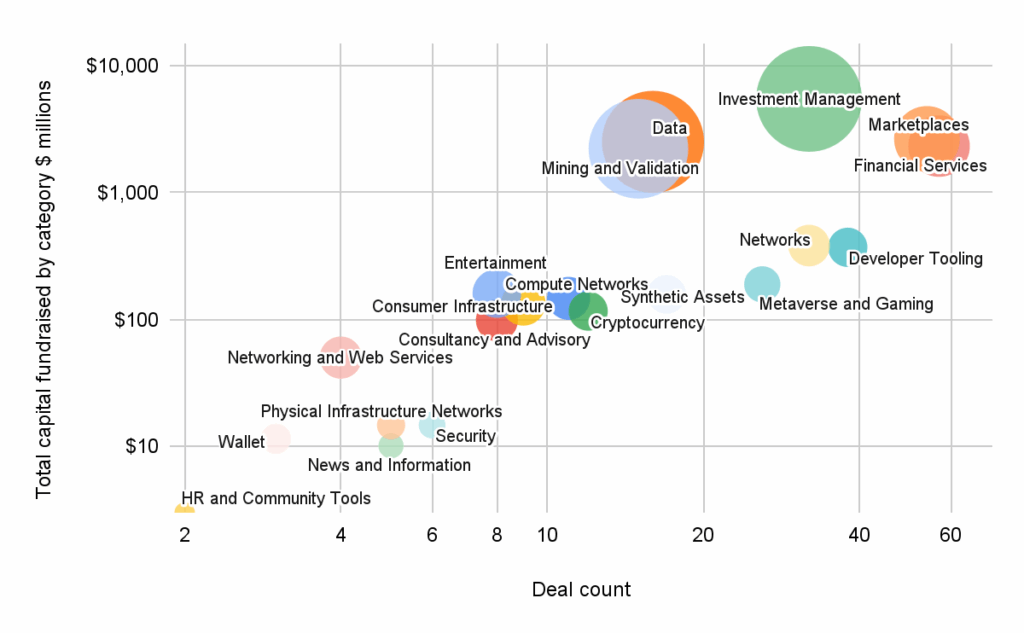
Capital deployment across all stages demonstrated a clear institutional preference. Investment management, marketplaces, data infrastructure, financial services, and mining and validation absorbed approximately 70 percent of all venture dollars deployed in the third quarter. These sectors form the foundational architecture required for asset issuance, custody, settlement, analytics, and blockspace supply.
Data infrastructure startups secured substantial rounds, driven by growing demand for indexing, enterprise analytics, and AI-adjacent blockchain stacks. Grayscale Research formalized AI-crypto as a distinct investable segment, preventing capital from fragmenting across unproven consumer experiments and instead directing it toward scaled data platforms. Conversely, consumer-centric sectors such as metaverse gaming and wallet security remained peripheral, underscoring a broader venture market preference for compliance-ready, revenue-generating enterprise infrastructure over retail speculation.
Private Retreat and Public Rebound in Token Fundraising
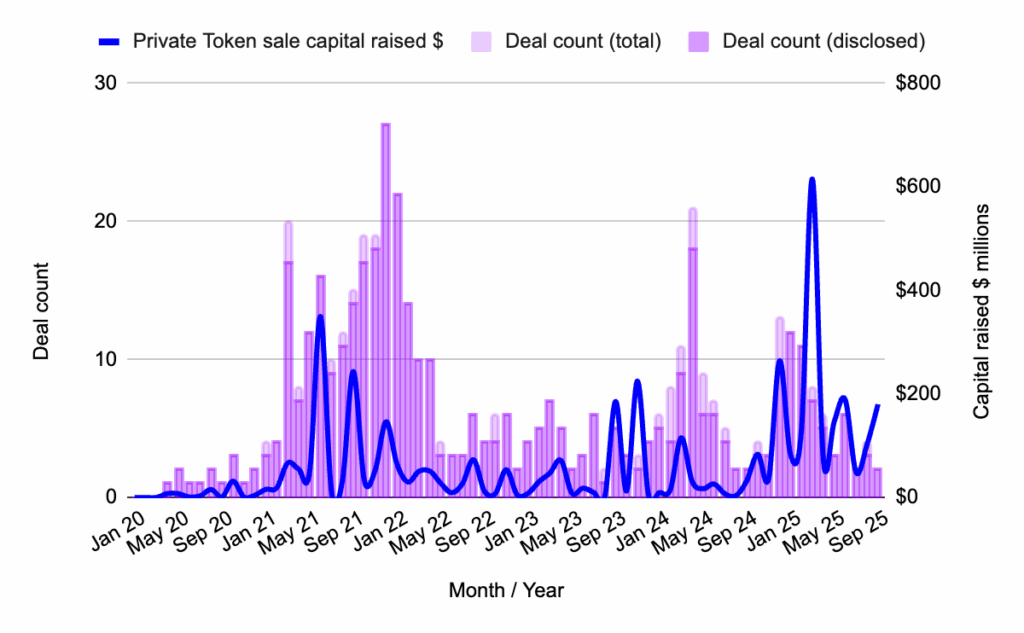
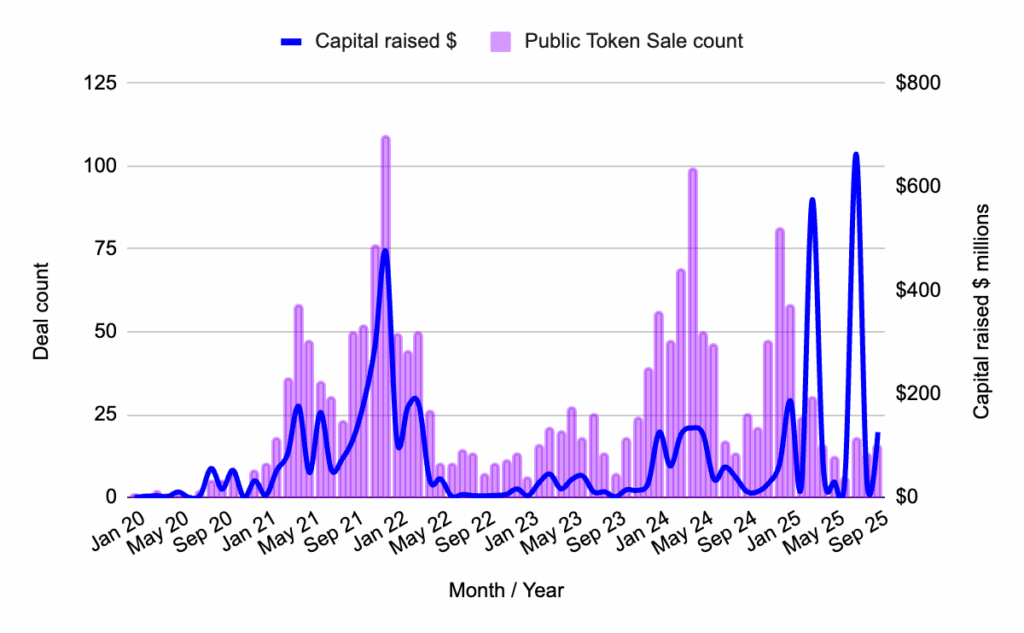
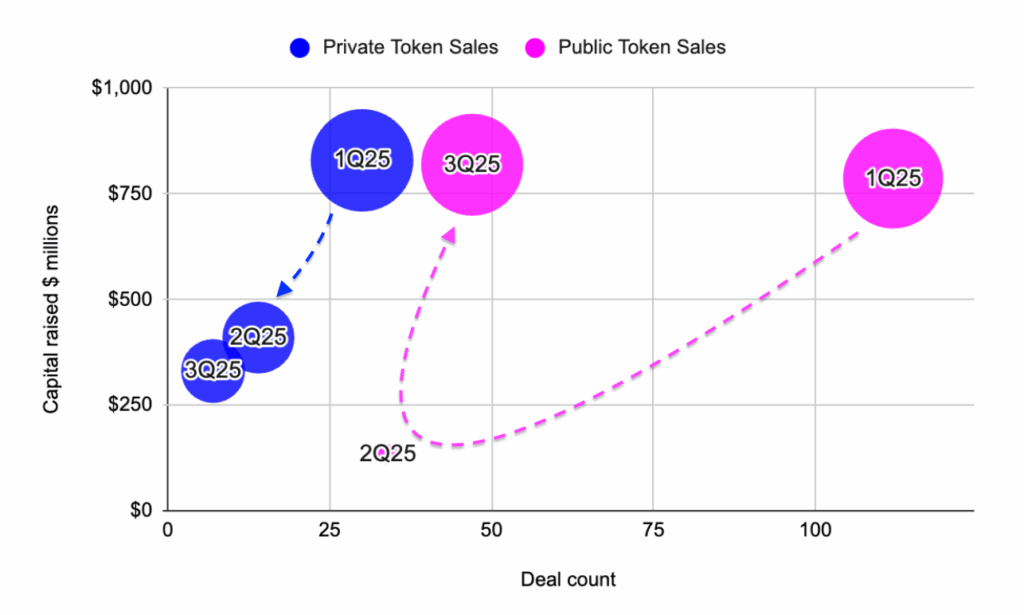
The third quarter of 2025 also witnessed a notable shift in token fundraising dynamics, characterized by a retreat in private token sales and a robust rebound in public distribution mechanisms. Public token sales climbed to 47 events totaling $819 million, while private token sales contracted to 7 events totaling $331 million.
As overall market capitalization and trading volumes expanded—as documented in CoinGecko’s Q3 industry report—crypto projects increasingly utilized public token generation events for efficient price discovery and community decentralization. Furthermore, initial public offerings (IPOs) re-emerged as vital indicators of market health. According to Tiger Research, public listings function as regulatory compliance certification marks for institutional capital access, signaling that public markets are increasingly receptive to digital asset exposure.
Outlook and Future Implications for the Web3 Ecosystem
The record-breaking performance of the third quarter of 2025 underscores a fundamental maturation of the digital asset economy. While consumer-facing applications continue to search for mainstream retail traction, the institutionalization of the infrastructure layer has firmly embedded blockchain technology within the traditional financial system.
As the market transitions into the final quarter of 2025 and looks toward 2026, early-stage founders face the imperative of demonstrating undeniable product utility, traction, and regulatory alignment. Venture capital firms and institutional allocators alike must navigate the structural challenge of supporting early-stage innovation while adhering to stringent risk mandates. How the industry solves these pipeline and capital structure challenges will ultimately dictate whether liquidity remains narrowly concentrated within institutional infrastructure or successfully broadens to encompass the next generation of decentralized innovation.