
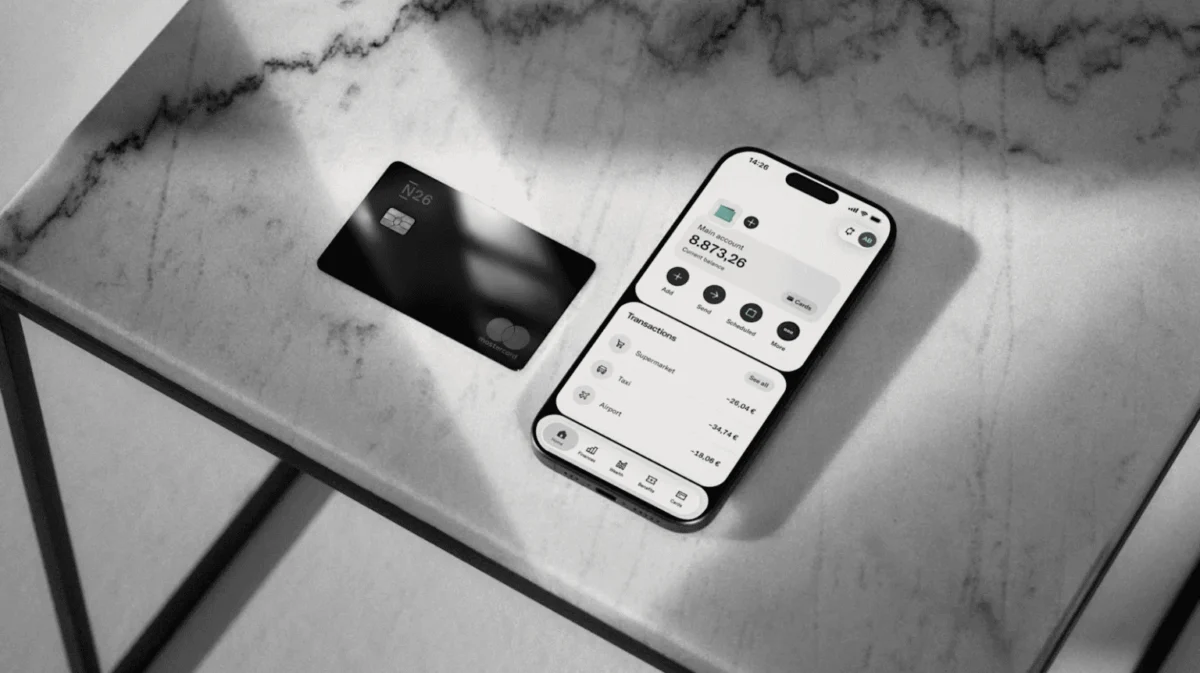
N26, the Berlin-based digital banking powerhouse, has officially unveiled Aura, its most premium and exclusive account tier to date, marking a significant evolution in its service offerings. This launch represents a strategic pivot for the fintech giant, transitioning from a traditional digital bank toward an integrated financial lifestyle platform. By introducing Aura, N26 is attempting to capture the high-net-worth segment of the digital banking market while simultaneously bundling a suite of lifestyle subscriptions that positions the bank as a central hub for the modern, professional consumer’s daily digital life.
Priced at €55.00 per month, the Aura account sits at the pinnacle of N26’s product hierarchy, effectively tripling the cost of its previous top-tier Metal account. This bold pricing strategy places N26 in direct competition with other neobank titans, most notably Revolut’s Ultra tier, which is currently priced at €65 per month for new German subscribers. By undercutting its primary competitor by €10, N26 is signaling an aggressive push to secure market share among affluent users who prioritize convenience, status, and value-added services over traditional, fee-based banking models.
A Chronology of N26’s Strategic Evolution
The trajectory of N26 since its inception has been one of rapid expansion, periodic consolidation, and a relentless focus on feature diversification. Founded in 2013 by Valentin Stalf and Maximilian Tayenthal, the company initially disrupted the German banking sector by offering a frictionless, app-first interface that bypassed the bureaucratic hurdles of legacy institutions.
- 2013–2015: N26 is founded in Berlin with the mission of creating a mobile-first banking experience. It officially launches its first products in 2015.
- 2016–2019: The bank experiences hyper-growth, expanding across multiple European markets and raising significant venture capital to fuel its scaling efforts.
- 2020–2021: N26 achieves a milestone valuation of over $9 billion during a funding surge, solidifying its status as a European fintech unicorn.
- 2022: Facing regulatory pressure and operational headwinds, the company makes the difficult decision to exit the United States market to focus exclusively on strengthening its European core.
- 2023–2024: N26 shifts its focus toward sustainable growth, tightening operational efficiency and investing in product diversification, including crypto trading and insurance.
- 2025: A watershed year for the bank as it reports its first full year of profitability, generating €501.6 million in revenue and a net income of €1.6 million.
- 2026 (November): The official launch of N26 Aura, marking the bank’s most significant premium product expansion to date.
Deconstructing the Aura Value Proposition
The Aura tier is not merely an account with higher limits; it is an ecosystem-focused membership. Beyond the aesthetic appeal of a ceramic mirror-finish payment card—a deliberate departure from the standard metal cards popularized by the first generation of neobanks—the tier includes a robust package of benefits designed to justify the monthly recurring cost.
Key features of the Aura membership include:
- Lifestyle Bundling: Access to premium subscriptions for Amazon Prime, Google AI Pro, and NordVPN, among others.
- Travel Perks: Unlimited access to global airport lounges, providing a luxury travel experience that appeals to the bank’s target demographic of frequent business and leisure travelers.
- Investment Incentives: Up to 15 free monthly trades, lowering the barrier to entry for users who integrate wealth management into their daily banking routines.
- Enhanced Service: Priority support channels, reflecting the "exclusive" nature of the product.
By bundling these services, N26 is attempting to mitigate the "subscription fatigue" that many consumers face. By centralizing these payments under one premium bank account, the company creates a "sticky" user experience where the cost of leaving the bank becomes significantly higher due to the loss of integrated lifestyle perks.
Official Perspectives and Strategic Rationale
"The launch of N26 Aura marks a major milestone in our broader strategy to further evolve N26 from a bank into a fully integrated financial platform," said N26 CEO Mike Dargan during the launch event. Dargan emphasized that the modern consumer’s lifestyle is fluid, requiring a banking partner that adapts to shifting needs. "How our customers live, work, and express themselves is fluid, and Aura is designed to fit naturally into that modern rhythm—combining our highest tier of banking with an elevated, seamless banking experience," he added.
From a corporate strategy perspective, the launch of Aura is a calculated risk. By targeting the premium segment, N26 is looking to increase its Average Revenue Per User (ARPU). In the current economic climate, where interest rate fluctuations and regulatory compliance costs weigh heavily on digital banks, generating high-margin, recurring subscription revenue is essential for long-term viability.
Industry analysts observe that the move into premium lifestyle banking is a common trend among successful neobanks that have reached a critical mass of users—in N26’s case, over 5.6 million revenue-relevant customers. After achieving profitability in 2025, N26 is now transitioning from a phase of "survival and growth" to one of "value extraction and retention."
Broader Market Implications and Competitive Dynamics
The digital banking landscape in Europe is increasingly crowded and commoditized. When basic banking services like current accounts, instant transfers, and currency exchange become standard, digital banks must differentiate themselves through brand perception, ecosystem integration, or exclusive perks.
The "Financial Super-App" model, popularized by Asian fintech giants like WeChat and Grab, has been the holy grail for Western neobanks. By integrating services—from insurance and crypto to lifestyle subscriptions—N26 is moving closer to this model. If Aura proves successful, it will likely influence how other European digital banks structure their premium tiers, potentially leading to an arms race of perks and bundled services.
However, the strategy is not without its risks. The €55 price point is significant for a personal banking product, and the success of Aura depends heavily on whether the included lifestyle subscriptions align with the actual usage patterns of the bank’s most affluent customers. If users find that the bundled services are redundant or do not offer enough utility, the high cost could lead to customer churn, particularly if competitors offer more modular, customizable options.
Furthermore, the initial restriction of the Aura account to the German market suggests that N26 is taking a cautious, phased approach to its rollout. By testing the waters in its home market, the company can refine its offering, measure engagement, and address potential technical or operational friction before considering a broader expansion across its 24 European markets.
Financial Health and Future Outlook
N26 enters this new phase from a position of relative strength. Having survived the volatile "growth-at-all-costs" era of fintech, the bank has demonstrated an ability to turn a profit. The financial data from 2025 provides a stable foundation: a revenue stream of over half a billion euros and a successful pivot away from the high-burn US market to focus on European dominance.
The bank’s ability to maintain this momentum will depend on its capacity to balance the "lifestyle" aspects of its business with the regulatory rigors of being a fully licensed European bank. As N26 continues to innovate, it will likely face increased scrutiny from financial regulators regarding the safety of these bundled services and the transparency of its subscription models.
As of November 2026, Aura is available to both personal and business customers in Germany. For the millions of existing N26 users, the question remains whether the transition to an "Aura" lifestyle is the next logical step in their digital banking journey. The move represents a critical test for N26: can it evolve from being a user’s primary bank into being their primary digital service provider? If the answer is yes, N26 will have successfully redefined its role in the European financial ecosystem, setting a new standard for what a premium banking experience entails in the digital age.

