
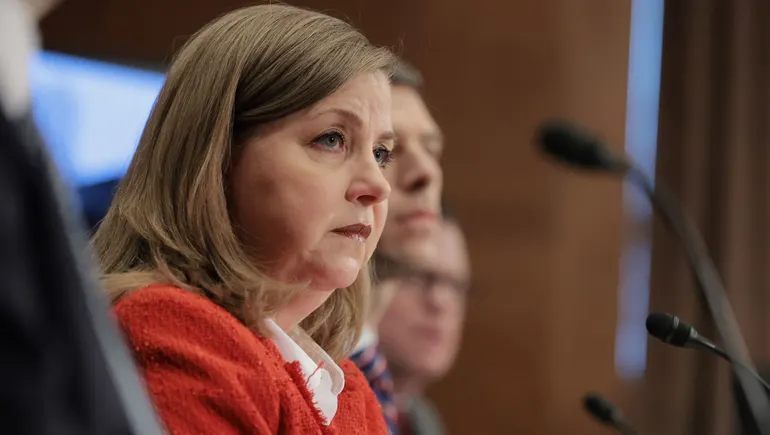
In a high-profile address delivered at a luncheon in London this past Friday, Federal Reserve Governor Michelle Bowman outlined a comprehensive strategy to modernize the central bank’s approach to bank stress testing. Her remarks, which arrived at a critical juncture for U.S. financial regulation, signaled that the Federal Reserve is nearing the conclusion of a long-standing effort to refine how it measures the resilience of the nation’s largest financial institutions. By linking these technical regulatory shifts to a sobering retrospective on the 2023 collapse of Silicon Valley Bank (SVB), Governor Bowman provided a rare glimpse into the internal pressures currently shaping the Fed’s supervisory agenda.
The address touched upon three core pillars: the impending finalization of new capital requirements, the implementation of more rigorous and transparent stress-test methodologies, and a candid admission that the systemic oversight of mid-sized banks—specifically SVB—had suffered from institutional paralysis and a lack of accountability.
The Looming Regulatory Timeline
Governor Bowman confirmed that the Federal Reserve is preparing to release final revisions to its stress-testing framework within the coming weeks. This announcement is of significant interest to the financial sector, as it marks the conclusion of a multi-year effort to revise risk-based capital requirements. These updates include adjustments to the stress capital buffer (SCB) and the surcharge applied to global systemically important banks (G-SIBs), a framework often referred to as the "Basel III Endgame" in U.S. regulatory circles.
The path to these final rules has not been without friction. Last week, the Federal Reserve and Governor Bowman were named as defendants in a lawsuit filed by the advocacy group Better Markets. The plaintiffs allege that the rulemaking process—specifically regarding capital requirements originally proposed in March—has been compromised by irregular interactions between Fed officials and banking executives. Despite this legal hurdle, Bowman’s comments suggest that the Fed remains committed to its current trajectory, aiming to codify these rules before the end of the calendar year to provide banks with a clearer, albeit more stringent, regulatory roadmap.
Refined Methodologies for the 2027 Cycle
A significant portion of Bowman’s address was dedicated to the technical intricacies of the Federal Reserve’s annual stress tests. Historically, these tests have been criticized by both banks and independent analysts for being "black boxes"—complex, opaque models that yield results with little clarity on the underlying assumptions.
To address these concerns, Bowman highlighted two specific proposals currently under consideration. The first involves establishing a "frozen" balance sheet date. Under current rules, bank balance sheets are evaluated based on their composition at a specific point in time, but the lack of a standardized freeze date has often led to inconsistencies. By creating a definitive window for the snapshot, the Fed hopes to improve the accuracy of its projections.
The second proposal centers on the introduction of dual global market shock scenarios. Currently, the Fed applies a single scenario to calculate potential losses. By running two distinct shocks and utilizing the higher loss calculation for the stress capital buffer, the Fed intends to build a larger margin of safety into the system. Furthermore, Bowman announced that the Fed is soliciting public comment on a revised model for evaluating noninterest income, specifically targeting the fee and trading revenues generated through wealth management and market-making activities. This change is slated for integration into the 2027 testing cycle.
"In finalizing these reforms, we will finally close the book on an opaque and unnecessarily unpredictable framework," Bowman stated. She emphasized that the goal is to transform the stress test from a one-way, punitive exercise into a collaborative dialogue that allows for proactive risk management.
The Silicon Valley Bank Post-Mortem
The most poignant moment of the address involved Bowman’s retrospective on the collapse of Silicon Valley Bank. She argued that the current supervisory failures were not necessarily due to a lack of data, but a failure of institutional culture.
According to Bowman, an independent review of the SVB failure—which sent shockwaves through the global banking system in March 2023—revealed that Fed supervisory staff were aware of the bank’s interest rate risk and deposit concentration as early as March 2022. However, internal hesitation prevented any decisive regulatory action. The report cited a pervasive culture of "risk aversion" within the Fed, where staff members were more concerned with avoiding the procedural risks of taking an incorrect action than with the systemic risk of taking no action at all.
This ambiguity extended to the chain of command, as the review found that staff members were often unclear about which officials held the authority to force a bank to correct its capital or liquidity vulnerabilities. Bowman characterized this as a failure of leadership and procedure that ultimately eroded public trust in the central bank’s ability to act as an effective supervisor.
Data and Implications: A Shift in Supervision
The implications of Bowman’s remarks extend far beyond mere technical adjustments to testing models. By advocating for "scenario analysis" that identifies vulnerability to nonfinancial risks—such as operational and cyber risks—before they manifest into crises, the Fed is signaling a transition toward a more forward-looking, qualitative approach to supervision.
Supporting this shift is the reality of the post-2023 economic environment. The failure of SVB occurred in an era of rapid interest rate hikes, where the unrealized losses on "held-to-maturity" securities effectively wiped out the bank’s capital base. Bowman noted that had the proposed stress tests been applied in 2021, the simulation would have flagged that SVB’s capital would fall below minimum requirements due to rising interest rates, long before the bank’s liquidity crisis began.
Industry analysts suggest that this transition will necessitate a larger workforce within the Fed’s supervisory arm, requiring more frequent, in-depth communication between examiners and bank risk officers. The shift also suggests that the Fed may become less reliant on strictly quantitative, model-driven metrics and more willing to exercise "supervisory judgment" to force mid-sized banks to hold more capital.
Broader Market Reactions
While the banking industry has generally welcomed the prospect of a more transparent and predictable stress-test framework, the trade-off is an environment where capital requirements are likely to remain elevated. Banking lobbyists have historically argued that excessive capital requirements limit credit availability and stifle economic growth. Conversely, consumer advocacy groups maintain that the current levels are necessary to protect the deposit insurance fund and prevent taxpayer-funded bailouts.
The lawsuit against the Fed and the scrutiny regarding the SVB collapse suggest that the central bank is caught between two fires: the need to maintain rigorous, modernized oversight and the pressure to ensure that such oversight is transparent and free from political or lobbying influence.
Conclusion: Lessons Learned
Governor Bowman concluded her address by emphasizing that the objective of the current reforms is not to assign blame for past failures, but to build a more resilient financial architecture. The era of the "opaque" stress test appears to be drawing to a close, replaced by a mandate for clarity, responsiveness, and earlier intervention.
As the Federal Reserve prepares to finalize its rules in the coming weeks, the industry will be watching closely to see how these changes are calibrated. If the Fed successfully balances its desire for higher capital buffers with a more transparent, predictable methodology, it may succeed in restoring the confidence that was so severely damaged in the spring of 2023. However, as Bowman herself acknowledged, the ultimate test of these reforms will not be found in the boardroom or the laboratory of a model, but in the Fed’s future ability to detect and mitigate the next unforeseen crisis before it reaches the point of collapse.
